
Our economy came down with a very nasty dose of 'seasonal flu' in the middle of 2024.
It is, however, now undoubtedly making its way back to better health with the help of some 'medicinal' lower interest rates.
We get the latest health check on NZ Inc in the coming week with the release of GDP figures for the March quarter on Thursday, June 19. And the latest update should show the recovery that began towards the end of last year has continued and perhaps broadened.
As we would well recall, our economy fell into a substantial hole in the middle of last year, with back-to-back GDP falls of 1.1% for both the June 2024 and September 2024 quarters.
In very simplistic terms this was the economy crying 'enough' after the Reserve Bank had ramped the Official Cash Rate up all the way from 0.25% in late 2021 to 5.5% by May 2023 and kept the rate at that level in order to squeeze the life out of inflation, which had peaked at 7.3% in mid-2022.
Well, this not only squeezed the life out of inflation, but out of the economy too. However, with inflation last year 'cornered' once again in the targeted 1% to 3% range, the RBNZ began dropping the OCR in August 2024, and it is now down to 3.25%.
Till pretty recently many of the major bank economists would have been expecting to see another OCR cut at the next review on July 9. However, more recent economic data has tended to be exceeding economists' expectations. And indeed this week some of the main bank economists significantly upgraded their forecasts for the March quarter GDP outcome after stronger-than-they-expected results from so-called 'key partial indicators', particularly manufacturing and wholesale trading figures.
This has been the not-so-pretty picture of our GDP performance in the past year:
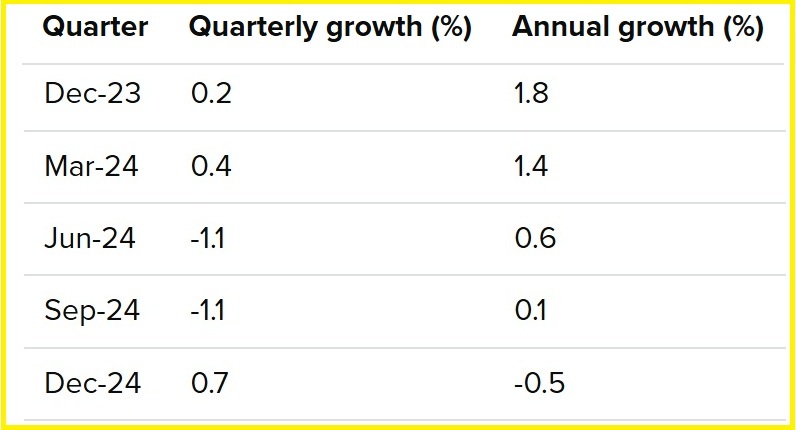
Undoubtedly that December quarter 0.7% rise in GDP was something of a relief. And there's a fair chance the March quarter figure could be a 0.7% rise as well, or close to it.
The RBNZ has forecast just a 0.4% rise. However, this forecast, contained in the RBNZ's latest Monetary Policy Statement (MPS) issued on May 28 was made without the benefit of seeing the most recent GDP-related 'partial' economic data.
If GDP has indeed risen by 0.7% in the March quarter - and therefore comfortably exceeded the RBNZ's forecast - then there's an increased chance the RBNZ will push the 'pause' button at the July 9 OCR review.
What a good result could mean
Westpac senior economist Michael Gordon summed all this up thus: "Our 0.7% growth forecast is an upgrade from our previous estimate of 0.4%, following the final batch of sectoral data that was released on Monday. Other market forecasters have shifted their views in the same direction, and the RBNZ (which forecast a 0.4% rise in its May Monetary Policy Statement) would likely be thinking the same at this point. Combined with the RBNZ’s declaration of “no bias” going into the 9 July policy review (and no quarterly CPI until after that date), a better-than-expected GDP result would make a strong case for leaving the OCR unchanged on that occasion."
So, what of this 'partial' data that's been released? What has it been telling us to give clues as to the likely outcome for GDP?
The volume of total manufacturing sales rose 2.4% in March, following a 1.2% rise in the December 2024 quarter. Wholesale trade sales rose a seasonally adjusted 3.2% after a 1.7% rise in the December quarter.
The seasonally adjusted volume of building work done in the March quarter was flat, which doesn't sound great. It does, however break a sequence of six consecutive quarters of falls.
Retailers have been struggling as we know, but retail trade volumes rose 0.8% in the March quarter after rising 1.0% in the December quarter.
And, as we also know, our primary industry exports have been going fabulously, particularly in dairy, meat, fruit and wood products.
'Two-speed economy'
ASB economist Wesley Tanuvasa and senior economist Mark Smith, who also pick a 0.7% March quarter rise for GDP, say there seems to be "a two-speed economy at play".
"Overall, the starting point for 2025 GDP is expected to be higher than the RBNZ’s May MPS assumption. We think downside growth risks still have credence because what’s driving growth is vulnerable to a tariff hit. Around 37% of total exports (goods and services) are to the US and China. The NZ economic outlook is dependent on whether exporters can diversify that concentration of demand over 2025. We are less convinced the external sector can maintain such momentum in a trade war. However, a higher starting point for GDP and the modest repair of interest-rate sensitive sectors like construction, suggest a turning point," they say.
"That’s a good news story in a sea of bad news stories. On balance, a more resilient economy supports our view that the RBNZ will pause in July. However, evidence of a kiwi-driven rebound is key to buttress the economic recovery ahead – if household spending isn’t sufficiently kickstarted by mortgages refixing to lower rates over the year, the RBNZ may have to relitigate its ‘neutral’ bias regarding easing."
I think we are at a very interesting stage. As I've noted before, the key thing this year was always going to be how quickly the economy would start to perk up once interest rate reductions began to properly kick in - and therefore how low the RBNZ would have to go.
A little earlier this year there seemed a fairly substantial body of thought that the RBNZ may have to take the OCR down to about 2.5% later this year - but in fact much of the economic data has come out stronger than, certainly the main bank economists, had expected. Will that continue though?
More money in pockets
As the ASB economists note above there does appear to be a two speed economy. Perhaps that's only to be expected. Any recovery was always likely to start in specific areas of the economy and broaden. Some of the strong primary industry returns - particularly in things such as dairy - are seeing debts being reduced and more money being put in pockets. In time that should boost spending.
So, a 0.7% growth figure for GDP in the forthcoming week would be very welcome if that's what the outcome is. But more important than the number will be the underlying detail of just how well or otherwise various parts of the economy are doing. We do want to see evidence that any recovery is becoming more broad based. And so does the RBNZ.
If the RBNZ becomes more confident that the economy is getting better, it's possible we might not see the OCR go much lower than 3.25%. And therefore the banks will be more constrained in offering future mortgage rate reductions.
If the details of the GDP release in the coming week suggest any recovery is 'brittle' then further OCR reductions may well be seen as warranted.
But assuming the number that comes out on Thursday, June 19 is a reasonably good one, it certainly is looking very likely there will be at least a 'pause' in any OCR cuts at the next review on July 9. Whether that 'pause' ends up becoming a 'halt' to the easing cycle we will have to wait and see. Plenty to watch out for.
*This article was first published in our email for paying subscribers early on Friday morning. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.