
Here's our summary of key economic events overnight that affect New Zealand, with news markets don't seem to be worrying about coming 'bad news' ahead of tomorrow's US March labour markets report.
US initial jobless claims recorded a minor +2000 rise last week from the week before taking the total to 1.94 mln. But that was a big -74,000 decrease as more benefits expired than new ones were added. A year ago there was almost the same number of initial claims as last week.
Updated American job cut data remains incredibly low even if it is rising. US-based employers announced plans to cut 90,300 jobs in March, the most since January 2023, compared to 84,600 in February.
Tomorrow we get the March non-farm payrolls data and markets expect employer payroll jobs growth to rise +200,000. You will recall they rose +275,000 in February.
Meanwhile US exports of both goods and services were +2.1% higher in February than in January. Imports were +2.2% higher on the same basis so the overall trade balance grew fractionally in the month, although year-to-date, the goods and services deficit decreased -2.8% and remains about -2.7% of US GDP. (New Zealand's current account deficit is -6.9% of GDP.)
Canada also reported trade data for February but only for goods trade and their exports rose +5.8% to a new all-time high. Imports rose +4.6%, so their merchandise trade surplus rose to +C$1.4 bln in February.
It is a public holiday in China, Ching Ming Festival, although Hong Kong financial markets will reopen today.
Global container freight rates continued their retreat from their late January peak. They are now down -28% since then, down -3% in the past week alone. But that leaves them still +65% higher than year-ago levels. The slowness of the recent easing points out that the twin problems in both the Panama Canal (drought) and Suez Canal (security) are not going away; the decreases are because the global logistics system is adapting. Bulk cargo rates eased -7% in the past week, and are in fact now back to long-run average levels.
Steel and iron ore prices are back falling, both near their lowest in the past year, probably an early signal markets don't believe Chinese demand will recover any time soon.
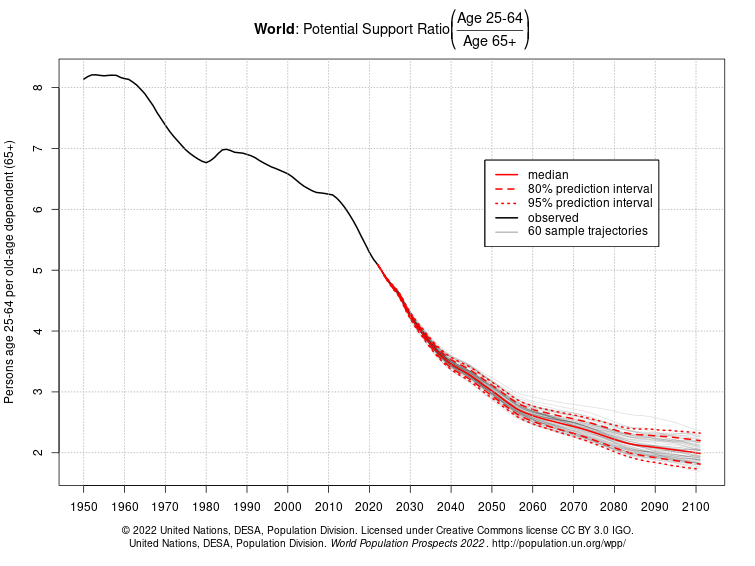
And speaking of commodities, a new report says the world's population is shifting in very significant ways in an historical turning point. Also, it is not simply a matter of a static or a declining world population – the nature of that population will also change. It will be much older. The report estimates there will be twice as many people over 80 as under five – nearly 900 million over-80s worldwide by 2100. A period of unprecedented demographic and economic adaption awaits our grandchildren. There seems little doubt that small countries will have many more options than large ones, but that the pressures from 'outside' will be enormous.
And speaking of natural stresses, keep an eye on Sydney weather this weekend. They seem to be facing a rather extreme meeting of two wild and wet weather fronts.
The UST 10yr yield is now at 4.35% and little-changed from this time yesterday. The key 2-10 yield curve inversion is also little-changed at -34 bps. And their 1-5 curve inversion is still at -70 bps. Their 3 mth-10yr curve inversion is now at -102 bps and virtually unchanged as well. The Australian 10 year bond yield is now at 4.19% and up +3 bps. The China 10 year bond rate is holding at just under 2.30%. The NZ Government 10 year bond rate is now at 4.72% and up +2 bps.
Wall Street has opened its Thursday session up +0.2% although that is a retreat from a much bigger rise earlier. The reversal was probably due to this interview. European markets were generally in positive territory with Frankfurt up +0.2%, Paris unchanged, and London was up +0.5%. Tokyo ended its Thursday session up +0.8%. Hong Kong and Shanghai were closed for their public holiday. The ASX200 rose +0.5% but the NZX50 ended another -0.5% lower yesterday.
The price of gold will start today softer by -US$5 from this time yesterday at US$2288/oz. But in between it hit a new all-time high of US$2305/oz.
Oil prices have fallen -US$1 to just under US$84.50/bbl in the US while the international Brent price is now up at just under US$89/bbl.
The Kiwi dollar starts today at just on 60.4 USc and +¼c firmer than this time yesterday. Against the Aussie we are softer at 91.3 AUc. Against the euro we are firmer at 55.6 euro cents. That all means our TWI-5 starts today just on 69.4 and up +20 bps from this time yesterday.
The bitcoin price starts today firmer at US$68,048 and up +2.7% from this time yesterday. Volatility over the past 24 hours has been moderate at just on +/- 2.3%.
Daily exchange rates
Select chart tabs

The easiest place to stay up with event risk is by following our Economic Calendar here ».

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.