

Here's my Top 10 links from around the Internet at 1 pm in association with NZ Mint.
I'll pop the extras into the comment stream. See all previous Top 10s here.
I welcome your additions in the comments below or via email to bernard.hickey@interest.co.nz.
Just imagine if the Greeks asked for the war reparations the Germans have yet to pay...

1. Where did all the money go? - The Times reports on a hastily withdrawn Peoples Bank of China report on how over 15,000 corrupt Chinese officials pulled US$120 billion out of China from the mid 1990s to 2008 and laundered it through various countries, including Australia.
How sure are we that the Chinese money now buying our farms and businesses and luxury houses hasn't been stolen from the Chinese government in some form?
I hope the Overseas Investment Office has the resources to do these checks...
And are our banks also doing all the necessary checks when accounts are set up here?
HT Stephen via email.
The research, whose revelations of corruption are breathtaking even by Chinese standards, estimates that between 16,000 and 18,000 officials may have fled the country with monumental hoards of ill-gotten money between the mid-1990s and 2008.
In one paragraph, the report, which had the words “internal data, store carefully” on the front page, cautioned that unchecked corruption was putting communist rule at risk. “It is a direct threat to the cleanpolitics structure of the Communist Party and harms the foundations of its power,” it said.
Large amounts of the money, along with the officials who amassed it, headed for Australia or the US.
2. Big cash call - Reuters reports Europe's banks may need to raise over 50 billion euros to comply with new tougher capital rules under Basel III. This is partly because hybrid debt known as contingent capital has been excluded by the masters of the banking regulation universe at Basel.
Bank shares hit a low for the year as lenders in France and Germany may be most in need, adding to fears their capital could be strained by losses on holdings of Greek bonds and loans to the troubled euro zone country.
"Capital will become a critical competitive issue. The race to compete for capital has begun," Deutsche Bank AG Chief Executive Josef Ackermann told a Reuters conference in Frankfurt on Monday. A capital surcharge of between 1 percent and 2.5 percent for the biggest systemically important banks agreed by global regulators at the weekend was in line with or slightly less than expectations.
"SIFIs (systemically important financial institutions) will in markets be perceived as very secure. We are therefore very happy to belong to the SIFIs," Ackermann said.
But the exclusion of a hybrid form of debt known as contingent capital (CoCos), which converts to equity in times of stress, to comply with the surcharge is a disappointment to many banks and investors, analysts said.
"The quid quo pro of a lower charge (than expected) appears to be the fact that CoCos cannot be used toward the surcharge -- it must be made entirely of equity capital," said Andrew Lim, analyst at Espirito Santo. Not allowing CoCos will be an unwelcome surprise for those managers and investors who had seen them as the solution to recapitalizing the sector, said Antonio Guglielmi, analyst at Mediobanca.

3, August 2 getting closer - America will default on August 2 if its debt ceiling is not increased. CNN reports there is no progress and it's getting a little tight...
CNN's Jeanne Sahadi looks at what might happen.
If Congress fails to raise the debt ceiling by Aug. 2 -- the day when the Treasury Department estimates it will no longer be able to pay all the country's bills -- any number of damaging and utterly preventable scenarios could occur. For starters, the United States would look ridiculous. The debt ceiling needs to be raised because of obligations that Congresses past and present chose to incur.
Not raising the ceiling would signal to the world that Americans are willfully choosing not to pay their bills. The message won't be "We can't pay." It will be "We could pay, but we've decided not to. Sorry."
To date, investors have been trading on the assumption -- the rock-solid belief, actually -- that there is just no way Congress would fail to raise the debt ceiling in time. If Congress dashes those expectations, no one can know exactly how the markets will react. But most think markets will react, and not well. Some bond experts expect that contrary to popular belief, Treasury rates won't rise but stocks may tank. In other words, there will be a move out of risk-based assets and a flight to safety in bonds.

4. Extend and pretend version 607 - The BBC's Robert Peston reckons there's plenty of flaws in the latest French bank plan to roll over 70% of Greek debt. It is promoted as a European version of the Brady Bonds that helped fix Latin America's debt problems in the 1980s.
But here's Peston explaining why they're a pale imitiation of Brady Bonds.
The original Brady scheme was a genuine path to recovery for countries that had borrowed far more than they could afford to repay. By contrast, the new French version is aimed at sustaining the claim - which many bankers and investors regard as a dangerous fiction - that Greece can afford to repay all the €340bn it owes.
Broadly the French scheme would do little more than extend the maturity of Greek debt. But it would do nothing to reduce the crippling burden of all that debt on Greece.
Its aim is to protect both private-sector lenders to Greece, especially the banks, and public-sector lenders to Greece, such as the European central bank and eurozone governments, from taking losses on their Greek loans.
However, most bankers and investors would say that unless and until private or public sector lenders to Greece - or both - are prepared to incur such losses, and reduce what Greece owes them, then neither Greece or the eurozone will be cured of the great financial disease afflicting them both.

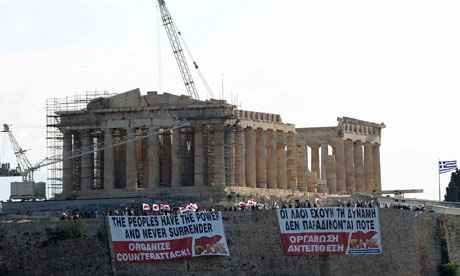
5. Greek strikes - The Guardian reports on the latest Communist action in Greece and the likelihood of two days of mayhem this week as the Greek parliament votes on the austerity plan.
The vote is expected on Wednesday. Meanwhile, there are more meetings expected tonight between EU bankers and officials on how banks might participate in any 'voluntary restructure' that must never be referred to as a default.
The word default now has the same status in these discussions as Voldemort or Macbeth.
Upping the ante, unions have declared a 48-hour general strike starting on Tuesday – the first two-day walkout since the collapse of military rule and the return of democracy in 1974 – to coincide with parliament's debate on the measures. Mass rallies have been scheduled in 65 towns during the two days that Greek politicians will discuss the belt-tightening policies.
"It will be two days that have never seen before," said Stathis Anestis of the General Confederation of Greek Workers, the country's largest labour force.
6. The problem with FTAs - The Guardian reports Philip Morris is using Australia's free trade agreement with Hong Kong to sue Australia to stop it from introducing brand-free packaging plastered with pictures of rotten toes and diseased lungs.
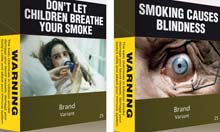 This is another reason why an FTA with America is a bad idea.
Here's what Philip Morris is saying:
"If no mutually agreeable solution is found, then it proceeds to us seeking compensation. We estimate the damage will potentially amount to billions of Australian dollars," a spokeswoman for Philip Morris Asia told Dow Jones Newswires.
"Brands are valuable intellectual property and form the basis of consumer goods businesses like ours. If we are banned from using them, our business in Australia will become commoditised and its value will be significantly impacted.
"The Australian government does not have an unfettered right to confiscate [our] valuable intellectual property. Moreover, the government has failed to demonstrate that plain packaging will reduce smoking prevalence."
7. Lower for longer - Tom Lauricella has written an excellent piece at the Wall St Journal about how the weight of debt in developed economies is suppressing growth and interest rates for much longer than is 'normal'.
Another effect is that interest rates could stay exceptionally low for much longer than would usually be the case, says former World Bank official and author Liaquat Ahamed, whose book, Lords of Finance, examined monetary policy in the 1920s and 1930s. He notes rates have been essentially zero in Japan since 1995 and that during the Great Depression, the Federal Reserve cut the discount rate to below 2 per cent in 1934 and it held at those levels until the mid-1950s.
History shows "that when people have borrowed too much, they stop borrowing and interest rates stay very low for a very long time", he says. "So you can forget about investing in bonds."

8. Germans not so righteous - Der Spiegel warns that Germany has actually been the biggest bankrupt of the last century and is in no position to come across to the Greeks and others as holier than thou.
German economic historian Albrecht Ritschl actually thinks that if Germany pushes too hard then countries like Greece could come back to Germany and ask for reparations unpaid after World War Two.
He's not kidding.
From 1924 to 1929, the Weimar Republic lived on credit and even borrowed the money it needed for its World War I reparations payments from America. This credit pyramid collapsed during the economic crisis of 1931. The money was gone, the damage to the United States enormous, the effect on the global economy devastating.
SPIEGEL ONLINE: The situation after World War II was similar.
Ritschl: But right afterwards, America immediately took steps to ensure there wouldn't be a repeat of high reparations demands made on Germany. With only a few exceptions, all such demands were put on the backburner until Germany's future reunification. For Germany, that was a life-saving gesture, and it was the actual financial basis of the Wirtschaftswunder, or economic miracle (that began in the 1950s). But it also meant that the victims of the German occupation in Europe also had to forgo reparations, including the Greeks.
Ritschl: In the 20th century, Germany started two world wars, the second of which was conducted as a war of annihilation and extermination, and subsequently its enemies waived its reparations payments completely or to a considerable extent. No one in Greece has forgotten that Germany owes its economic prosperity to the grace of other nations.
SPIEGEL ONLINE: What do you mean by that?
Ritschl: The Greeks are very well aware of the antagonistic articles in the German media. If the mood in the country turns, old claims for reparations could be raised, from other European nations as well. And if Germany ever had to honor them, we would all be taken the cleaners. Compared with that, we can be grateful that Greece is being indulgently reorganized at our expense. If we follow public opinion here with its cheap propaganda and not wanting to pay, then eventually the old bills will be presented again.

9. The Big Fat Greek Gravy Train - Arch euro-sceptic The Daily Mail has done a "special investigation into the EU-funded culture of greed, tax evasion and scandalous waste."
It starts by looking at how hardly anyone in Athens pays for their train tickets, which means the rail system collects 80 million pounds in revenues and pays out 500 million pounds in wages.
Fiddling on a Herculean scale — from the owner of the smallest shop to the most powerful figures in business and politics — has become as much a part of Greek life as ouzo and olives. Indeed, as well as not paying for their metro tickets, the people of Greece barely paid a penny of the underground’s £1.5 billion cost — a ‘sweetener’ from Brussels (and, therefore, the UK taxpayer) to help the country put on an impressive 2004 Olympics free of the city’s notorious traffic jams.
The transport perks are not confined to the customers. Incredibly, the average salary on Greece’s railways is £60,000, which includes cleaners and track workers - treble the earnings of the average private sector employee here.
Ridiculously, Greek pastry chefs, radio announcers, hairdressers and masseurs in steam baths are among more than 600 professions allowed to retire at 50 (with a state pension of 95 per cent of their last working year’s earnings) — on account of the ‘arduous and perilous’ nature of their work.
After issuing warnings last year, government officials say he is set to deploy helicopter snoopers, along with scrutiny of Google Earth satellite pictures, to show who has a swimming pool in the northern suburbs — an indicator, officials say, of the owner’s wealth.
Officially, just over 300 Kifissia residents admitted to having a pool. The true figure is believed to be 20,000. There is even a boom in sales of tarpaulins to cover pools and make them invisible to the aerial tax inspectors.

10. Totally Irrelevant Carp Attack video - You gotta see this to believe it.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.