

Here are the key things you need to know before you leave work today (or if you already work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
None to report again today.
TERM DEPOSIT/SAVINGS RATE CHANGES
In case you missed it late yesterday, ANZ raised most term deposit rates for terms to 1 year, nothing longer. That makes their new six month rate 5.00% and their new one year rate 5.50%. ASB made similar moves today. SBS Bank raised its 6 & 9 month offers, and ended its 6% one year offer. A review of the TD market is here.
FONTERRA IMPRESSES
Fonterra reported profits up +50% in their half-year review, ROE was up to 8.6%, and they declared a 10c interim dividend. They say earnings are strong despite lower NZ milk volumes and ongoing market volatility. They note success is coming from scale and their ability to shift milk to higher earning segments and products.
BROAD-BASED ECONOMIC WEAKNESS
Economic activity declined more quickly than expected in Q4-2022. Household consumption was flat, government consumption fell, investment spending fell, exports fell, imports rose. Less upbeat spending and investment highlight that demand is weakening, which is a necessary evil to get inflation back under control, notes Infometrics. If there is a 'positive' is is that nominal GDP exceeded $101 bln in Q4, the first time any quarter has breached the $100 bln level. Inflation pushed that.
A SUCCESSFUL BOND TENDER
Fifty out of 105 bids won something at the latest Treasury bond tenders. The May 2028 $200 mln attracted $680 mln in bids and went for a 4.35% yield, well below the 4.61% at the equivalent event two weeks ago. The April 2033 $150 mln got $538 mln in bids, also going for a yield of 4.35% and also down from 4.60% two weeks ago. The Mau 2051 $50 mln went for 4.60% yield, little-changed from the 4.63% two weeks ago even though it attracted $103 mln in bids. Overall $920 mln of demand went unsatisfied today.
A FAILED CARBON TENDER
Yesterday we noted the failed carbon tender where no units were allocated because no bidder fronted up with a price above the Government's [secret] reserve level. We have more on this story here. Today, secondary market trading has the price at $67.35/NZU which is probably still below yesterday's reserve.
RIDERS GIVE UP ON AT
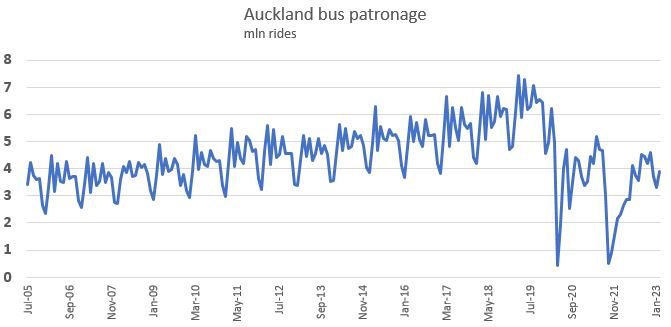
Auckland bus patronage continues to languish, undermined by WFH, cancellations, and poor service. Half fares have not rejuvenated it. You can see a long-run chart of bus ridership here, through to the end of February 2023. Auckland Transport is struggling to win back riders. Depending on the month they have lost between -2 and -5 mln rides per month from the pre-pandemic peak.
AUSSIE JOBS MARKET STRENGTHENS
In Australia, their labour market came in stronger in February than expected with +64,600 extra jobs or which +75,000 were full-time positions, and part-time roles fell more than -10,000. Their jobless rate fell to 3.5% while their participation rate was unchanged at 66.6%. (NZ is 3.4% and 71.7% respectoively.)
SWAP RATES TURN BACK DOWN
Wholesale swap rates are probably slightly lower today. However, the real action in swap rates comes near the close. Our chart will record the final positions. The 90 day bank bill rate is down -8 bps at 5.01% and now only +26 bps above the current OCR. The Australian 10 year bond yield is now at 3.37% and down -9 bps from this tiem yesterday. The China 10 year bond rate is little-changed at 2.89%. And the NZ Government 10 year bond rate is now at 4.40% and down -2 bps from this this time yesterday and still well above the earlier RBNZ fix at 4.28% which was down -8 bps from yesterday. The UST 10 year is down further today at 3.49 with a -19 bps drop from this time yesterday. Any sense of calm yesterday disappeared today with the European banking wobbles.
EQUITIES LEAK VALUE
Wall Street ended its Wednesday session down -0.7% and that was a lot less of a fall than the earlier session suggested. At one point it was down a full -2.0%. Year to date it is up +1.8%. From its peak at the end of 2021 it is down -18.3%. The NZX50 is down -0.1% in late trade. This is nothing like the -1.8% mid afternoon fall on the ASX200. Tokyo has opened down 0.9%. Hong Kong has opened down -1.9%. Shanghai has opened down -0.4%.
GOLD FIRM
In early Asian trade, gold is up +US$7 from this time yesterday at US$1910/oz, although it was higher intra-day earlier.
NZD SOFTER
The Kiwi dollar is -½c lower than where we were this time yesterday, now at 61.7 USc as the greenback rises on safe-haven flows. Against the Aussie we are a little softer at 93 AUc. And against the euro we are up slightly at 58.2 euro cents. That means the TWI-5 is down to 70.2 and a -40 bps slip from yesterday.
BITCOIN LESS VOLATILE
The bitcoin price has moved little today, a second day with only a minor change, now at US$24,374 and down -1.6% from this time yesterday. Volatility has been moderate today at +/-2.8%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs

This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.