The global bond markets are a sensitive lot. And they’ve been having a particularly tricky time lately.
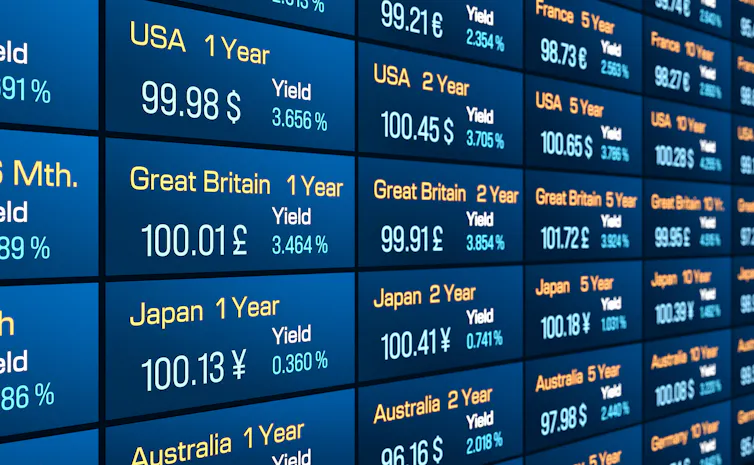
Spooked by high inflation, high interest rates and high levels of government debt across the world, those markets have become less stable over the summer. The prices of government bonds – what governments sell to investors – have gone down. And yields – the amount of interest governments need to pay to those investors over a set period of time – have gone up.
This means it’s now more expensive for governments to borrow the money they need to pay for all the things governments need to pay for.
In the US for example, the interest rate that investors charge the government for a ten-year bond has risen to 5%, its highest level for almost 20 years. Ten-year borrowing costs in the UK and France are also at their highest levels since before the global financial crisis of 2008.
Some analysts blame governments themselves for this rise because of their persistent budget deficits, where spending outstrips tax revenues, forcing them to lean heavily on bond markets to plug the gap.
But budget deficits have been commonplace for years. Neither the UK nor the US has managed to run a budget surplus since 2001.
So why are global financial markets only now beginning to react?
A big part of the answer lies in an imbalance between the demand for borrowing and the supply of capital available to finance it.
Governments have borrowed heavily from capital markets for much of the past two decades and, until recently, faced relatively limited competition for that capital.
But the boom in AI investment is beginning to change this. Companies, particularly in the US, are borrowing heavily – to the tune of trillions of dollars – from financial markets to fund the construction of data centres and investment in AI research and development (plus the infrastructure needed to support it).
So governments are no longer the only big borrowers at the table.
And while global capital markets are enormous, the pool of money available to lend is not infinite. As governments and companies compete for that capital, investors can demand a higher return for providing it. The result is higher borrowing costs across the economy – including for governments.
Benchmarks for borrowing
The level of government bond yields provide an important benchmark for borrowing costs across the economy – for businesses and households.
For governments, higher bond yields increase the cost of servicing government debt. That can effectively reduce spending on public services as money is diverted away from education and healthcare in order to pay the interest on outstanding debt. In the US, official forecasts predict that the government cost of paying interest on its debt will double over the coming decade.
US debt interest payments already cost more than annual military spending.
This is why relatively small movements in government bond yields can matter so much. The rise in US ten-year yields from 4.3% to 5% may not sound dramatic, but when those higher borrowing costs are applied across trillions of dollars of debt, the consequences for the taxpayer can quickly become significant.
And bond markets, once provoked, can be hard to placate.
With the current enormous appetite for AI investment, something will need to change.
For years, governments have been able to rely on global financial markets to finance persistent deficits relatively cheaply. But this cannot be taken for granted. As competition for capital intensifies, governments may increasingly find that investors are no longer willing to finance ever-growing borrowing needs on such favourable terms.
Comments by the US treasury secretary, Scott Bessent, that the US government deficits had probably peaked ended up being a source of much derision in financial centres around the world.
Bessent has since tried to back his warm words with hard action by announcing a US$6 billion programme (£4.5 billion) to bring down borrowing costs by buying back bonds. But given that US government debt stands at over US$40 trillion, it will have a limited effect.
Higher tax revenues or lower government spending would certainly help. And an improvement in the long-term fiscal outlook could reassure investors that government borrowing is on a more sustainable path, helping to bring borrowing costs back down.
The difficulty is that good fiscal economics can make for bad politics. Voters rarely thank governments for raising taxes or cutting public spending, particularly when the benefits may not become apparent for several years.
Politicians therefore face an uncomfortable choice. They can take difficult decisions today to reassure bond markets, or postpone them and risk paying a higher price for borrowing tomorrow.
Alex Dryden, PhD Candidate in Economics, SOAS, University of London. This article is republished from The Conversation under a Creative Commons license. Read the original article.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.