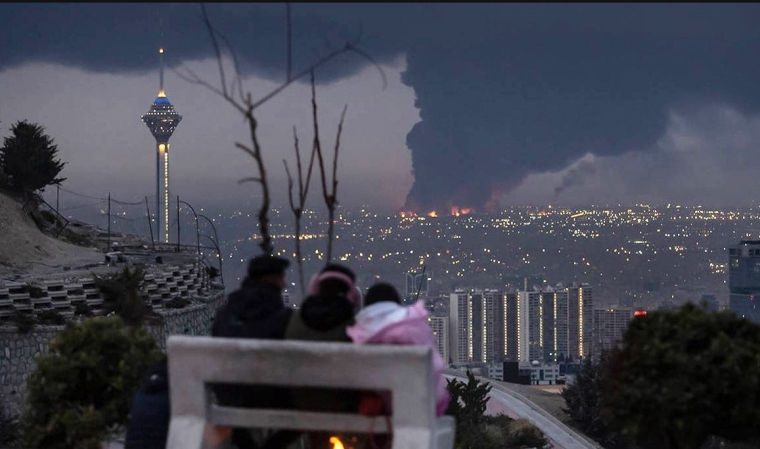
Despite the rising risks, uncertainties, and large negative supply shocks of the last two years, stock markets and the overall global economy have held up quite well. Following the shock of US President Donald Trump’s “Liberation Day” (April 2) tariffs in 2025 came this year’s Iran War, which caused the largest energy shock since the oil crises of the 1970s.
Yet, according to International Monetary Fund data, global growth was as high in 2025 as it was in 2024 (3.5%), and global inflation was lower in 2025 than in 2024. And while global growth is expected to slow to 3% this year, it is projected to recover (to 3.4%) in 2027, with inflation returning toward its 2025 level in 2027 after rising in 2026.
What explains the global economy’s apparent resilience, and what are the biggest downside risks to the relatively benign outlook for 2027?
Four major factors have prevented a downturn. First, market discipline forced the Trump administration to shelve its most stagflationary policies. Average US tariff rates spiked from 2.1% in January 2025 to 21.5% on April 2, 2025, but that triggered a market reaction that forced Trump to blink and negotiate tariff reductions. The average tariff rate is now 9.6%. Likewise, Trump’s decision to go to war against Iran caused an oil-price shock, rising bond yields, and a stock-market correction, leading him to negotiate a fragile ceasefire that partly reversed some of the damage.
Second, the tariff and oil shocks were mitigated by adjustments in trade patterns, global supply chains, and other production factors. With many new producers and sources of energy, the world today depends less on oil than in the past. A drawdown in strategic oil reserves (especially in China) and some demand destruction dampened the impact of the shock substantially.
Third, policy responses also helped absorb some of the impact. There was fiscal and monetary easing in many advanced economies in 2025, when growth seemed to be at risk, followed by monetary tightening this year to keep inflation expectations anchored.
Fourth, and most importantly, the world is in the middle of a massive, positive long-term aggregate supply shock, owing to the AI investment boom. The United States and China are the clear leaders, but many other countries in Asia and Europe are also benefiting from this capital expenditures (capex) cycle, which also increasingly includes higher defense spending.
Still, there are tail risks to consider. For starters, geopolitical tensions are high, shipping through the Strait of Hormuz remains constrained and uncertain, and recent Houthi attacks on shipping chokepoints and a Saudi pipeline may further restrict oil and gas supplies. Oil prices have already spiked above $100 per barrel again, and the longer that energy prices remain elevated, the greater the stagflationary pressure.
Moreover, the recent extension of the Sino-American truce may not last if China—and its de facto allies, Russia, Iran, and North Korea—feels emboldened by US geostrategic missteps. Tensions over Taiwan could rise after the island’s elections in 2028, and the Russia-Ukraine conflict is already expanding to a wider theater—with Ukraine striking deep inside Russia, and Russia pursuing hybrid warfare against Europe. Given Ukraine’s targeting of Russian energy facilities, the failure to secure a ceasefire will put additional upward pressure on hydrocarbon prices.
At the same time, liberal democracies are increasingly showing signs of political dysfunction, and upcoming elections in the US, France, Germany, Italy, and Spain could lead to more populist economic policies that would damage growth and introduce greater fiscal risks. Indeed, large fiscal deficits and high debt-to-GDP ratios in many advanced economies and some emerging markets are driving up sovereign bond yields, threatening to crowd out private-sector production, capex, and consumption, and raising the risk of credit crises.
The AI boom is another source of risk—and is showing signs of frothiness. If it proves to be a bubble that must eventually pop or deflate, the result could be negative wealth effects (lower consumption), credit problems, and a loss of animal spirits among investors and households.
On the policy front, stagflationary shocks that reduce growth and increase inflation tend to create a dilemma for central banks with a dual mandate to maintain both price stability and full employment. If they conclude that additional rate hikes are warranted to fight inflation, that may weaken growth and raise financial-stability concerns, given high levels of private and public debt and the risk of debt monetization (“printing money”).
In the baseline scenario, these negative risks remain contained, global economic growth improves in 2027, and inflation falls as productivity-enhancing technological innovations provide a strong tailwind for the global economy. In this case, high bond yields will be driven more by the AI boom than by concerns about inflation or fiscal deficits and debt. Moreover, an easing of geopolitical tensions is certainly possible and would reduce energy prices, creating the conditions for the positive—even double-digit—equity returns of recent years to continue.
But if the big risks do materialize, energy and commodity prices may remain high or rise further, and trade and supply chains could be more severely disrupted. That would significantly raise the risk of a serious market correction, with both higher bond yields and lower equity prices.
The more positive scenario is still the more likely one. Tech tailwinds remain strong, market discipline will still contain the worst policies, and the US and China both seem committed to de-escalating their rivalry. Given the scope of the potential risks, one must hold out hope that the current resilience will continue. Much will depend on political leaders avoiding extremes and not derailing one of the most important technological innovations in human history.
*Nouriel Roubini, Professor Emeritus of Economics at New York University’s Stern School of Business. Copyright: Project Syndicate, 2026, published here with permission.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.