The transfer of the controversial Credit Contracts and Consumer Finance Act (CCCFA) to the Financial Markets Authority (FMA) is apparently not keeping the financial regulator up at night.
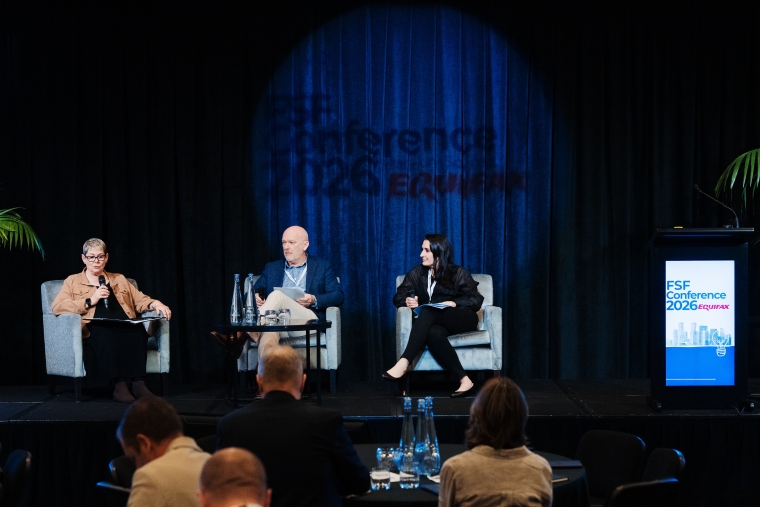
Appearing at the Financial Services Federation conference in Auckland on Friday, the FMA’s Anita Frazer, Helena Lewis and Michael Hewes debriefed on the first 100 days post-CCCFA oversight transfer from the Commerce Commission. They discussed the changes made and what the future with the CCCFA under the FMA will look like for businesses.
The CCCFA is the primary consumer credit law in NZ and regulates mortgages, car loans, personal loans, credit cards and buy now, pay later (BNPL) schemes. Responsibility for regulating consumer credit transferred from the Commerce Commission (ComCom) to the FMA on July 1. The change is aimed at bringing licensed consumer credit providers within a broader conduct framework.
Frazer, the FMA’s head of licensing and regulatory services, said that over the first 100 days, the FMA focused on getting to know the sector, settling its new responsibilities and starting to shape the regulator's approach to consumer credit regulation.
“When CCCFA licensing came into effect, certified and exempt lenders automatically moved to an FMA market services licence, so they could continue operating as credit providers,” she said.
“Since then, we've approved six new credit licences, and that might not sound like a large number, but given my team, we've been very busy.”
Frazer said for many businesses, this is their first experience of licensing, so there's been “plenty to learn” for both the FMA and the licensed sector.
“One of the key things that we've been going over the last 100 days and prior is talking to people, talking with consumer groups, financial mentors, consumer organisations and industry. Those conversations have really helped us understand what's happening on the ground and what consumers and lenders are experiencing,” she said.
The law hasn't changed
Hewes, the FMA’s director of credit, deposit-taking, insurance and advice, told the audience that it was important to remember that while responsibility for the CCCCA has moved from ComCom to the FMA, the law itself hasn't actually changed.
“Responsible lending requirements are exactly the same. Disclosure obligations remain the same. And also consumer protections remain exactly the same. So while we move from one regulator to another, those underlying requirements are exactly the same, and we expect them to go through and continue,” he said.
Lewis, who heads up the regulator’s disclosure and market conduct services, added that the FMA has been focusing on the “broader range of tools” that are available to the FMA compared to what was available to ComCom under the CCCFA.
“But that doesn't mean we're going to jump straight into our formal tools when we see something,” she said.
Under the CCCFA, the FMA can instantly issue a stop order to prohibit a lender from distributing specific information, marketing materials, or supplying a credit service if they believe a CCCFA or fair dealing breach has occurred or is likely to occur.
The FMA can also issue interim stop orders while investigating a lender and directly order them to take specific, reasonable steps to comply with the law, or to change practices to avoid or mitigate the effects of a breach.
“Our starting point is usually engagement,” Lewis said.
“So we'll be talking to firms, we'll be asking questions, we'll be trying to understand. We may carry out a desk-based review, or we may visit a firm to understand how things are working in practice. And then where serious concerns do arise, we do now have a number of other formal tools that we can use, which is actually what I do in my standard role as head of permit and response.”
She added that it was worth lenders remembering that their licences “are not the finish line.”
“So getting your licence is just the beginning. As a licence holder, there are ongoing obligations that you need to be thinking about.”
There was only time for one question from the audience at the end of the FMA discussion: as regulators operating in industry, what is keeping them awake at night? After a pause, the trio all said none of them were losing sleep over any issues.
“It doesn't keep me awake at night, but it challenges me: the new sector that we're looking into, the new complexities that we're learning about. Some of the things that just make me shake my head and go, how can we help in this space?” Frazer said.
FMA's 3 areas of focus include remuneration conflicts
The FMA has three areas of focus for the 2026/2027 year in the consumer credit sector: managing conflicts arising from remuneration structures; complaints processes and handling; and unsuitable or unaffordable lending.
In an open letter the FMA released to consumer credit providers in early October, FMA licensing and conduct supervision executive director Clare Bolingford said that the regulator will also take a particular interest in how boards and/or those responsible for the governance and senior management of lenders oversee risks to fair consumer outcomes.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.