A business owes Inland Revenue $120,000. It is still trading, paying its employees and meeting its current tax obligations. The owner accepts that the debt must be paid.
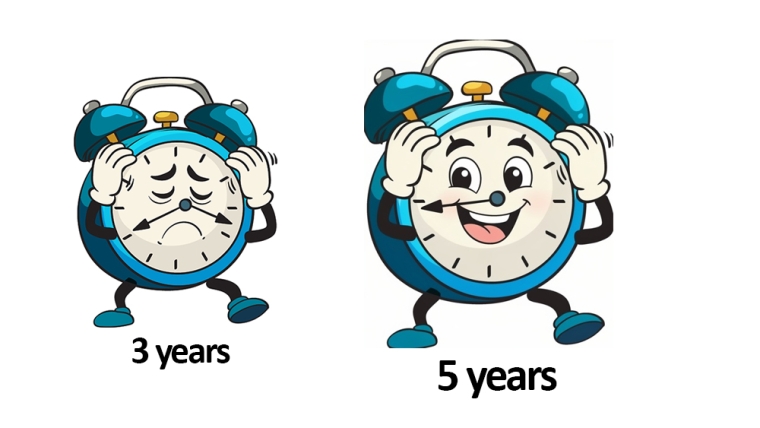
After meeting wages, rent, suppliers and other expenses, the business can afford $2,000 a month towards the outstanding debt. For this illustration, leave interest and other charges aside. At $2,000 a month, it would take five years to repay the principal.
But Inland Revenue generally expects repayment arrangements to be completed within 36 months.
To repay $120,000 over three years, the business would need to pay approximately $3,333 every month. Where does the additional $1,333 come from?
The business cannot simply invent the money. It would have to reduce expenditure, obtain additional finance or divert money needed to keep trading.
If none of those options is realistic, the arrangement may fail.
I encounter this issue in my work negotiating tax debts with Inland Revenue. Often, the question is not whether the taxpayer wants to pay, but whether the proposed payments can actually be maintained.
If a viable business can repay its debt over five years but not three, why should the shorter period generally be preferred?
Three years is not the law
In March 2026, Inland Revenue released draft Standard Practice Statement ED0261, Options for Relief from Tax Debt, proposing to replace its existing guidance. Consultation closed in May, and the draft has not been confirmed as finalised.
Paragraph 39 acknowledges that legislation does not impose a maximum period for an instalment arrangement. Nevertheless, Inland Revenue's general practice is to seek repayment over the shortest possible period, generally no longer than three years.
There are sound reasons for wanting tax debts repaid promptly. Circumstances change, taxpayers’ default and longer arrangements carry greater uncertainty.
But an administrative preference is not a statutory limit.
Section 177B of the Tax Administration Act 1994 allows the Commissioner to enter into instalment arrangements and decline them in specified circumstances, including where an arrangement would not maximise recovery.
The legislation does not say that five years is unacceptable.
In my experience, the 36-month expectation is a real consideration in negotiations. Yet there are circumstances where a longer arrangement could provide a better outcome for both Inland Revenue and the taxpayer.
A promise to pay is not the same as payment
Consider our business owing $120,000. Suppose it agrees to pay $3,333 a month despite having only $2,000 genuinely available.
For a few months, the proprietor may manage by using personal savings, delaying equipment replacement or leaving another creditor unpaid.
Eventually, the money runs out.
After six months, Inland Revenue may have recovered approximately $20,000. The business then defaults, leaving about $100,000 of the original principal outstanding, on our simplified figures.
Compare that with a sustainable five-year arrangement paying $2,000 each month. If completed, Inland Revenue receives the full $120,000 principal.
In a real arrangement, continuing interest and other charges must also be addressed, either through affordable payments or through whatever lawful relief is available.
Of course, five years carries additional risk. The business may fail, trading conditions may change, and interest may continue to accrue. Inland Revenue may also have other lawful recovery options.
Those matters should be assessed against the financial evidence.
But if the longer arrangement has a realistic prospect of success and the shorter one does not, what has been gained by insisting on three years? An arrangement that looks satisfactory on paper is of little value if it collapses after six months.
Why not use technology to monitor longer arrangements?
We now have technology capable of monitoring payments and identifying overdue tax returns electronically.
Why should administering a five-year arrangement necessarily be substantially more difficult or expensive than administering one lasting three years?
A business entering into a longer arrangement could be required to meet its current tax obligations, make agreed monthly payments and provide updated financial information when reasonably required.
An automated system could identify missed payments, overdue returns or newly accumulated tax debt. Those accounts could then be referred to an Inland Revenue officer for review. Accounts where payments and compliance remain satisfactory would require less routine attention.
This is not about replacing human judgment with artificial intelligence. It is about allowing technology to identify which cases actually require human attention.
Section 177B already permits the Commissioner to cancel an instalment arrangement where the taxpayer fails to meet its obligations or obtained the arrangement through false or misleading information.
A longer arrangement would not mean surrendering Inland Revenue's rights. If the taxpayer defaults, the arrangement could be reviewed and, where legally permitted, cancelled. The unpaid balance would remain recoverable. The taxpayer would have been given more time, not forgiven the debt.
Such a system would still require investment, safeguards and human oversight. But if technology can reduce the administrative cost of longer arrangements, that possibility deserves serious consideration.
What happens when a viable business closes?
Consider a business employing six people. It has customers, generates revenue and meets its ordinary operating expenses. Its problem is an accumulated tax debt that it cannot repay within three years.
If the business closes, Inland Revenue may recover only part of the outstanding debt. Closure may also reduce future tax receipts and disrupt employment, although some business activity and jobs may transfer elsewhere
Employees who cannot find alternative work may need assistance from Work and Income. Suppliers may lose a customer or be left with unpaid invoices. The consequences extend beyond the unpaid tax balance.
I am not suggesting that every struggling business should be kept alive. Some businesses are simply not viable. They cannot meet their ordinary expenses, continue accumulating tax debt and have little realistic prospect of recovery.
A payment arrangement cannot turn an unviable business into a viable one.
But there is a difference between that situation and a business that can meet its current obligations, remain profitable and repay its historic debt over a longer period. The wider economic consequences do not override Inland Revenue's statutory responsibilities. They do, however, provide another reason to examine whether a rigid repayment expectation produces the best result.
What should Inland Revenue be trying to achieve?
Section 176 of the Tax Administration Act requires the Commissioner to maximise recovery of outstanding tax. It also recognises circumstances where recovery would be an inefficient use of the Commissioner's resources.
The objective is to collect public revenue, not merely obtain the shortest repayment promise.
Taxpayers who meet their obligations should not be disadvantaged by those who do not. Nor should businesses be allowed to use unpaid GST or PAYE indefinitely to fund their operations. A longer arrangement should therefore be supported by reliable financial information, realistic cashflow forecasts and demonstrated capacity to meet current taxes.
It should also be monitored, with appropriate action when the taxpayer fails to comply.
Inland Revenue's draft practice statement provides an opportunity to consider whether modern technology could make longer arrangements easier to administer without compromising enforcement. I am not advocating automatic five-year arrangements. Nor am I suggesting that Inland Revenue should accept every proposal simply because a taxpayer wants more time.
There will be cases where three years is appropriate. There will be cases where five years is unrealistic. But where a viable business can repay over five years and cannot do so within three, that proposal deserves proper consideration.
If a five-year arrangement produces more revenue for the Crown, preserves a viable business and allows employees to remain in work, why should three years necessarily be better? The purpose of tax-debt collection is to recover money, not simply to secure a promise that may never be fulfilled.
Sometimes five years may achieve more than three.
This article is general commentary, not legal or financial advice. Decisions involving family loans, gifts, guarantees or security may require separate legal and financial advice.
*Dave Ananth is a partner at Meridian Partners and a former Inland Revenue solicitor. His practice focuses on student loans, tax disputes and negotiations with Inland Revenue. His background, profile and contact details are here.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.