
Here's our summary of key economic events overnight with news the war in Ukraine continues in something of a stalemate process as the spring thaw bogs down the Russians. But they are bombing indiscriminately. Still, Western investors no longer seem to be preparing for an international meltdown. Equity markets are recovering. Bond yields are back focusing on the US Fed, oil prices are much lower today, and the main economic fallout seems to just be on Russia. Anyway that's what markets seem to be signaling despite the changed economic conditions.
In the US, American mortgage applications rose, and by more than expected, last week. And mortgage interest rates slipped back at the same time. But these lower rates are not expected to continue for long, so borrowers piled in on the opportunity.
The number of job openings in the US in January slipped marginally from a revised record high level in December. Still, the result was above market expectations as worker shortages persist.
The US WASDE March report indicated that the global market for wheat may not be as tough as first thought. Rising volumes from Australia and India are helping offset the Ukraine uncertainties. The same report sees lower US dairy production, so prices are expected to rise on continued demand strength
Today's US Treasury 10year bond auction was well supported, and the 1.84% median yield was little changed from the same event a month ago. Further, the Fed only participated at a very low level this time, a significant pullback.
Japanese machine tool orders slipped in February from January, although to be fair they are still running very much higher than a year ago.
In South Korea, their presidential election remains too close to call, but the throwback opposition candidate does have a narrow lead as the vote count nears the end.
China's inflation rate is staying low, running at only +0.9% in February. This was as expected. Meanwhile China's producer prices rose +8.8% in February from a year ago, slightly higher than expected but lower than January.
China might be an economic loser on the sharp runups in commodity prices. It isn't unique to China of course, but their high dependence on exports made at fixed costs will put their factory sector under a special squeeze.
Ratings agency Fitch says Russia is about to default on its debt obligations. It has downgraded Russian Government bonds to C. (Russia paying its US dollar bond obligations in rubles is default, says Fitch.)
Russia's pre-invasion consumer price inflation rate rose to +9.2% pa in February. That will be looked back on as 'low' in coming months. In February it took about 80 rubles to buy one US dollar. Now it takes 120 rubles, an effective devaluation of a third.
Appreciate this coverage? Support us and go ad-free. Find out how.
(We are not supported by the Public Interest Journalism Fund, nor Google, nor Facebook's similar programs.)
Although capacity is still constrained, air cargo traffic volumes are recovering and back to pre-pandemic levels. They were up +3.2% in January from the same month a year ago with Asia/Pacific international trade by air up +5.5%.
Australian consumer sentiment is falling on a growing set of factors that compound each other, including the pandemic, floods, and war. Housing gets an honourable mention too.
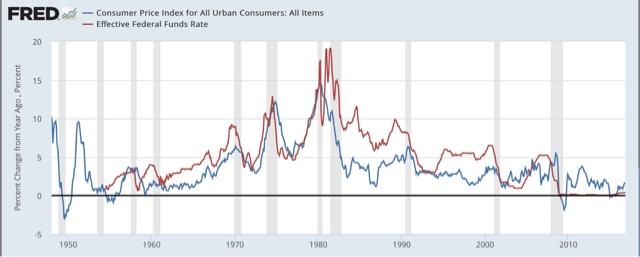
Higher interest rates not only affect consumers, they add to government spending as well, and that effect is magnified when budget deficits are growing. In Australia, their $15 bln interest cost on public debt is expected to grow to $18 bln this year, and to over AU$30 bln as their deficits swell. Fast-rising interest rates off a low base supercharges the interest cost, especially when deficits are large as they are in Australia.
The flooding disaster in NSW and Queensland has prompted market experts to predict home insurance premiums will rise at a much faster pace. +10% rises are on their way, as a start as insurers increase their natural disaster provisioning. From the current flooding event, they are dealing with more than 100,000 claims already, and more are sure to pour in. And New Zealand won't be immune because the same insurers operate here and their climate risk aversion is now front-and-center.
The UST 10yr yield opens today at 1.92% and up another +5 bps from this time yesterday. It is back to pre-invasion levels. The UST 2-10 rate curve starts today a little steeper at +26 bps. Their 1-5 curve is very much steeper at +99 bps and their 30 day-10yr curve is also much steeper at +176 bps. The Australian ten year bond is up +2 bps at 2.34%. The China Govt ten year bond is another +1 bp firmer at 2.87%. And the New Zealand Govt ten year is up +7 bps at 2.89%.
In New York, the S&P500 is in full-on recovery in Wednesday afternoon trade on Wall Street, up +2.6% so far. Overnight European market recoveries were reasonably spectacular; Paris was up +7.1%, London was up +3.3% and Frankfurt was up +7.9%. Yesterday, Tokyo ended -0.3% lower. Hong Kong was -0.7% lower. Shanghai was 1.1% lower. The ASX200 ended its Wednesday session up +1.0%. The NZX50 ended up +0.3%.
The price of gold starts today at US$2001 and down -US$43/oz from this time yesterday.
And oil prices are very sharply lower today and down by -US$6/bbl. In the US they are now just under US$114/bbl. The international price is just under US$118/bbl.
The Kiwi dollar will open today a little firmer at just over 68.5 USc. Against the Australian dollar we are at 93.5 AUc which is slightly lower. Against the euro we -½c lower at 61.8 euro cents. That all means our TWI-5 starts today at just on 73.4 and little net change from this time yesterday.
The bitcoin price is up a lot today, up +11.1% from this time yesterday to US$42,277. US regulators have signaled it will continue with its light-handed overview of the crypto sector. Volatility over the past 24 hours has been extreme at +/- 5.6%.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.