
Here's our summary of key economic events overnight that affect New Zealand with news global equity markets re-found their 'greed' mojo with a risk-on shift in a week where interest rate moves down gained some serious momentum.
Most global equity markets celebrated with strong weekly rises, knowing that inflation seems beaten, especially as energy prices remain in retreat everywhere. Some can smell a new up-cycle. That could be good for commodities.
First up today, Canadian retail sales rose more strongly than expected in July, up +0.9% from a year ago when a +0.6% rise was expected. A key driver was car sales.
And Canadian PPI rose only +0.2% in August from a year ago, a sharp slowing from the +2.8% rise in the prior month. Month-on-month, their PPI fell -0.8% and a much bigger drop than expected. The key driver here is the falling cost of energy.
Japan reported 3.0% CPI inflation in August, up from 2.8% in the prior three months. It is their highest level since October 2023. Japanese inflation now seems well embedded, after decades of deflation.
The Japanese central bank left its 0.25% policy rate unchanged, as expected. They said "Japan's economy is likely to keep growing at a pace above its potential growth rate, with overseas economies continuing to grow moderately and as a virtuous cycle from income to spending gradually intensifies against the background of factors such as accommodative financial conditions." But press conference remarks after the release suggests that the Bank has turned dovish, so expectations for more rate hikes are lower now.
India's economic surge is built on aggressive borrowing. Loan growth is running higher than +13% from the same month a year ago, even if that is lower than the almost 20% rate it was running in the same month in 2023.
China left its loan prime rates unchanged yesterday in its September fixing, as expected. These remain at record lows. (It doesn't wish to be seen following the US Fed, even if a cut is warranted at this time.)
And data released overnight shows their 'youth' (16-24) unemployment rate was 18.8% in August, the highest since they changed the basis of this stat in January. They say their general jobless rate is 5.4%, and that too is its highest in a year.
Consumer sentiment in the EU continues to rise, in spite of their obvious economic struggles. In fact, it is almost back to its long-run average levels, something it hasn't managed since the pandemic period.
German producer prices fell -0.8% in August from a year ago, also largely due to cheaper energy costs.
The UST 10yr yield is now at just on 3.73% and unchanged from this time yesterday. But that is up +7 bps from a week ago. The key 2-10 yield curve is now +12 bps positive. Their 1-5 curve inversion is still inverted by -46 bps. And their 3 mth-10yr curve inversion is now at -103 bps. The Australian 10 year bond yield starts today at 4.00% and unchanged. The China 10 year bond rate is at 2.05%, and also unchanged. The NZ Government 10 year bond rate is now just on 4.20% and down -1 bp from yesterday, where it was two weeks ago, but up +7 bps from a week ago.
Wall Street has settled back today with the S&P500 down -0.1% from yesterday after the Fed decision. That makes it a +1.6% rise for the week. Overnight, European markets were all down -1.5% on the day. For the week, London lost -0.3%, Frankfurt gained +0.5% and Paris gained +0.9%. Tokyo ended its Friday trade up another strong +1.5% to end its week a good +2.3% gain. Shanghai was unchanged yesterday, up +0.5% for the week. Hong Kong closed up +1.4% and up a stellar +5.6% for the week, and helped by rumours Beijing will end limits on developments that were introduced to cool an earlier market surge. Singapore was down -0.2% in Friday trade. The ASX200 ended its Friday up a relatively modest +0.2% for a good +1.4% weekly rise.The NZX50 fell -1.5% on Friday and compounding its drop to -2.9% for the week.
The Fear & Greed Index ends the week in the 'greed' range, from last week's 'neutral' range. Overall market have recovered their risk appetite.
The price of gold will start today at US$2620/oz and up +US$31 from yesterday's high to near a new all-time high again. That is a +1.5% rise from a week ago when it was US$2582/oz.
Oil prices are down -US$1 at US$71/bbl in the US while the international Brent price is still just under US$74.50/bbl. A week ago these prices were US$69/bbl and US$72/bbl respectively, so a +US$2 rise since then. And they are down -17.7% in a year. Demand is suppressed by alternatives while supply is rising too fast for the comfort of OPEC.
The Kiwi dollar starts today at 62.4 USc and down -10 bps from yesterday but up +80 bps from a week ago. Against the Aussie we are unchanged at 91.6 AUc. Against the euro we are down -10 bps at 55.9 euro cents. That all means our TWI-5 starts today at 69.9, unchanged from yesterday but up +60 bps from a week ago.
The bitcoin price starts today at US$62,499 and down -2.1% from this time yesterday. A week ago it was at US$59,737, so a +4.6% gain since then. Volatility over the past 24 hours has been modest at just on +/- 1.4%.
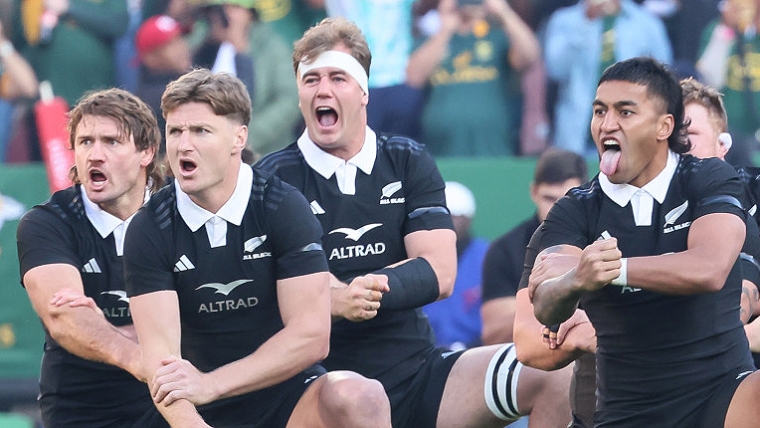
Go the ABs !
Daily exchange rates
Select chart tabs

The easiest place to stay up with event risk is by following our Economic Calendar here ».

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.