
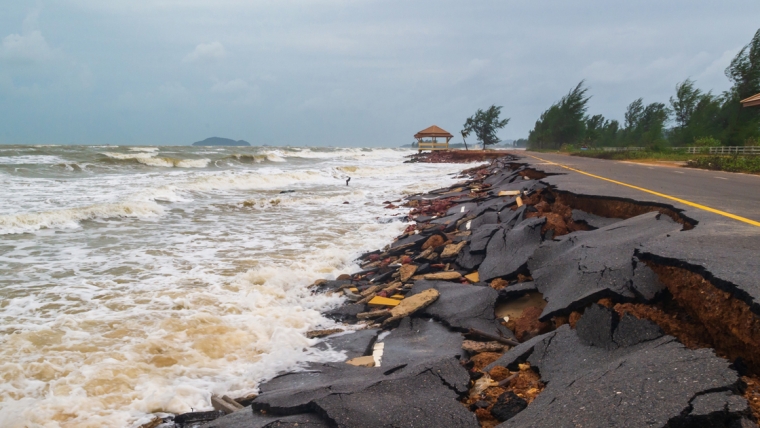
Insurer Tower says it is expanding its risk-based pricing model for customers' insurance premiums to include landslide and coastal hazards, with advanced selection for landslide risks "already in place" across New Zealand.
Tower made the announcement alongside its interim financial results. Tower reported an underlying loss, including large events, of $3.3 million versus profit of $5.4 million in March 2022 half year, and a reported loss after tax of $5.1 million versus a $2.9 million profit.
The storm in Auckland on May 9, the latest extreme weather event to hit the upper North Island over recent months, is expected to be a large insurance event costing between $4 million and $6 million, Tower says. It has between $10 million and $12 million in large events allowance remaining in the second-half, and won't be paying an interim dividend.
“Now more than ever it is critical that New Zealand maintains a strong insurance industry for the future. Tower remains focused on careful risk selection and risk-based pricing, which is a fairer way to price insurance as customers only pay for the risks that apply to their property," CEO Blair Turnbull says.
"In 2023 Tower will expand its risk-based pricing model to include landslide and coastal hazards. Advanced selection for landslide risks is already in place across New Zealand."
Tower already has flood and earthquake risk-based pricing in place.
Tower says it has successfully completed "the reinstatement of its reinsurance arrangements" providing important protection from the volatility of large events.
"Tower has cover for any potential third and fourth catastrophe event up to $889 million in the financial year," Turnbull says.
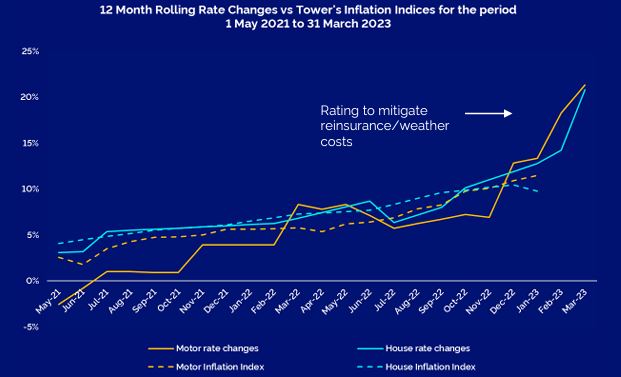
"Tower’s full year underlying net profit after tax guidance remains between $8 million and $13 million, assuming full utilisation of the $50 million large events allowance. Gross Written Premium guidance is between 15% and 20% reflecting organic growth and a strong rating response to address inflation, rising reinsurance premiums and higher motor claims costs. Tower will not pay an interim dividend. A decision on a full year dividend will be made when Tower’s full year results are finalised."
He says about 30% of claims for the Auckland and Upper North Island weather event and Cyclone Gabrielle, and 5% of claims for Cyclones Judy and Kevin in Vanuatu have been completed. Tower is "working efficiently" to settle the rest, with these events "predominantly" covered by reinsurance.
"The cost to Tower for each of the New Zealand catastrophe events is limited to an $11.9 million excess, while the estimated cost of the Vanuatu cyclones is $10 million net of reinsurance recoveries," Turnbull says.
“Tower continues to grow both premium and customer numbers while reducing our expense ratio. We expect to deliver a full year profit along with sustainable long-term growth in revenue and earnings.”
“Investments in technology, operational efficiencies and robust reinsurance continue to underpin Tower’s resilience and ability to address external challenges. We are proactively managing climate related weather impacts through risk-based pricing and product innovations, keeping pace with inflation via targeted rating and underwriting actions and addressing increasing vehicle theft with rating and excess changes," says Turnbull.
Summary of key HY23 results:
• Gross written premium (GWP) $245m, up 15% on HY22
• Customer growth up 5% to 320,000
• Business as usual (BAU) claims ratio 51.6% vs 48.6% in HY22
• Management expense ratio (MER) improved to 35.1% vs 35.8% in HY22
• Underlying net profit after tax (NPAT) excluding large event costs $23.6m vs $18.2m in HY22
• Large event costs $33.9m vs $17.9m in HY22
• Combined operating ratio including large events (COR) 105.3% vs 94.8% in HY22
• Underlying loss including large events $3.3m vs $5.4m profit in HY22
• Reported loss $5.1m vs $3m profit in HY22, including strengthening of the residual Canterbury earthquake and multi-policy discount remediation provisions, partially offset by the sale of Tower’s Papua New Guinea subsidiary and its building in Suva.
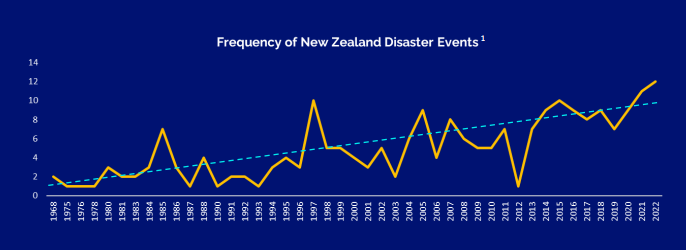
1) Chart above sourced from the Insurance Council of New Zealand.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.