Here are my Top 10 links from around the Internet at 10 past 11 am, brought to you in association with New Zealand Mint for your reading pleasure.
I welcome your additions and comments below, or please send suggestions for Tuesday's Top 10 at 10 via email to bernard.hickey@interest.co.nz.
I'll pop any surplus suggestions I get into the comment stream under the Top 10.

1. 'I will not be moved' - Despite the talk of a Pensions Working Group on the weekend, Prime Minister John Key has reasserted his opposition to changing either the NZ Superannuation age (65) or its amount (66% of the average wage).
That's one way to shut down the debate.
A pity.
He has however left the door open for Compulsory KiwiSaver.
I'm not sure how you could have both a universal pension on the current terms and a Compulsory KiwiSaver, but no doubt this will come out in the debate.
One thing that should be talked about is what happens to all this extra saving we might do into pension funds. At the moment most of it is being funneled offshore.
Was that supposed to be the plan? Currently 69% of the NZ Super Fund's (Cullen Fund) NZ$15.6 billion of assets is invested offshore once cash here is included. It's 81% without cash.
As at the end of March 2009 44% of the NZ$3 billion invested in KiwiSaver funds had been sent offshore.
If we have a savings problem in New Zealand, is sending more than three quarters of this news savings overseas the right approach?
Mr Key said he was happy with how New Zealand's superannuation scheme worked and it was, essentially, compulsory. "That's a very elegant system, it works well, and we're not going to change it -- either age of entitlement or the amount that you get," he told TV One's Breakfast show.
However, 90 percent of New Zealand's debt was owned offshore, he said. "Lifting our national savings rate would be really good, the question is how you do that." Individuals lived longer after retirement now and were more active so needed more money to fund their retirement, Mr Key said.
Mr Key said the Government was aware of the problems and was looking into solutions but it was too early to say whether it would adopt compulsory KiwiSaver.

2. 'There's no mattress big enough' - William Pesek makes the point at Bloomberg that China's widening gap between the rich and the poor is a political problem in the long run because eventually it's hard for the super rich to hide their wealth from the super poor.
And we wonder why so many Chinese seem so keen to squirrel their cash out of China and into hard assets in New Zealand such as land or houses?
Investors haven’t gotten rich betting against China. Yet China’s fragilities need tending to, and now, if its development is to be sustainable. The condition of China’s state-owned banks is a concern for investors, and rightfully so. China plans to stress-test banks to assess how a big drop in property prices would affect the financial system.
Officials should make sure the process is more thorough and transparent than in the U.S., Europe or Japan. Social unrest is a bigger risk. Much of China’s hidden income may be “illegal or quasi-illegal,” according to the Credit Suisse study, published by the China Reform Foundation. It should be no surprise that a nation growing 10 percent has a healthy gray economy running in parallel.
That’s what happens when an all-powerful, top-down government mixes with vast supplies of capital. Crony capital thrives, be it kickbacks from construction projects, gifts to officials at weddings, payoffs from state monopolies such as the tobacco industry or spreading profits from land transfers.

3. Australia's plastic cash scandal - The Reserve Bank of Australia just can't seem to shrug off its money printing bribery scandal. Now the Sydney Morning Herald is reporting that Securency, the RBA's money printer (and ours), used an Indian middle man that was also involved in the Iraqi oil-for-food scandal that was so damaging for the Australian Wheat Board.
The agent engaged by the Reserve's banknote firm Securency - which is the subject of Australia's biggest foreign bribery investigation - is related to a senior Indian politician, Natwar Singh, and has been raided by Indian police in connection with suspect arms deals.
Securency hired the businessman Aditya Khanna and his Delhi firm, DSSI Group, to help get its plastic banknotes circulating in India, one of the world's biggest cash economies.
4. Can we trust the CEOs and their bankers? - We're about to have a debate about whether New Zealand should adopt an Australian-style compulsory KiwiSaver scheme.
But it's worth looking closely at who has actually benefited from the Australian scheme and the A$1 trillion of savings now sitting there. Michael Evans at BusinessDay points to a report showing that CEOs and their investment bankers engineered a massive transfer of wealth during the A$100 billion of capital injections in 2008/09 through doing share placements rather than rights issues. Mates picked mates.
A review of the A$100 billion in capital injections made in 2008-09 questioned the fairness and transparency of the processes, finding existing shareholders suffered an extraordinary transfer of wealth to other investors, hand-picked by company management and their investment bank advisers.
The corporate governance advisory firm ISS Governance Services calculated that A$45 billion of the A$98.9 billion in funds raised by Australian companies as they sought to repair their debt-laden balance sheets during the global financial crisis were chosen by the company or their advisers in a process known as a placement.
Existing shareholders who are unable to take part in a placement have their stake watered down. In contrast, capital-raisings, where all investors were given the opportunity to maintain their ownership interest in the company through rights issues, accounted for A$46.2 billion.

5. Affordable housing and employment - It's intuitive that expensive housing in an area would suppress employment growth in that area because people can't afford to live and work there.
Could it be the same for a country? Until now the research hasn't been there to say yea or nay. Now Ritashree Chakrabarti and Junfu Zhang from the New England Public Policy centre have done some research on how unaffordable housing affected employment growth in parts of the United States. They say it does.
There is a general belief that unaffordable housing could drive businesses away and thus impede job growth.
We empirically measure this effect using data on California municipalities and U.S. metropolitan areas and counties. It is argued that for various reasons a simple correlation between unaffordable housing and employment growth should not be interpreted as causal.
We therefore develop some empirical strategies and employ statistical techniques to estimate the causal effect of unaffordable housing on employment growth. Our results provide consistent evidence that indeed unaffordable housing slows growth in local employment.

6. How big is that bubble in China? - One of the most closely watched hot spots in the global economy right now is the Chinese housing market. Here is an academic paper from Jing Wu, Joseph Gyourko and Yongheng Deng at the National Bureau of Economic Research which reckons prices in Beijing could fall 40%.
High and rising prices in Chinese housing markets have attracted global attention, as well as the interest of the Chinese government and its regulators. Housing markets look very risky based on the stylized facts we document. Price-to-rent ratios in Beijing and seven other large markets across the country have increased from 30% to 70% since the beginning of 2007. Current price-to-rent ratios imply very low user costs of no more than 2%-3% of house value. Very high expected capital gains appear necessary to justify such low user costs of owning.
Our calculations suggest that even modest declines in expected appreciation would lead to large price declines of over 40% in markets such as Beijing, absent offsetting rent increases or other countervailing factors. Price-to-income ratios also are at their highest levels ever in Beijing and select other markets. Much of the increase in prices is occurring in land values.
Using data from the local land auction market in Beijing, we are able to produce a constant quality land price index for that city. Real, constant quality land values have increased by nearly 800% since the first quarter of 2003, with half that rise occurring over the past two years. State-owned enterprises controlled by the central government have played an important role in this increase, as our analysis shows they paid 27% more than other bidders for an otherwise equivalent land parcel.

 7. Speaking of cats...(below) - America's economic recovery has been of the rubbery feline variety, the Economist's Ryan Avent points out with this handy chart (left), particularly compared to previous recoveries.
He has some startling stats on how employment has previously bounced back very strongly...but not this time.
From 1934 to 1936, the American economy grew by 10.9%, 8.9%, and 13.0% per year, respectively. From 1983 to 1985, annual growth came in at 4.5%, 7.2%, and 4.1%. For now, it seems the American economy will struggle to grow by 3% in the first full calendar year after the recession.
This is uncharted territory for the American economy.
We have already observed the ways that the weak and jobless recovery has strained budgets and labour market institutions.
It will place transformative pressure on other political and economic institutions as well before the unemployment rate falls back to "normal" levels
8. Roubini speaks - Nouriel Roubini spoke to Andrew Patterson at Radio Live last week about the rising risk of a double dip recession in the US economy. He sees more money printing from the US Federal Reserve, but doesn't see it making much difference.
Interest rates are already near record lows and borrowers aren't credit worthy enough. The only other option is government stimulus paid for with bond issues, but America's public debt is already very high and it's politically difficult to push it much higher than the already ruinous track.
Roubini is well worth listening to by those a tad sceptical about the 'new normal'.
"You cannot force a horse to drink," Roubini says.
"We cannot go back to high economic growth any time soon until this massive multi-year deleveraging has taken place."
He sees anaemic growth for two or three years with a lower risk of a slide into a Japanese-style depression.

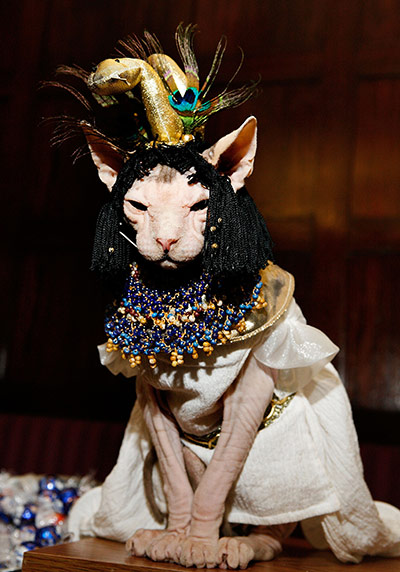
9. Totally irrelevant pictures - This is how some of the richest people in America live. These cats below were in a fashion show to celebrate another cat's birthday in New York. Poor little buggers.
Halebop is a cat from New York. They have way too much money there.
This is just too good not to put in.
Oh and this is a shocker too
10. Totally irrelevant video - This made me smile. Clever video wordplay. HT EricaLloyd va Twitter
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.