By Bernard Hickey
Just over two years ago I spoke to a group of Waikato property investors at an evening meeting about economics and investing.
I mentioned in passing that some other people chose to invest in shares in growth companies rather than the two bedroom brick and tile flats they were more familiar with.
I mentioned a then little-known business software company called Xero that had listed on the NZX in June 2007 after an initial public offering at NZ$1 a share raised NZ$15 million.
The audience's response was contemptuous. There were sniggers. There were chortles.
"It's never made a profit and never paid a dividend," said one. "The stock market is a rip off machine," said another.
There was little appetite that evening for anything other than highly leveraged investment in property where the interest costs could be offset against income and the capital gains were tax free.
It was actually hard to argue against their logic that night.
Our tax system and banking systems work together to make leveraged property investment a much more rational decision for individuals than investing in term deposit accounts and stocks and bonds.
It's the reason why most wealthy people will tell you privately that they made most of their money via the tax-free gains from leveraged property and not from their business interests.
It's why Parliament's register of pecuniary interests last year showed our 121 MPs owned 292 properties and 60% had interests in family trusts that owned many more properties.
Yet, just quietly, this structural bias in favour of property investment and against long term investment in other savings vehicles is even beginning to sour around the corridors of the Beehive and in the ministries up the Terrace.
The housing affordability crisis in Auckland, a fresh burst of leveraged property investment and the resulting limits by the Reserve Bank on low deposit borrowing have focused hearts and minds around government.
Politicians can feel the anger building, particularly among those of a younger and aspirational view that values home ownership.
The young and the poor are now pounding against the gate, demanding to let in to share the spoils.
The opinion polls in Auckland are telling the Government to change track.
The mood is shifting on the issue of tax incentives for saving in vehicles such as KiwiSaver funds, which are growing fast and pumping money into New Zealand's broadening and rising stock and bond markets, but which remain deeply disadvantageous for savers relative to rental properties.
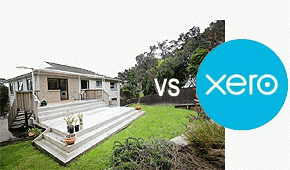
That's where Xero comes in. Back in July 2011 when I talked about Xero with the brick and tile owners it had been on the stock market for four years and its shares were trading at just over NZ$2.
This week Xero's shares nudged the NZ$19 mark as it announced a near doubling of revenue and customers.
It has still to report a profit, but the early grumbles about profit and dividends have faded away amid the celebrations over the rise in its market value to more than NZ$2 billion and hopes it can become a global small business accounting giant in the cloud.
Most importantly, Xero's staff numbers rose from 41 in 2007 to 584 and it has a real shot at massive services export revenues.
This is the sort of investment New Zealanders need and our tax system should encourage it, not discourage it.
I may not ever be able to convince those property investors there is another way, but I hope they will think twice before dismissing the next Xero with a snigger.
-------------------------------------------------------------------------------------------------
This piece was first published in the Herald on Sunday. It is used here with permission.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.