
By Amanda Morrall (email)
1) Worship at your own altar
As most of you know by now, I'm a dedicated yogi and Buddhist. How I ended up in finance seems a somewhat random spin of the wheel or else destiny. In any case, as one of "those types" I have enjoyed my fair share of retreats, some good, some bad and some just weird. One of them was on a mountaintop in the South Island. Indulge me for a moment but there's a personal finance thread here.
On this particular retreat, I had an opportunity for a one on one chat with the resident guru. Overall, this individual struck me as being more enlightened than the average bear. You can tell this about a person usually. They have an inner glow about them that is missing from the general population. Regardless of that radiance, my spidey senses were tingling. For one, I had to pay for this private chat (no, no clothing was removed!) on top of the retreat fees. I justified this at the time because even yogis need to monetise to survive. The more jarring part of the exchange was the nature of the advice. It related to a particularly difficult matter in my life. The guru, in my opinion, gave me bum advice. I can't blame anyone but myself but reflecting back now on the experience this well-intended bit of advice did more harm than good.
When I read this story on the rising popularity of "personal finance guru" Ramit Sethi (thanks BH) my spidey sense starting tingling again. I highly recommended you reading the article as much for Sethi's financial prowess as for his acerbic personality. Obviously I don't know this guy but the impression I had (from the reporter's experience) was that this guru however money smart is somewhat of a jerk. (Yes, I acknowledge that by saying this puts me in his boat too). As tends to be the case with these kind of self-obsessed, single minded individuals who have cottoned onto something that resonates and indeed works for the masses, Sethi's become rich out of it.
In a nutshell, the magic of Sethi's espoused financial wisdom and method is creating systems to manage your money. Basically he maintains the majority are hopeless financial dimwits who need saving from themselves. This apportioning system whereby you auto-pay into accounts to control overrun, is hardly a new concept, but it would appear the guru has been able to peddle the message loudly and clearly to the public.
His appeal ironically seems partly to do with the fact that he's a fellow who has no time for financial fools nor any problem calling them that.
For the pleasure of his financial arse-kickings and abuse, Sethi's clients pay a not insignificant sum of money. If his message and method sticks, one might arguably say the US$1k is a drop in the bucket and therefore worth every penny. But as your financial yogi, I'm here to tell you, you don't have to shell out more money to get yourself sorted. Everything you need to know lies both within and without. You'll find it at the library, or on the Internet or among people who visit and comment on blogs such as ours. Sure, I agree that financial handcuffs are a brilliant idea, and perhaps a necessity for some but don't dig a deeper hole for yourself by paying when you don't have to.
Be your own guru and prosper.
2) Is being financially average okay?
I don't like averages. Statistically speaking, I've found averages to be quite meaningless because of the yawning gap between the upper and lower that distorts the middle. Also to me being average implies satisfaction with the status quo. The average Joe has more potential than they will ever know. Still, I acknowledge that average is a reality many have to contend with or else content themselves with.
This article, a write up from the latest BBC Money files, is interesting in this regard as it profiles a few families who live on £40,000 a year (the average income in the U.K.).
3) Consumer manipulation
I was never a big consumer but in the past few years I've become the anti-consumer. I enjoy some luxuries of course (Parisian mascara, quality yoga gear, nice coffee) but overall my buying urges have been squelched. I'm not seduced by sales, I don't need the latest, greatest and I don't indulge in retail therapy to compensate for a bad or sad mood.
Here's a great list of retail ploys to beware of via moneycrush.com
4) Profiting from your passion
I know a number of people who have established sidelines to supplement their income or for the sake of their enjoyment. What's the key to making these sidelines profitable? It's multi-factorial.
This blog profiles how a few individuals have made it work. I'm very interested to hear yours as well. Please email me directly if you have a method or story you don't mind sharing.
5) The gift of gratitude
There is a mistaken belief that yoga is about great feats of flexibility and strength. While that's true of asanas (the postures) the physical practise of yoga is but one of eight "limbs" of yoga. The real practise of yoga is a journey of understanding self with a view to conducting oneself in a manner that gives to the world more than it takes. I'll end my sermon here save to say that gratitude is a central element of the process.
Gratitude, I would argue, has just as an important role to play in personal finance. That's because when you take stock of what you have in your life, it has the effect of extinguishing so many of the cravings that lead to reckless financial behaviour and outcomes.
6) Balasana
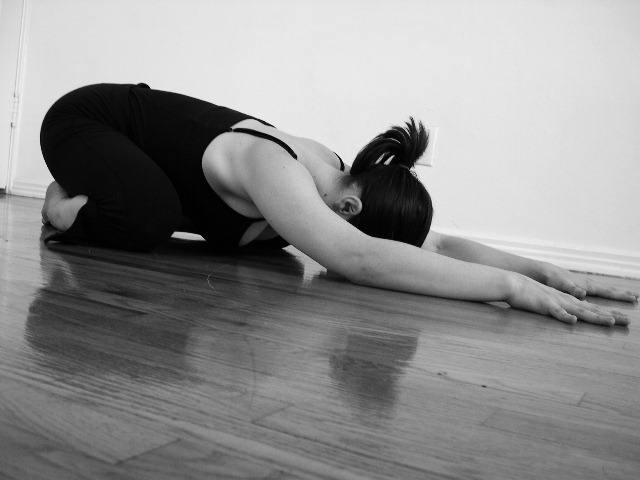
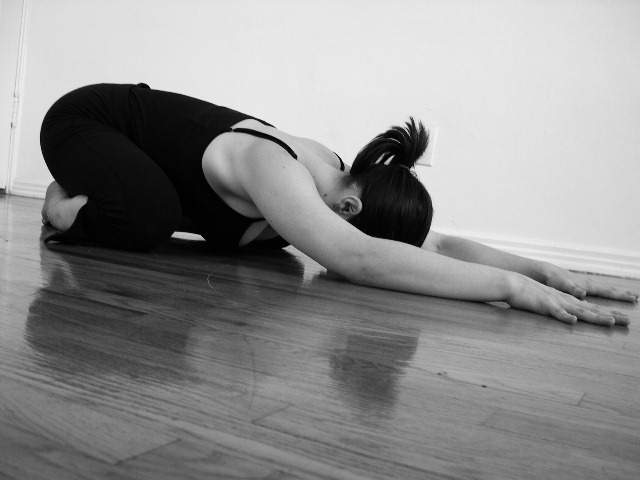
It's fitting therefore to throw in another simple pose to help ease the strain and tension of Christmas. Child's pose, pictured below, is a fabulous chill out position to calm the mind, and stretch the thighs, torso, ankles, and release tension in the neck. The version pictured below is an "extended child's pose" but the arms can rest at your side as well.
If you're wondering at the incongruous coupling of yoga with money, it's because of an earlier promise to match three financial detox strategies with yoga poses that achieve the same effect on your body and mind. Namaste.
For other Take Fives by Amanda click here.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.