
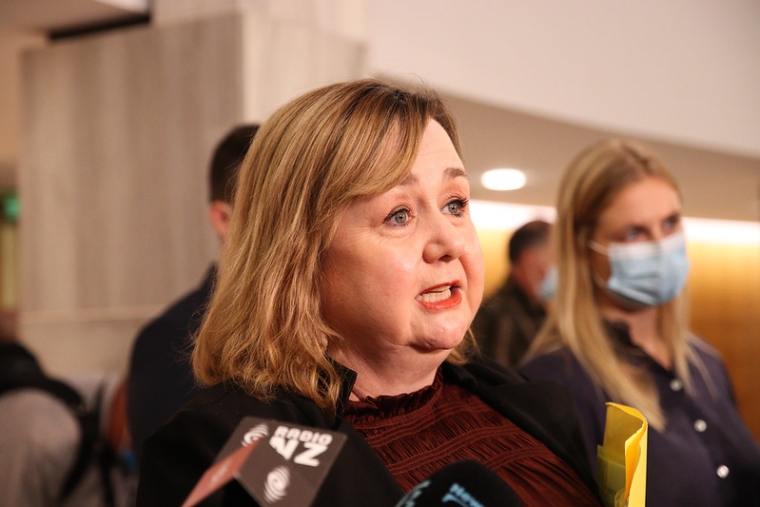
Housing Minister Megan Woods has announced blocks of at least 20 new and existing build-to-rent flats will be exempt from interest deductibility tax changes in perpetuity if they offer 10-year tenancies.
The Government has just changed interest deductibility rules so landlords cannot claim interest for tax purposes on existing rental properties. The interest deductibility changes don't apply for 20 years for individual landlords that build new homes.
“We’re providing an exemption from the interest limitation rules to certain types of new and existing build-to-rent developments in perpetuity,” Housing Megan Woods said.
“To qualify, developments need to offer tenants leases of at least 10 years. Tenants can ask for shorter agreements if they wish and the development will still qualify for the exemption. Tenants will be able to break their tenancy agreements at any time, with a 56-day notice period," she said.
“We believe security of tenure is critical for people who are renting. This requirement will enable people to settle and personalise their homes, reduce how often they must find a new place to live and all those associated moving costs, especially as people face cost of living challenges, and help them to build and maintain connection to their community."
Woods said the change would encourage an increase in supply of stable new rentals.
"We recognise the big role the build-to-rent sector can play in filling a gap in the general rental market by increasing the supply, density, and diversity of housing. Aotearoa New Zealand needs to build more houses where they are needed and at prices that low- to moderate-income households can afford," Woods said.
"Build-to-rent can help to continue the current momentum of new supply and improve the quality of rental housing with new warm, dry, secure homes,” she said.
Property Council welcomes move
Property Council CEO Leonie Freeman said the announcement was one of the best levers to unlock the potential of build to rent.
“We support the government’s desire to enable Build to Rent in order to provide warm, dry rental homes that offer Kiwis long-term security of tenure,” Freeman said.
The Government will introduce the following build-to-rent asset class definition:
- Tenants must be offered a fixed-term tenancy of at least 10 years with the ability to give 56 days’ notice of termination, but they may agree to or request other tenancy offers. Note that in order to qualify as build-to-rent, a tenant does not have to accept a 10-year tenancy offer. A build-to-rent development will satisfy this requirement as long as a 10-year tenancy term is offered.
- At least 20 dwellings in one or more buildings that comprise a single development, on either a single parcel of land or multiple contiguous parcels.
- The dwellings and any common land or facilities for those dwellings must have a single owner, but dwellings can be held in one or more titles.
- The building that a build-to-rent dwelling is in can include other dwellings or commercial premises that do not form part of the build-to-rent development (for example, an apartment block that has shops on the ground floor)
- For existing build-to-rent assets, interest will not be phased out as a taxable expense. Taxpayers who hold existing build-to-rent assets will not be subject to the interest limitation rules for the short period of 1 October 2021 to 31 March 2022, and will continue to be exempt in perpetuity. ·
The legislation for the proposal will be included in the next omnibus tax bill, which is expected to be introduced by the end of August.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.