
sign up log in
Want to go ad-free? Find out how, here.

High numbers of homes for sale and lacklustre sales volumes keep buyers in the driving seat through winter

Property / analysis
High numbers of homes for sale and lacklustre sales volumes keep buyers in the driving seat through winter
agent
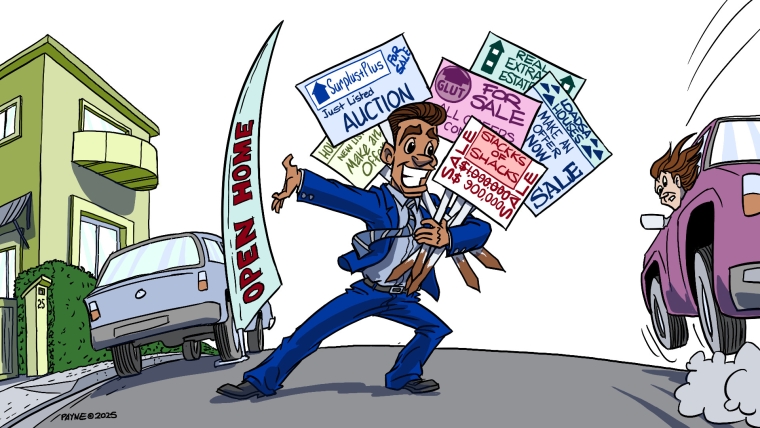
Image: Ross Payne.


The high level of unsold housing stock for sale is likely to continue weighing on the market as its heads into spring.

Stock for sale measures in July were all well up on July last year, while reported sales were down, meaning buyers continued to have the upper hand in mid-winter.

Property website Realestate.co.nz reported 33,252 residential properties for sale on its site at the end of July, not only up 9.3% compared to July last year, but also the most properties the website has had available for sale at the end of July since 2014. That puts stock levels at a 12-year high.

The overhang of unsold properties, the number of properties remaining unsold after being on the market for more than a month, was looking even worse.

Interest.co.nz estimates there was an overhang of about 25,500 residential properties at the end of July, up 12.6% compared to July last year, putting the overhang at its highest level since 2014.

However, sales were headed in the opposite direction.

The Real Estate Institute of New Zealand provisionally reported 6090 residential sales in July, down 3.6% compared to July last year. 

While high stock levels and lacklustre sales volumes point to a market that's likely to remain subdued, a couple of figures suggest at least it may not be getting any worse.

The first is that new listings coming to market were almost flat compared to a year ago.

Realestate.co.nz received 7698 new residential listings in July, just 39 fewer properties (-0.5%) compared to July last year.

On top of that, the number of properties dropping out of the market was down significantly.

Dropouts are properties that have either been taken off the market completely, or are still technically for sale but are no longer being actively marketed.

Interest.co.nz estimates there were around 3100 residential dropouts in July this year, down 7.6% compared to July last year.

A flat number of new listings and fewer dropouts supports anecdotal evidence that vendors are starting to become more realistic in their price expectations, which, if the trend continues, could reduce the backlog of properties for sale over time.

However, all of the above figures relate to the market in mid-winter.

Whether the market continues to strongly favour buyers during the busier spring and summer months will likely depend on how many properties come to market and how realistic their vendors are in regards to price.

The comment stream on this article is now closed.

We welcome your comments below. If you are not already registered, please register to comment

Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.

22 Comments

This huge number of monthly dropouts and gigantic number of listings, will eventually move.....

As the NZ property market drops down,  another -20%, over the next 2 to 3 years.

This crash will be the biggest in NZ and perhaps world history, for last 100 years.

NZ Winning gold again!

Up
6

"another -20%, over the next 2 to 3 years" - I actually agree that is possible.

My prediction has been flat prices for a while now (loss in real terms). But with interest rates heading up again, its like a kick in the guts to a flat-at-best market. 

Up
6

4% inflation at the moment, over 3 years is 12.5%. So it would only take a pretty minor drop in nominal values to get close to a 20% fall in real terms over 3 years. Easily possible. Consents have really started ticking up, and this low bottomed out higher than the early 2000's peak in building activity. New supply will continue to put downward pressure on prices. The market has structurally changed.

Kudos to those that paid down the minimums on their mortgage and put the rest into index funds. Or even better, stayed renting and did the same!

Up
6

That's one of many problems. Increasing interest rates, a dud economy, low net immigration, potential tax changes, more homes permitted by councils, boomers cashing up, ...

Up
3

Speculords be happy. A tax free loss... is still tax free. Jokes.


Up
5

Nothing kills property values like cutting mass immigration. 

Up
5

Nothing kills property values like people realising they don't need to buy a house, or not now given the current trajectory. More doing the maths and realising they are saving by renting and investing, then can buy back in later with a greater deposit that they didn't have to work for a percentage of due to net index gains, thus compounding their savings long term across the lifespan of the lower mortgage.

Up
5

I haven't seen any compelling paper or article that quantifies the additional housing demand of migration. Compared to domestic demand.

For instance; the aging population with more and more empty nesters rolling around in 4 bed houses, people having fewer kids, both adding to smaller average household sizes. Rising productivity and incomes of workers, although slower than elsewhere in the OECD, contributes significantly people want nicer newer bigger houses. Work from home meaning every office worker wants an additional bedroom for a dedicated home office.

The classic data point is the the inner suburbs of Auckland (Ponsonby, Herne bay) have fallen in population over recent census periods. Hardly some low cost area.

I would guess that immigration makes up a small amount of housing demand. Don't have the tools to study it unfortunately.

Up
5

In this housing market, for the years ahead, the best time to SELL, IS YESTERDAY.

NEXT BEST, IS TODAY!


All mortgage rates are about to bolt much higher!  The cost of debt is going to be painfully high for years.


Take note, the two hasbeen high priests and accomplices of pushing the NZ propery Ponzi to its heights.....and now crashing: Ashley C and Tony Zanders!

Up
6

The US 30y and 10y are screaming problems ahead

30y bottomed at 1.197% during covid now its 5.31% I think you have to go back to 2004 to find it this high.

US Share market seems to be ignoring the rapid rise, historically bonds win, normally by equities getting slaughtered.

Up
6

Yes. 

High debt prices, is the giant slaughtermans blade,  set to slash at all assets linked to Ddddebt.

Up
6

Shit could get serious very quickly here not n nz housing in us equities private credit and euro dollar financing 

nz housing could be the least of our worries 

Up
4

The housing market is poised to bounce back strongly once the election has been and gone. Many investors are waiting on the sidelines waiting to see what happens on November 7. However, whether it be a left or right govt, property will still be a great investment. Leverage and inflating away your debt are two of the many benefits of investing in property.

Up
0

Do you ever consider the many thousands of NZer's that hugely overpriced housing doesn't benefit, in fact quite the opposite? 

Up
7

Hmmm.... tell that to those suckered into buying in 2021-22. Crashflow is "not" always king. Negative leverage anyone...?

Up
4

The property investment seminars you've listened to likely didn't differentiate between stagflation and general inflation. You can't pay your loan off easier or put the rent up because the price of cheese went up. https://www.rnz.co.nz/news/personal-finance/700162/nz-wage-growth-worst…

Up
5

The force is strong in that one 

Eventually reality will beat it out of him 

Up
5

Ponzinomics is full of the devout followers of:  "its a cycle"   "always goes up"   "not making any more"  "Doubles every 10yrs".


Now the Ponzi is kaput and broken beyond repair, they are wondering the wilderness - naked, afraid and muttering the ole Ponzi hymns like a homeless santa.

Up
3

if people knew things we would not have the concept of stop loss and money management

Up
0

Left governments are usually good for house price inflation (also = rent increases). They can't help themselves "being kinder" by  subsidising it with other people's money (cf income support / accommodation allowance, WFF...)

Up
1

Are you suggesting the Proparati circle are all lining up to vote left, cos that would be a first...?

Up
2

No, I'm suggesting that some people should "be careful what you wish for "

Up
2