sign up log in
Want to go ad-free? Find out how, here.

Cotality says elevated stock levels and rising mortgage rates are making buyers cautious

Property / news
Cotality says elevated stock levels and rising mortgage rates are making buyers cautious
Cameron Tidy/Unsplash.

Residential property values declined for the fifth consecutive month in August, according to the latest Cotality Home Value Index.

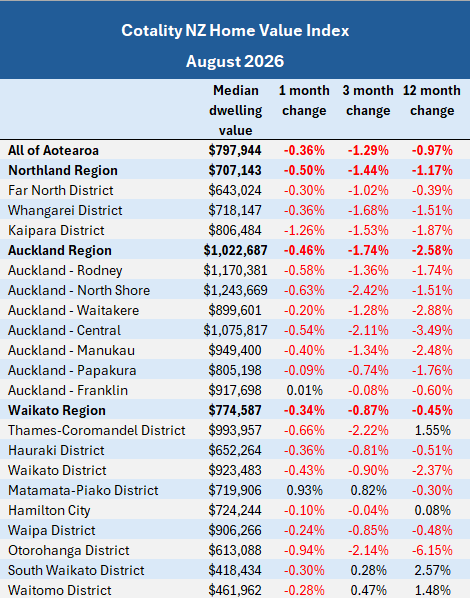
The national median dwelling value was $797,944 in August, down 0.36% for the month, down 1.29% over the last three months and 0.97% lower over the last 12 months.

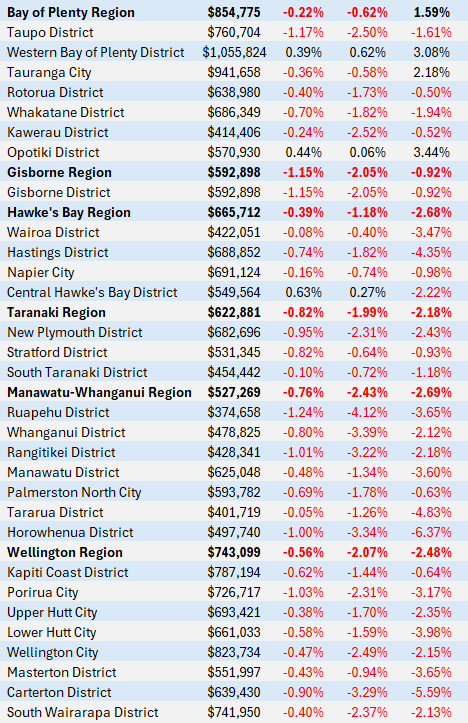
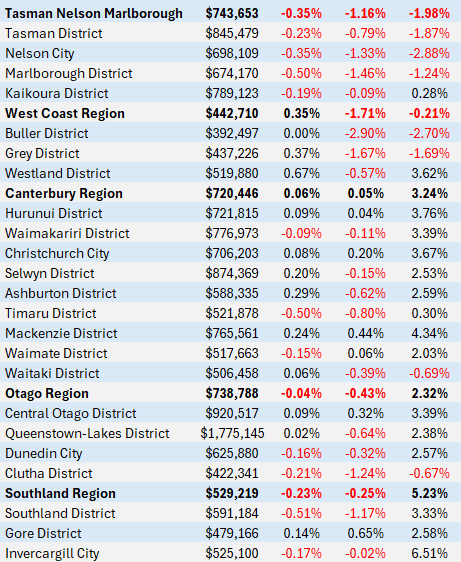
The Index figures show a sea of red (see the tables below) with values declining in most parts of the country over the last year.

The biggest annual declines in value were mostly in smaller provincial centres, led by Horowhenua -6.37%, followed by Otarohanga -6.15%, Carterton -5.59%, Tararua -4.83% and Hastings -4.35%.

In the main urban districts results were mixed, with annual losses in Auckland -2.58%, Waikato -0.45% and Wellington -2.48%, while value gains were recorded in Bay of Plenty 1.59%, Canterbury 3.24% and Otago 2.32%.

Cotality Chief Property Economist Kelvin Davidson said the latest results reflect a housing market characterised by caution rather than distress.

"Economic uncertainty, rising mortgage rates and a high level of properties available for sale are giving buyers little reason to rush," Davidson said.

"At the same time, sellers generally aren't under significant pressure," he said.

"Labour market conditions have softened, but widespread job losses haven't emerged, allowing many vendors to remain patient and hold relatively firm on pricing."

"The result is a market where sales activity has gradually slowed through 2026 and property values have continued to drift lower."

"Most of the heavy price correction occurred in 2022 and 2023, but conditions have remained subdued since then," Davidson said.

The comment stream on this article is now closed.


We welcome your comments below. If you are not already registered, please register to comment

Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.

51 Comments

Cmon Kelvin D-Prop-Apologist. Your words do not match the reality, of this massive NZ property crash, biggest in 50 years. 

Soon to be, the biggest, since the wirely old fox, James Cook, chucked up a tarp on a lonely NZ beach.

Your always talking of "easy on dgms, but but but green shoots, not really a crash, vendors are holding the line" over the years, has your credibilty in total tatters, wrecked and torn, like a sad and soggy discarded edition of granny Herald.


This is his latest beauty allowing "many vendors to remain patient and hold relatively firm on pricing."

Again, This Wont Age Well.


This market is totally borqed and picking up steam, as she slides down the greased up karzi.....

This sucka is going down.


On the bright side, FHBs will be buying by 2030, with a just 20 year mortgage, on 4xDTI and not a lifetime of Bankster indentured slavery.

Cmon Kelvy, tell the truth on this market and ditch the paid market pumper narratives. You should be better than this. When did telling the truth, become so rare?

At least the Interest team, bring the unvarnished truth to the people.

Up
9

I asked Claude how the median median price has changed over the last two decades. Here's what it told me;

(2005) $300k → (2015) $460k → (2025) $790k. 

Roughly a 2.6x increase. 

I can't think of a more perfect illustration of what a good long term investment property is. 

Up
3

Well done H:

Your extra fine, Meguires polish is just the best.  You got a beauty shine, on the now 5 year, NZ housing market Crash -Turd:)

The Truth Be.  The NZ housing market, has become the investment equivalent of:  "The Dog That Don't Hunt"  .....any longer.

FRED data dont lie.  The next downleg is happening, NOW!
Real Residential Property Prices for New Zealand (QNZR628BIS) | FRED | St. Louis Fed

Up
8

Hamish posted numbers based on facts, 

You replied..."polish, shine, turd..." basically emotional blah blah.

Look, there is no doubt that NZ house prices have gone down after the crazy rises up to 2022, and I personally think they will keep going down in the near future.

Still, Hamish has a point, not just a point, he actually has hard facts that can't be argued with (that's why you didn't challenge his numbers).  Resi property investment is not a short term game, so he does have a valid point. 

Up
4

PI Investment has been all about capital growth, those oh so sweet tax avoiding gains. There has been scant focus on yield for some time. As such todays free fall in values stops that model deader than dog poo.

So where to from here. Yanks keep printing and remain the central currency. Then things can indeed sputter of for a bit (can kicked down road).

Or

Bonds raise further and debt is priced higher, or Europe is pulled in war, or US looses reserve currency and or defaults, or oil flow completely stops as the gulf decends into endless drone strikes on refinerys, or a targeted land tax is voted in etc. Or any combination of the above. Then the ponzi can indeed deflate quite a bit further to where income actually supports leverage/value.

Back you views, arrange your finances.... and role the dice...

PS. Just been to Qtown lakes. International money still flowing for ultra high end. The remainder is as soft as spring slush. Everyone is waiting for "cashed up" jaffas to start piling in again. It like they dont realise that train derailed 18 months ago.

🍿 

Up
7

AKL market going to look very sick by the end of summer, vendors are still in serious denial that prices are down 25% from peaks


Up
6

Hamish has no valid point because he is projecting future returns on past performance. It's investing 101 and every prospects warns about this.   

Up
8

He's projecting absolutely nothing (perhaps you are?), he's simply stating facts.  Or are you saying that the only projections that are valid are those that align with your view that housing is going to continue to fall ? (which by the way I think will happen)

Up
3

Is vs was. 

Up
3

Tulips were also a great investment (before they were not). 

Also a true statement, but a life altering poor investment if you got your timing wrong and purchased at the peak (like the NZ housing market). 

Up
7

Com'on that's a dumb statement and you know it.  If you buy anything at the peak it's a poor investment.

Up
3

Just reflecting your own line of reasoning back to you. 

Up
5

Looks like things have been busy while I was away at work - keep it up :-)

Yes, you do make a good point that just because the last 2 decades have seen a 2.6x in median values, it doesn't mean we will see similar returns in the future. However, for me, property is a great investment. I tend to spend the money I have in my account. I am no good at simply tucking money away in a savings account, or putting it in shares. I have OCD and can't stand the volatility of the sharemarket. Property on the other hand, is a whole different ballgame. Once you make the initial investment, you are committed to a long term, fiscally prudent, (forced) savings program.

Up
0

Looks like things have been busy while I was away at work

What a great post, whilst you have been busy working, we have been busy arguing over trivial things.  You have been productive, we have NOT.

Up
1

You've got no idea what's going to happen dude and you can't base future performance on past performance. How do you know it's not going to end up like this? https://fred.stlouisfed.org/series/QJPN628BIS

Up
3

True, he's got no idea what's going to happen in the future, nor do you or I or any other poster.  But note, he has said nothing about the future, he simply posted the values of the average house over the last 20 years up to the last known full year.  He's posted facts, simple facts, and some people on here are getting all upset because these facts show that values have gone up, significantly.

Up
3

My only quibble would be the last word in the original post should be 'was', not 'is'. 

Up
9

Exactly!

Up
1

Oh please he said "I can't think of a more perfect illustration of what a good long term investment property is. "  Given the context of his other drivel posts on here you don't think that is implicitly projecting into the future? Otherwise he would have use the word "was" instead of "is"

Up
5

House prices went up from $300k to $790k from 2005 to 2025, and as you rightly said: "No one knows where they will be in the future for sure".

It's that simple.

Up
3

And on that we agree

Up
0

note, he has said nothing about the future

He said

I can't think of a more perfect illustration of what a good long term investment property is

which implies property still is a good investment for the future

Had he used "was" he would've been perfectly correct. So would you have been

Reminder to everyone that the most effective manipulation comes from taking the truth and altering it just slightly

Up
9

Perfect example to highlight how bad housing is as a long term investment:

Date | NZ Median | 2026$ Real Value | House Real Return | MSCI World | MSCI Real Return
2006-06 | $310,000 | $516,811 | 0.0% | $310,000 | 0.0%
2011-06 | $360,000 | $518,461 | 0.3% | $261,146 | -27.2%
2016-06 | $500,000 | $691,308 | 33.8% | $429,833 | 15.0%
2021-06 | $816,000 | $1,024,984 | 98.3% | $899,358 | 118.6%
2026-06 | $770,000 | $770,000 | 49.0% | $1,956,855 | 278.6%

Housing annualised real return: 2.0% p.a.
MSCI World annualised real return: 6.9% p.a.

Up
5

LOL, "only up by 278.6%".  You're going to upset some people with these stats.

Up
3

No, that's my MSCI world stock index comparison. Sorry the formatting was a bit rubbish, have fixed now.

The real return for the median for the median house over that time has only been 49.0%.

Up
6

Oh, OK then, only up 49% then.  Since most buyers would pay only 20% deposit, that makes it a real return of 245%, whilst they enjoy living in it, or earning income if they rent it out.  Try inviting some friends for a BBQ in your share certificate, or raise your kids in it !

Up
4

I didn’t realise you were a professional turd polisher Yvil - but you are certainly showing your credentials as such in this comment section. 

‘Housing is always a great investment, but just as long as you purchased in 2010 like Hamish’ 

What about the people that you and other property bulls talked into buying near the peak who are now in negative equity and perhaps negative cash flow positions on their investment properties who are suffering deep regret for their purchases? (and potentially a life altering bad investment decision)

Up
4

IO

I'd be careful slaging off others. 

You have been continually calling a collapse. Back in 2019 you posted (I have a copy) that you had been calling this for seven years . . .  so it’s now 14 years that you have been calling Armageddon. This is influenced by your following of Shiller's prediction published 2005. 

If people listened to you over the past 14 years they would all stil be renting while their landlords made great capital gains at their expense. 


Hey, and before you call me a property bull yet again for being positive for a long period prior to the peak, in the year prior  I posted on  a number occasions: 

by printer8 | 18th Dec 20, 9:19am 

Clearly the current rate of housing inflation is unsustainable (even Bindi has publicly said so) and it poses risk of significant correction . . .  


Up
4

Aren’t you an Auckland based bank manager? (Was it ANZ?)

How is your low equity lending going to your portfolio of FHB from the past 5 years going?

Any interesting numbers you can share with us?

Up
0

Pretty desperate comment. :)

You can’t even get that right. It was your mate HouseMouse who baselessly suggested that and as he was wrong on so many accounts he has disappeared in embarrassment.
Cheers

Up
5

(Just as desperate and truthful as yours?)

No I’m pretty sure you said it yourself in order to prove how much of a property expert you were - while still encouraging people to buy property near the peak - while at the same time encouraging your adult son to sell out of his own rental portfolio. 

I remember being struck by how two faced it was - selling mortgages at the bank to FHB who didn’t know any better - while helping your son sell out at peak $$ to some poor soul destined to be in negative equity while paying your bank manager wages. 

Up
1

Why the low blow comment IO ???

Up
3

Why are you saying: "Housing is always a great investment" ?  I certainly don't think so. 

Up
2

I'm sure I don't have to tell you that a 2% annualized real return on the underlying asset is rubbish. Especially considering the risk taken on, levered up and able to go into negative net worth. Huge concentration, single country, single city even, very exposed to a litany of local risks.

You can also leverage stocks, in some ways more easily and with less risk than you can with a house. Buy the MSCI World Leveraged 2X Daily Net Index instead. Try take the house with you when you move or have cash in your bank an hour after deciding to sell.

Up
3

Yip how is the leverage working out now for those in negative equity? No mention of that from either Yvil or Hamish…but why would anyone want the truth to get in the way of a good story?

Up
2

Why the anger IO ? I simply said Hamish statement was true, which it is.  I even said that I believe that house prices are going to continue to go down. I have also never said that investment in RE is always good, I'm not invested in it anymore.  But I  can still recognise that Hamish's post is quite simply true.

Up
3

Not simply true. It is true in isolation if you aren’t willing to look at the bigger picture - just as any position can be made true if you cherry pick only the data points that benefit your own position.

As I say above, investing in tulips was brilliant until it wasn’t. 

Just as investing in RE was until 2021. It went from great to absolutely terrible - no mention of that by Hamish - only the good stuff without any of the bad. 

Up
3

Except it's not a 2% return because you generally put only 20% into it, so the annualized return becomes 10%, and it's tax free!  Then you have the benefit of living in your house, having friends over, seeing your kids grow up in it. 

Are your eyes opening up yet?

Up
3

And gold went up 682% over the same period.  

Up
4

And gold never misses rent, never damages your property and has practically zero admin. Set and forget 

Up
3

and you can leverage gold just like houses,you have to accept mark to market and margin calls, like every other grown up leveraged investment


Up
0

Good point Rampart, although Gols does not provide any return or shelter

Up
1

Kelvin Davidson was on the radio, man sounds down enough to be on medication, put away sharp knives etc.

It's a lost decade, 5 years in.

Up
4

Tale of two islands, a sea of red in the North, a majority of black in the South yoy.

Up
2

North Island population passes 4 million while South Island population grows faster | Stats NZ

The mental drag of low N island prices etc drags on 75% of NZers

I suggest the negative equity situation of FHBers from 2020 onwards is scaring the entire market

Cotality estimated 3600 FHBers but their assumption was FHBer had a 20% deposit; many would have actually had 10%, I think upwards of 10k FHBers will now be in negative equity.

Up
3

Yes many, many more than 4000, are in underwater Mortgageville.

This predicament is a tough suburb to live and survive within.

Often these now poor and destitue souls, were led there by unscrupulous property pumpers and Onewoof ogglers.


As always, the property pumpers, selfishly interested and land greedy will try to hide the truth.

They point to this and that, past and tired old stats, as some way to contrive and cajule a new set of usefull idiots to buy their flailing and now unloved property portfolios...... 

My heart weeps for the beached and burnt whales of property hoarding gamblerville.

Up
4

It really looks like all areas that overspeculated (Akl, Wellington and others) are down down down in ponzi town.

🍿 +⛽️ = 🔥 

Up
5

Wow that escalated quickly on a rainy Friday afternoon.   Resident Spruikers put up a good fight against a vastly higher number of merchants who correctly called future falls.   Lets call them Future Fall Merchants, upgraded from Doom as they were, in hindsight correct.


Up
7

Thanks for the genuine chuckle 😂

Up
0

It's interesting how Hamish asking AI about house prices over the last 20 years and posting it on here, triggered so many into highly emotional responses without actually being able to deny the numbers posted.

Up
0

Like many/most of my generation-now 81- the property market has been kind to me both in Scotland and here for the past 23 years, not because I am particular ability, but in a rising tide, all boats float. The only thing I can take any credit for is that I have bought properties in good areas like Mount Maunganui.

I watched the median price to income multiple hit 11 in 2012(Demographia) and now fall to around 7. For the sake of my grandchildren, I hope to see it fall further to around 5, if not even lower. What i would like to see disappear is the view that property should be thought of in investment terms. 

Up
3