By David Skilling*
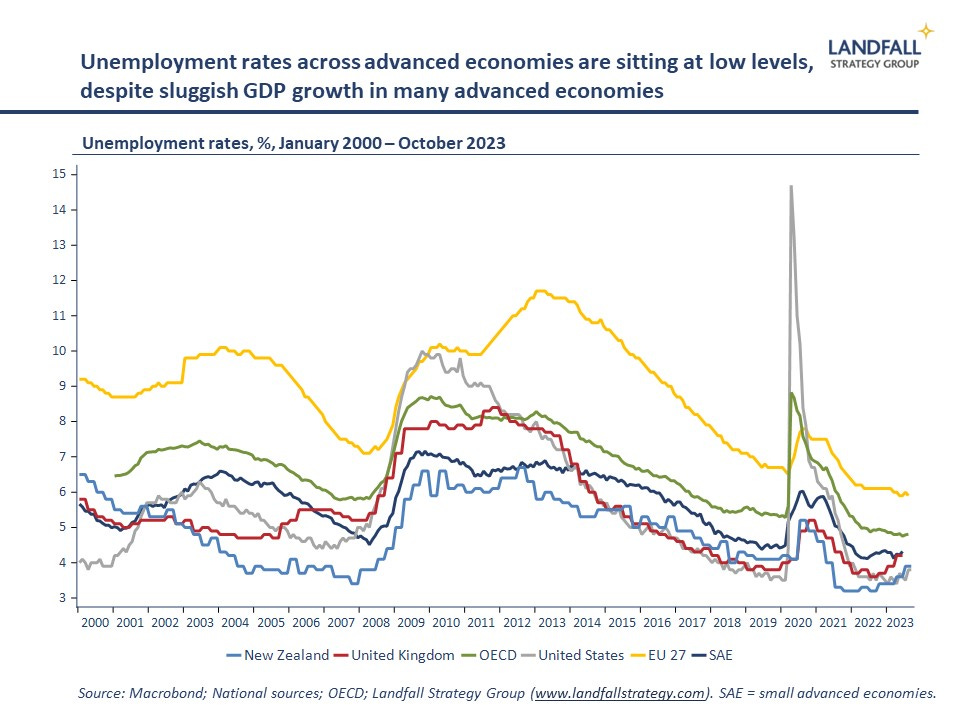
Across advanced economies and beyond, labour markets are tight with unemployment rates at or close to historic lows – 3.8% in the US, 5.9% in the EU (despite the eurozone being on the cusp of recession after this week’s data confirmed a Q3 GDP contraction), and 4.2% in the UK. A similar picture is seen across small advanced economies.
Employment levels have recovered above their pre-pandemic levels in most advanced economies. And job vacancy rates remain at high levels, even if they have come off their record highs. Part of this tightness reflects substantial churn in labour markets through and since the pandemic, as people move between jobs and occupations. Quit rates soared as people looked for better jobs, particularly moving out of sectors such as retail and hospitality.

Relatedly, preferences around labour market engagement have shifted. It is difficult to quantify this, but the pandemic experience reshaped the way that some thought about work; participation rates in some cohorts reduced (e.g. early retirement). And there are generational differences in attitudes to work: from quiet quitting to the lie flat movement in China. It is striking that employment has increased by much more than hours worked over the past few years, implying reduced average hours per employee.
This means that there are constraints on labour availability. Business surveys from the US and the UK to New Zealand commonly report that lack of workers is a major constraint on expansion.
Indeed, there are many examples of labour supply related constraints around strategic projects in the US and Europe. TSMC’s new semiconductor plant in Arizona is being delayed until 2025 because of a shortage of skilled construction workers. There are similar issues in Germany, where the (heavily subsidised) influx of planned semiconductor facilities (TSMC, Intel, and others) are confronting substantial labour shortages amid an aging population. Aspirations around industrial policy in many Western economies are constrained by the absence of workers.
Structural labour market tightness
Some of these developments are short-term in nature, reflecting the major shocks to labour markets through the pandemic. But some of these forces are structural: changed preferences are partly sticky, for example. And many economies are close to the upper bound of labour supply with high employment rates – meaning that labour supply growth will be more challenging to achieve than over the past few decades. There are fewer people available to draw into the labour market.
Looking forward, demographics will be a key constraint on labour supply. Across advanced economies (with the partial exception of the US), populations are aging – with weaker/negative working age population growth. In Europe, for example, the working age population is forecast to contract by ~20% by 2050. There are even more substantial drops in the working age population in multiple East Asian economies that are deeply integrated into the global economy, such as China, Japan, South Korea, and Taiwan. The working age population in Japan and South Korea are forecast to decline by 30-40% by 2050.
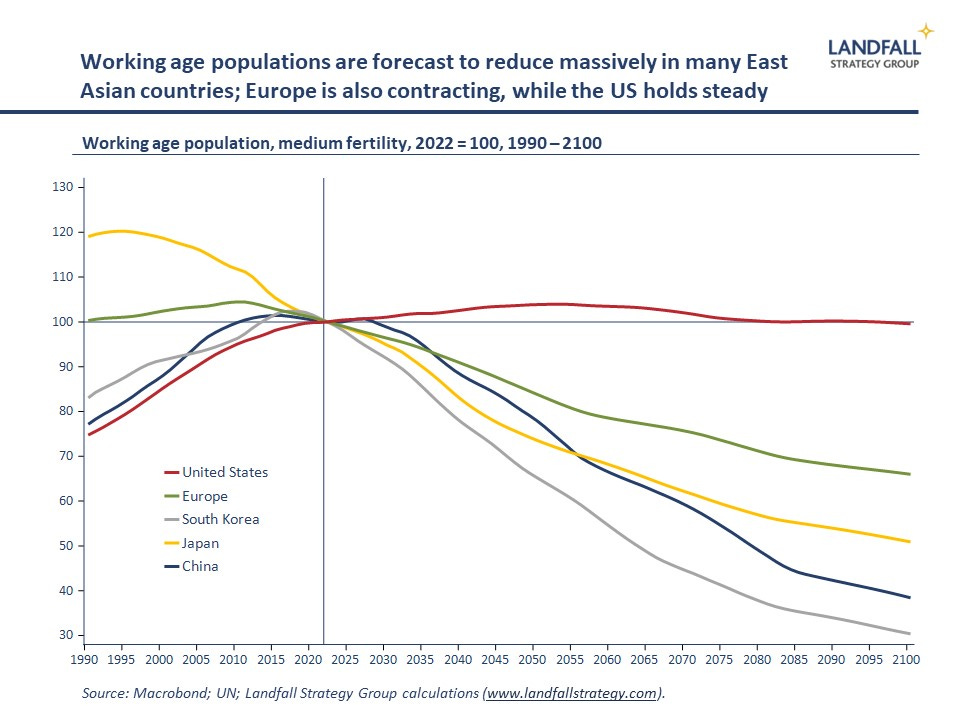
As discussed in a previous note, this will significantly constrain growth in the global labour supply – reinforcing tightness in labour markets and adding to wage pressure. There are regions of the world with stronger demographics, such as South Asia and Africa. But these economies are not currently deeply integrated into the global economy, and so the impact on global labour markets will be more gradual.
This suggests that labour shortages are likely to be a bigger concern across advanced economies than mass unemployment due to the impact of new technologies such as AI and automation. Of course, policy attention needs to be paid to ensure that people have access to the right skills to participate in the emerging global economy. But in general, labour markets are likely to remain tight.
Implications
Overall, these dynamics mean that bargaining power has shifted towards labour, allowing workers to demand better terms and conditions. This will mean upward pressure on wages, as well as more worker-friendly employment conditions (such as flexible working). This stronger bargaining position for labour is also reflected in the elevated levels of strikes/industrial action in the US, the UK and elsewhere.
Although the surge in inflation reduced real wage growth, this is turning around and we can expect stronger real wage growth – with nominal wage growth running ahead of inflation. This will likely compress firm margins as well as leading to price pressures across the economy.
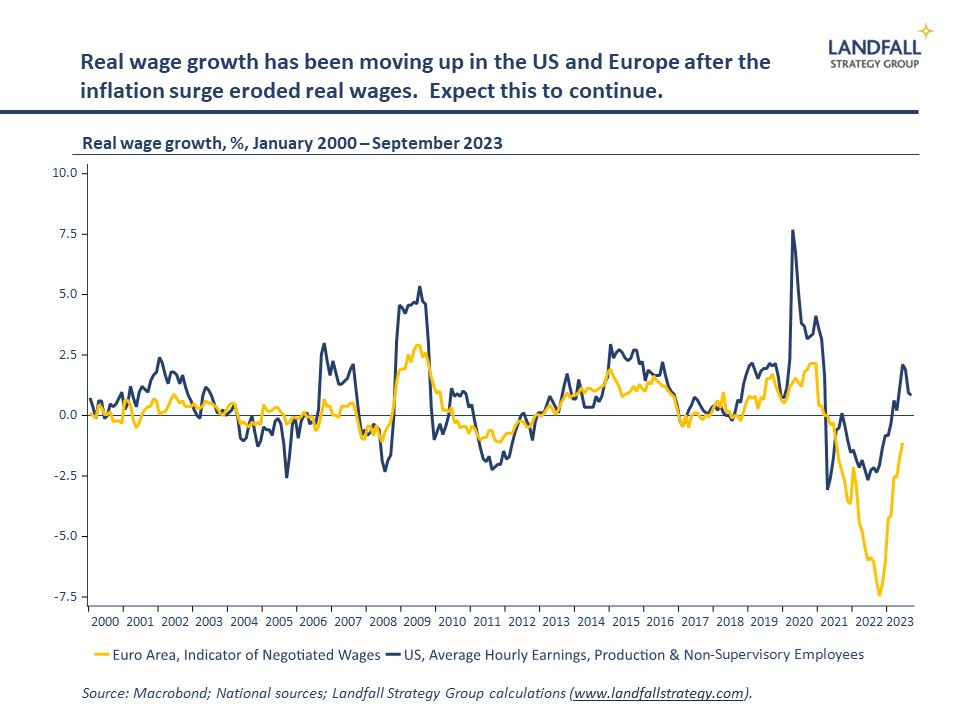
Sustained tightness in labour markets is likely to contribute to structurally higher inflation. The deflationary process from the 1990s was supported by a rapid expansion in the global labour supply; this process is now weakening if not reversing, which will put upward pressure on trend inflation. This is one reason why I expect structurally higher levels of inflation over the coming period.
There are a few implications of these labour market pressures. First, expect a stepped-up global war for talent – with labour-constrained economies more aggressively competing for migrants. Indeed, even countries like Poland and Hungary, with strong anti-migrant political lobbies, have been working to attract migrants from India and Pakistan to support the growth of key sectors (for example, the EV battery sector in Hungary).
And recent OECD data reported record migration flows across OECD countries in 2022. Many small economies, from New Zealand and Singapore to the UAE and Ireland, are experiencing very strong migration inflows. Expect economies to set migrant-friendly policies to offset the weakening organic working age population growth. Countries that can offer easy paths to integration (language, residency, etc) are likely to have an advantage.
A second implication is that tight labour markets and increasing labour costs will strengthen incentives for investment in automation, AI, and so on. These technologies can lift labour productivity, as previous notes have discussed. It is not a coincidence that countries with the most rapidly aging populations have the highest densities of industrial automation.
Third, variation in these global labour dynamics is likely to shift the location of economic activity around the world. Although abundant labour supply will not be the source of advantage that it was to the East Asian economies over the past several decades (because of declining labour intensity of manufacturing), there is still some advantage. Global supply chains are likely to be reshaped by access to labour, along with friend-shoring/de-risking dynamics and attempts to make supply chains more resilient.
One of the globalisation dynamics over the past few decades was to allocate production to locations with large labour forces. Current policy efforts to allocate production to economies with already tight labour markets in the name of derisking or resilience will lead to significant pressures. Indeed, industrial policy initiatives which attempt to reshore activity will be constrained by labour supply realities – as noted above. Blocs need to have access to labour as well as capital, technology, commodities.
Overall, tight labour markets will be a defining characteristic of the global economy over the coming decades – with implications from higher inflation to a new global economic geography. Firms, investors, and governments need to position for a labour crunch in many parts of the global economy.
Thanks for reading small world. This week’s note is free for all to read. If you would like to receive insights on global economic & geopolitical dynamics in your inbox every week, do consider becoming a free or paid subscriber. Group & institutional subscriptions are also available: please contact me to discuss options (more information is available here).
*David Skilling ((@dskilling) is director at economic advisory firm Landfall Strategy Group. The original is here. You can subscribe to receive David Skilling’s notes by email here.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.