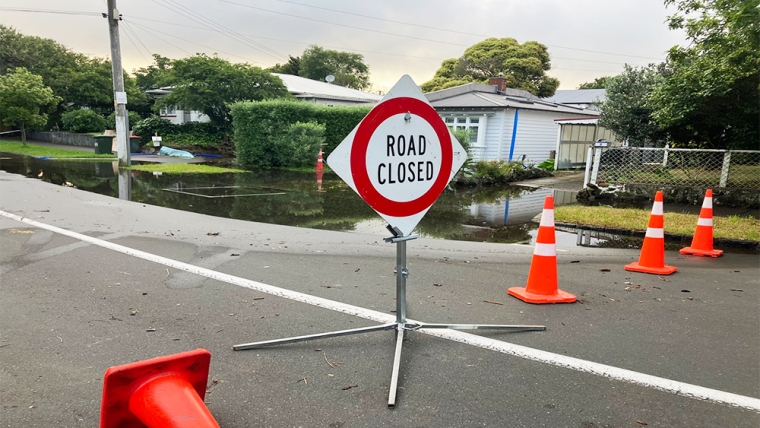
Insurers could walk away from some of Auckland’s most expensive residential areas, causing a “massive drop” in property values.
Massey University academic Michael Naylor, who has authored a book on the future of insurance, said a worst-case scenario from Auckland’s record-breaking storm was that parts of the city could become too expensive to insure.
He said cliff-top or cliff-bottom properties and homes along the foreshore are high risk, and insurers could roll over policies in those areas and hike premiums – but there would be no domestic competition to give consumers choice.
Homeowners in high-risk areas could try shopping for insurance from offshore providers but there was no guarantee those policies would be rolled over year-to-year so would bring a risk of becoming uninsured, Naylor said.
That could mean people have to pay three- or four- or five-times their premiums, he said.
He said climate change had changed the calculations for insurers, and they would take the maximum cautious approach to risk. Insurers used technology to map out which homes had flooded, or could flood, and could identify risk street-by-street and house-by-house.
“If you ever flood the bottom of your property, you’ll be marked as high risk. If you’re in an area where storm drains can’t cope, you’ll be marked as high risk. And customers aren’t really able to verify [whether they will be high risk] so they’ll be quite confused as to why some have premiums dropping and others don’t.”
Insurer IAG, which along with Suncorp dominates New Zealand’s insurance industry, said it was common practice for insurers to put temporary extra requirements in place for new insurance cover after major events.
It said it didn’t “currently have flood exclusions in place for residential properties in Auckland” and was still providing cover.
“New insurance applications are assessed on a case-by-case basis, as is usual practice.”
John Lyon, chief executive of underwriter Ando Insurance, said Ando won’t insure houses in areas subjected to repeated flooding, but it might insure them “for other perils”.
He said it’s hard to say an insurer won’t insure any homes in an area, and it considers insuring on a case-by-case basis. Lyon said, for example, there were some “perfectly good risks” in flood-hit Westport that have never flooded, and probably never will.
“But at the same time, you've got to be cautious. If a particular property is flooded three times in the last three years, then that's not insurable.”
He said the reality is there are some parts of New Zealand that will become very hard and expensive to insure.
“And repeated flooding basically becomes effectively an uninsurable proposition unless mitigation exercises are carried out.”
The same applied to cliff-top properties with erosion.
“I think if I owned a cliff-top property I'd be nervous about it, but that's just me being in the insurance industry. If there is a situation where there is gradual erosion happening on a cliff, and we've seen some photographs in the media over the last few days of properties that are just just hanging on there, they become uninsurable. Because effectively, it's inevitable damage and insurance is there for unexpected damage, not for inevitable damage.”
He said there had been some good examples of flood mitigation where insurers and councils worked together to reduce localised flooding, “but in some areas that's really, really challenging”.
Once homes became uninsurable, the question was who would foot the bill, Naylor said.
“If houses have to be removed from risky areas, who is going to pay for that? Who is going to compensate the existing house owner? And if you bought a clifftop property knowing it was a clifftop property, why should the government give you compensation?”
He said rich and powerful people live on cliff-tops and along the foreshore, and there would be immense pressure for the government to step in.
Assessment delays
On Thursday the Insurance Council of New Zealand warned it could be years before all claims are settled for flood damaged homes, cars and contents in Auckland.
The Council said this was an unprecedented event in terms of New Zealand's history for a flood event.
The Council’s consumer affairs manager Sarah Knox told Radio New Zealand people forced out of their homes due to flood damage should make a long-term housing plan.
Wayne Tippet, executive general manager for claims for IAG's AMI, State and NZI, said it was too early to put a timeframe on how long it might take to complete claims.
He said it had received 14,000 claims by 9am on Wednesday morning.
“We have teams on the ground assessing the damage – those with the highest needs are being prioritised first.”
On Friday IAG told investors the Auckland event would cost it more than $380 million.
Naylor said the experience in Christchurch and Westport after natural disasters showed it could take months or years for damaged homes to be properly assessed for repairs.
Tippet said the insurer was “making good progress” settling claims, and it was settling more than 200 car claims a day.
“The assessment process will include virtual assessments (where damage is light, and we can use photos) and face to face assessments when the damage is greater.”
Auckland Council has cancelled thousands of scheduled building inspections so its inspectors can get around the region to assess storm-damaged homes.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.