Reinsurance giant Munich Re Australasia says climate change is one of the most prominent emerging trends in New Zealand’s insurance market but the reinsurer’s appetite for risk remains the same.
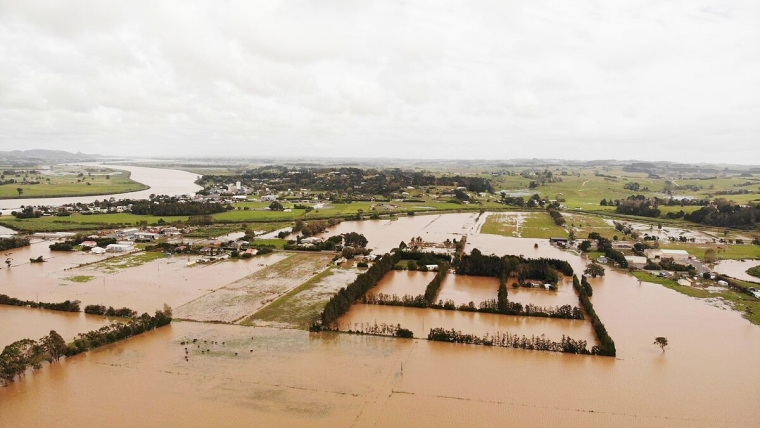
Munich Re Australasia's Managing Director Scott Hawkins says “unprecedented levels” of climate events have been felt in New Zealand – most recently the Auckland floods and Cyclone Gabrielle that hit the country last year – and it’s a bleak trend that’s surging globally.
Reinsurance, or insurance for insurers, transfers risk to another company to reduce the likelihood of large payouts for a claim.
“Another emerging trend is very much insurance affordability, which is being driven to a large degree by the increasing frequency and severity of events in New Zealand,” Hawkins says, adding that it’s not just a New Zealand specific topic," Hawkins says.
“If I look at the overall Munich Re portfolio and the losses that we're seeing come through globally on natural catastrophes, particularly what we would deem, as we call them, sort of secondary perils – so we think about things like bushfire and flood [and] hail events – they're increasing in frequency and severity in many parts of the world,” he says.
The climate might be changing in unexpected ways and bringing with it a larger frequency of losses, but one area Hawkins is firm the reinsurer hasn’t budged on is its appetite for risk.
“Our risk appetite has not changed based on the events that we've seen in the last four or five years across both Australia and New Zealand,” he tells Interest.co.nz, adding that it was “exactly what reinsurance is there to do”.
“Global companies like Munich Re take that volatility away from insurance companies – and from countries even. That's something that's been around for many years and will continue into the future.”
But on the back of that and the topic of insurance affordability, he says there’s a lot the industry needs to do.
The ‘industry’ includes governments and corporations to mitigate against this trend as well as the broader insurance industry. Hawkins also highlights New Zealand as one of the countries which is potentially at the forefront of this work.
“If I think about those risks, they're not a surprise with the climate changing as it is and as we have been researching it for many years – we fully expect the frequency and severity of some types of events to increase,” he says.
“From a risk appetite perspective, we still have an appetite for those types of risks. That's our core business. But of course, when we learn more, we need to reflect that in our forward view of how often and how large those events will be. And that then translates into pricing.”
Supports 'intelligent regulation'
There’s also been an increase in sustainability and climate-related reporting for corporations in recent years as well, as more consumers, customers and regulators want to know what measures companies are taking in this area.
Munich Re wants to see that continue and Hawkins says the reinsurer fully supports “intelligent regulation” when it comes to this topic – “we need to know what companies are doing and that they're doing the right thing,” – but there’s a need to “globally harmonise” this reporting.
Rather than every country having its own version of what that reporting should look like, he says it would be better to have standard reporting instead that applies to all countries.
“If I think about regions like Australia and New Zealand, where at the moment insurance affordability is certainly top of mind, we really need to think about if we have disproportionate reporting duties, that increases the cost of doing [that] reporting,” Hawkins says.
“And of course those costs then need to go into [insurance] premiums. So that's why we fully support the reporting, but that it’s fit for purpose, that we don't create an extra burden by the cost that's associated with that.”
The number of climate disasters and their severity in New Zealand and offshore might be rising but Hawkins says that events like floods and cyclones don’t concern the reinsurer because these types of events “aren’t a surprise”.
Forward view
Many things go into reinsurance pricing, Hawkins says.
One is the technical price, where Munich Re assesses the forward view – usually for the next 12 months – of expected frequency and severity of events, and how that then translates into price.
Hawkins says the competitive marketplace also has an influence in “pricing up and down” depending on supply versus demand.
“There have been some adjustments to pricing, particularly given the inflationary environment that we've had across the globe. When we have inflation, the values of assets go up, and when the values of assets go up, the size of the claims then also increase.”
As an example, he describes a property that has doubled in price becomes a total loss – and means that total loss has now doubled.
“Likewise, if the cost of repairing goes up because of inflation, then the cost of claims goes up in a sort of a proportionate way. And that’s certainly one of the factors that has been driving prices.”
In areas of unprecedented events, Hawkins says Munich may have a different view as to how often those events will happen in the future – which is then reflected in a forward view of pricing over the longer term.
“But I wouldn't say there's a standard and prices went up by ‘X’,” he says.
“It's really dependent on the client, their portfolio, what's happening in their portfolio, what's happening in the environment within which they operate.”
IAG deal
Munich Re alongside other reinsurer giants Swiss Re and Hannover Re entered into a quota share agreement with general insurer Insurance Australia Group, New Zealand's biggest general insurer, in 2017.
The agreement saw that the reinsurers received a combined 12.5% of IAG’s consolidated gross earned premium, in exchange for paying 12.5% of claims and expenses.
In January 2023, IAG told the market it had agreed terms to renew arrangements with Whole of Account Quota Share (WAQS) partners, Munich Re and Swiss Re, representing 10% of the 12.5% whole of account program that had been due to expire in June 2023.
IAG said last January that the new agreements were effective from January 1 2023 and had a term of five years.
“In an environment of constrained reinsurance capacity, the renewed agreements provide IAG with materially consistent financial outcomes and support our 15% to 17% medium-term reported margin target,” IAG's Chief Financial Officer Michelle McPherson said at the time.
*This article was first published in our email for paying subscribers. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.