The chief executive of IAG New Zealand says roughly a third of its customers received reductions to their insurance premiums over the last year.
The country’s largest general insurer reported its 2026 annual financial results on Thursday, revealing a decline in insurance profit and Gross Written Premium (GWP) growth. IAG NZ’s GWP edged down 2.7%, or $113 million, to $4.060 billion in the 12 months to June.
Its insurance profit slid much further, falling 22.9% to A$467 million, or NZ$563 million. It’s a decrease of NZ$167.4 million year-on-year.
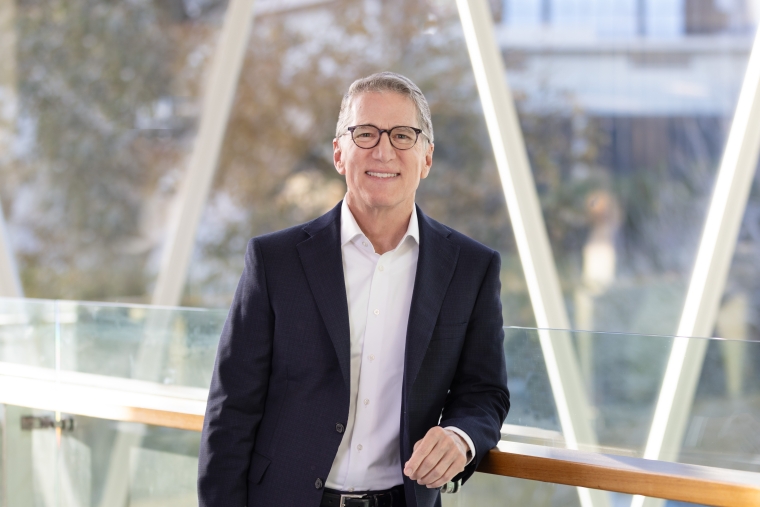
IAG NZ chief executive Phil Gibson, who became the general insurer’s new boss in February, described the financial results as “mixed” to interest.co.nz.
“It’s a story of two businesses, right? On the retail side [AMI and State], we’re serving more customers, we’re growing. We've got lots of tailwinds. So we're feeling great about that business,” he said. IAG NZ brought on 80,000 new retail customers in the 2026 financial year.
“Then you go to the NZI side, and through no fault of their own, they've sailed into stormy weather, the commercial soft market.”
IAG NZ’s business insurance is primarily provided through NZI, which supplies commercial, motor and home policies primarily through broker networks.
Over the course of his 30-year international career in insurance, Gibson said he had seen a “soft” commercial market like the present environment just four times.
“I've seen my share of commercial markets [and] that's what we're in right now. Prices go down, premiums go down, they go down for everybody,” he said.
“So to keep clients, you have to make tough decisions around do I let premiums go down, or do I hold my line and say I know where my pricing is? And that’s a tough balance to negotiate.”
According to Gibson, businesses are currently experiencing “tough times”, with many facing declining revenues and payrolls, an inability to pay for insurance and potential closure. But with time, these conditions will eventually “level out” and eventually recover, he said.
“It happens every cycle and we know what's going to happen,” he said. “In the meantime, we took out a lot of costs last year to try to make sure that we're as efficient and as effective as we can be, good times or bad. That's our job.”
Gibson said “many” IAG NZ customers received premium reductions during the 2026 financial year. He couldn’t provide the exact percentage because it varied by cover – home, auto, and contents – and also brand. But he put the amount as “roughly a third” of IAG NZ’s customer base.
Around one in two NZ households have a relationship with IAG NZ and the general insurer has 1.7 million customers across the country, according to its 2030 growth strategy published in May.
“This is the benefit of our new technical pricing models. We're really getting better instead of pricing for the community, pricing to your actual address of the home and the type of the home and how likely the specific property is to have a loss,” Gibson said.
“So we're getting better and better with precision on that. That's why we saw some customers' premiums went up and some went down.”
A report from Treasury earlier this year found insurance premiums have increased three times more than the Consumers Price Index (CPI) inflation since 2011 and risen by over 40% in the past two years.
Asked if NZ was facing an insurance affordability crisis, Gibson said it was in IAG NZ’s “best interest” to keep insurance affordable for as many people as possible.
“I absolutely don't want insurance to become unaffordable,” he said. “That’s why every day we're thinking about ways we can make this business more efficient for customers.”
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.