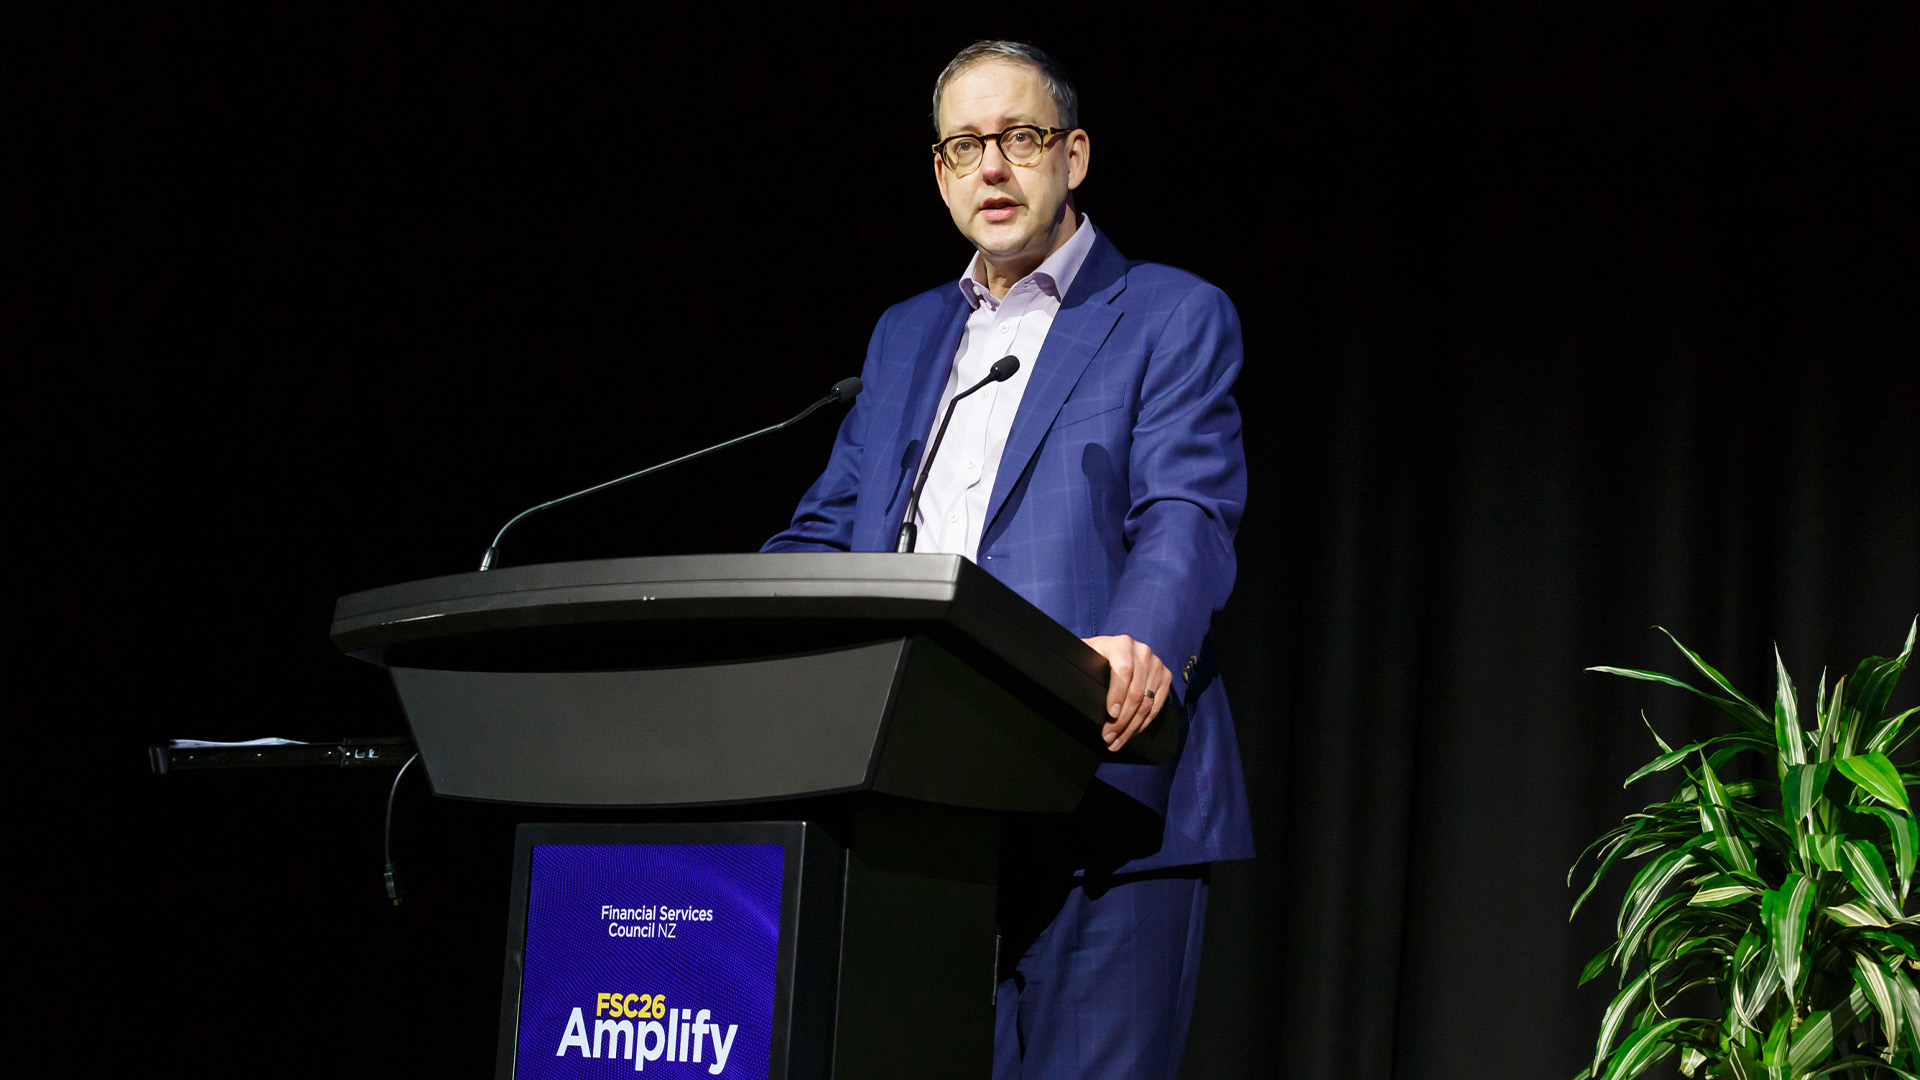
A reverse stress test done on life and health insurers has prompted some of them to strengthen their risk management, the Reserve Bank’s assistant governor of financial stability, Angus McGregor, says.
This includes doing things like having stronger capital triggers, reviewing reinsurance arrangements, increasing cyber cover and making improvements to recovery plans.
The Reserve Bank (RBNZ) conducted a reverse stress test on five life insurers and three health insurers. These insurers account for more than 70% of premiums in their respective sectors.
The RBNZ conducts stress testing to assess banks and insurers’ resilience to severe but plausible risks such as economic downturns. A reverse stress test starts with a severe outcome and works backwards to identify the events that could cause it.
For this reverse stress test, the outcome was an insurer’s solvency margin falling below zero. The RBNZ describes a solvency margin as the amount of solvency capital that would remain after the stress.
Shocks featured in these scenarios for the insurers included a combination of sustained medical claims inflation, cyberattacks, reinsurance disruption and a pandemic.
Insurers face different vulnerabilities
A RBNZ bulletin article on the reverse stress test said that life and health insurers faced different vulnerabilities.
“Life insurers were more exposed to sudden increases in death and critical illness claims and disruption to reinsurance. Health insurers faced pressures that built over several years as healthcare costs rose faster than expected. Higher capital requirements added further pressure in some scenarios,” the RBNZ said.
Reinsurance disruption appeared only in life insurer scenarios, “reflecting life insurers’ greater reliance on reinsurance to manage large claims”, the RBNZ said, while cyber risk affected both sectors by disrupting operations and limiting insurers’ ability to respond to the wider stress.
The RBNZ said claims were generally among the largest sources of pressure including mortality, critical illness, disability and health claims.
Across the eight insurer-specific scenarios, the modelled stresses reduced the participating insurers’ combined projected solvency margin by almost $1.7 billion, producing a $200 million shortfall before additional mitigating actions.
“Because insurers tested different events, severities and timeframes, these figures do not represent the effect of a single industry-wide event,” the bulletin said.
“The additional mitigating actions modelled by insurers restored their projected solvency positions above the regulatory minimum, but their effectiveness was not assured. Recovery often depended heavily on one or two actions, such as increasing premiums, reducing costs, obtaining capital or changing reinsurance arrangements.
“Their effectiveness depended on customers retaining cover, funding remaining available and reinsurers continuing to provide cover at an acceptable cost. These actions could therefore be delayed, less effective or unavailable during severe stress.”
Recovery plans: repricing, cost cutting and underwriting changes
The RBNZ said after modelling a solvency breach, insurers tested extra mitigating actions that could be taken to help restore their financial position.
“Recovery plans were more effective when they were linked to existing capital management arrangements. Early warning indicators, such as deteriorating economic conditions or rising claims, enabled actions to be considered before solvency came under severe pressure.”
Extra actions were connected to defined capital thresholds, the RBNZ said, including insurers’ own target capital buffers providing a structured basis for escalating the response as solvency deteriorated.
These actions included repricing, cost cutting, benefit/underwriting changes, capital actions, new business volume management, asset management actions, operating actions, reinsurance and risk transfer.
Premium increases
When it came to repricing, this was mainly premium increases “to improve income and respond to higher claims costs”, the RBNZ said.
“Health insurers relied particularly on premium increases to offset sustained growth in medical costs. Some insurers with access to parent company support chose not to assume a capital injection, providing a stronger test of their other recovery options.”
The RBNZ said the modelled actions restored every insurer above the regulatory minimum but didn’t always return them to their starting position.
“Some insurers remained below their opening solvency margin, and recovery often depended heavily on one or two key actions.
“Premium increase effectiveness depended on customers being able and willing to retain their cover. Capital raising depended on funding or shareholder support remaining available, while changes to reinsurance depended on cover being available at an acceptable cost. Under severe stress, these actions could therefore be delayed, less effective than expected or unavailable."
The RBNZ said the exercise reinforced the importance of acting early and planning for escalation.
“Recovery plans should clearly link warning indicators and capital thresholds to the actions an insurer would take as conditions deteriorate.
“They should also set out when the Reserve Bank would be engaged and how capital would be restored to an appropriate level, rather than simply back above the regulatory minimum. Stress testing can also be used to assess whether existing target capital buffers remain appropriate under severe conditions.”
Test provides insights into vulnerabilities and risks, RBNZ’s Angus McGregor says
The RBNZ will provide individual feedback and monitor participants’ progress in addressing the recommendations. The findings will inform supervision, policy and future stress tests.
McGregor said the reverse stress test provided insights into vulnerabilities and risks for insurers, and their preparedness to manage these.
“The exercise prompted some insurers to strengthen their risk management in response to vulnerabilities they identified. Steps included stronger capital triggers, reviews of reinsurance arrangements, increased cyber cover and improvements to recovery plans.”
By the numbers
The RBNZ said the lapse rate, when the proportion of policies in force at the start of the year lapse or do not get renewed, increased from 7% to 11%, while growth in lives insured slowed from 4.2% to 1.4%.
The RBNZ said 35% of adults reported having private health insurance in 2024/2025.
About 43% of health policies were through employer or other group schemes in 2025 and major medical cover accounted for about two-thirds of health policies in 2025.
"In November 2025, the Reserve Bank reported that sustained operating losses over the preceding two years had reduced health
insurers’ solvency margins by nearly 40 percent. Capital nevertheless remained well above regulatory minimums."
The central bank has noted that claims costs have risen sharply, with the average health claim paid per member increasing from $1097 in 2021 to $1921 in 2025.
"The increase was consistent with greater use of private healthcare and higher treatment costs, including labour, supply and medical technology costs," the RBNZ said.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.