
Today, we are launching a new way to assess and compare KiwiSaver fund performance.
We are doing this because the traditional way to compare does not realistically reflect how KiwiSavers build their savings.
This is a Beta launch.
The present way fund performance is reported (and the way we have been reporting it until today) is to show the gain (or loss) in the unit price of the fund and report that on a per-cent-per-annum basis. But to a large extent, it assumes the member's funds are at a similar level over the period reported on.
Even the 'new' MBIE-mandated way to compare assumes a standard fund amount.
However, most KiwiSavers are adding to their funds on a regular way every pay period, and these monies are collected through the tax system and paid to the funds by the IRD every month.
And as the years roll by, most people get increases to their pay, which also raises the contributions they, and their employers pay.
In this way, your KiwiSaver grows incrementally every month, building from both your contributions, your employer (and government) contributions, plus (hopefully) growth in the fund unit values.
This regular saving means that Fund unit price growth has minor impact when you start out, but it has a much greater effect when your fund balance is higher - which is what it will be now.
The differences in approach can be seen best graphically:
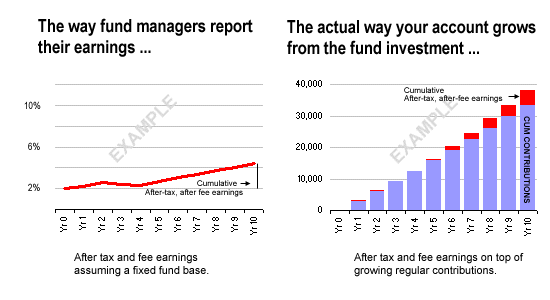
Our new system adjusts the way we report returns, tracking the regular build up of the fund balance, and the earnings on those increasing balances.
We will be reporting both methods of reporting returns. But our unique method much more accurately reflects how most KiwiSavers save, and by focusing on $ returns, rather than % returns it is much easier for you to get a sense of the value your fund manager is adding.
Here is a table of the five default funds using the new perspective:
| Default Funds | Cumulative $ | + Cum net gains | Effective* | = Ending value |
| since April 2008 | contributions | after all tax, fees | cum return | in your account |
| to Sept. 2013 | (EE, ER, Govt) | $ | % p.a. | $ |
| AMP** | 17,096 | 2,573 | 4.69 | 19,669 |
| ANZ Investments | 17,096 | 3,106 | 5.56 | 20,202 |
| ASB | 17,096 | 2,871 | 5.18 | 19,967 |
| Mercer | 17,096 | 2,481 | 4.53 | 19,577 |
| Tower | 17,096 | 2,853 | 5.15 | 19,949 |
(* This is the equivalent cumulative annual average return to achieve the after-tax and after-fees gain between the total contributions to the account and the current value of the fund for our benchmark KiwiSaver.)
(** Note for the members of the old AXA default fund. Your account has now been transferred into AMP, but the numbers above don't actually apply to you; they are just for the original AMP default fund members.)
Obviously, we do not know your personal income and earnings, so the results above aren't your's.
We have modeled a benchmark KiwiSaver individual.
In our case, we have established this benchmark:
- a full-time worker,
- on a median income,
- who was about the 500,000th signup to KiwiSaver (that is, at the end of March 2008),
- who was aged 28 on March 31, 2008,
- who has contributed 2%/2% until March 2012, and then 3%/3% (less ESCT) since,
and from the LEEDS database (brought up-to-date with subsequent QES releases), we can apply a realistic regular savings cash-investment stream.
To this, we apply the Kickstart bonus, and the matching "member tax credit" annual Government contribution on the dates those happened. We also deduct the annual Scheme fee. And most importantly, we apply the monthly unit prices for each fund. We then deduct the PIR tax for this benchmark person at their income band.
We even include the 'use-of-money' credits you will see in your own KiwiSaver statement.
We think this accurately mimics what happens for a 'median' fund member on their KiwiSaver statement and represents a fairly calculated return, one that can be compared between funds, one that is net of all fees and all tax.
By following our benchmark KiwiSaver, we can follow her through income changes (increases) as their career progresses. Contributions by both employee and employer rise in dollar terms as pay goes up.
By using the LEEDS database (which is essentially the DED/PAYE database collected by the IRD), we are using a huge sample of actual payroll earners in New Zealand.
As this is a beta launch, we are interested in your feedback.
(Please note that our new analysis can only be done for funds that supply unit prices. A small handful however won't supply them.)
As the months roll out, we will be adding the results to each fund page, and updating them each quarter. We will only be reporting the 'since inception' $ gains and %pa returns, although we will be comparing these to what we reported last quarter.
At this stage, the largest part of your KiwiSaver fund balance is what you, your employer and the Government contributed. As the years roll by, the skill of the fund manager to grow these contributions with after-tax, after-fee gains will become more important.
So far, across the industry, some fund managers have done a very ordinary job.
There is $17 billion currently in KiwiSaver funds, $15 billion are the base contributions. It is vital that the funds management industry do much better than they have to date.
You should not tolerate poor long-term performance. There are things you can do about it however. Selecting the right type of fund is one thing; selecting a fund manager who delivers in the long terms is another. KiwiSaver has been going seven years now, so we can certainly assess long-term performance now and benchmark that against funds with similar risk and investment profiles.
The resources in the website allow you to do that.
This new return assessment tool gives you a practical way to compare them fairly.
We will be publishing a separate review of 'regular savings returns' for each class of KiwiSaver funds, and will do this quarterly when all the data has been received from the fund managers.
We welcome your feedback, either below in the Comment stream, or via a Feedback message.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.