
By Bernard Hickey
It is the great conundrum of New Zealand's investment scene and the great mystery of the Auckland economy.
Why has the median house price risen 25% in Auckland in the last two years to over NZ$620,000, yet the median weekly rent for a three bedroom rental has risen just 6% to NZ$550?
Why have rents not kept up with prices in a market that everyone from the Auckland Council to the Housing Minister and the Reserve Bank have said is short of housing supply and faces a migration boom?
The numbers look even more extreme going back to 2007. Auckland's median house price has risen 38% since then, while rents rose just 15%.
Surely the laws of supply and demand say rents should be rising at a much faster rate?
Rents and prices certainly are rising at similarly high rates in Christchurch, which does definitely face supply shortages and increasing demand from more workers receiving higher wages.
Why aren't landlords able to force through rent increases?
It's certainly not for lack of talking about it or a lack of reasons.
House prices have certainly risen, which means already low rental yields have fallen even further below alternative investment options such as bank term deposits. These bank deposit interest rates may feel very low at an average of 4.7% before tax, but they are up almost 0.5% since March and above the current implied rental yield before any expenses of 4.6% in Auckland.
Costs have risen too.
Advertised floating mortgage rates are up 0.75% to around 6.4% this year, although many rental property investors will have taken advantage of the cheap fixed mortgage deals being offered by banks able to borrow cheaply offshore and locally. Auckland's property rates have risen by a cumulative 38% in the first four years of the Auckland Super City and maintenance costs have risen 16%.
The Government's tax changes in 2010 also stopped landlords from claiming depreciation on their buildings.
Landlords have taken an enormous dollop of pain over the last couple of years. Therefore, there's no shortage of incentives to put up rents. Yet still, rents haven't risen very fast.
There is a very free and open market for rentals in Auckland with good information and little regulatory intervention gumming up the works so a market failure can't be blamed.
Essentially, rents are limited by the growth of tenant incomes.
Ultimately, rental property investors are not choosing to buy and hold these properties because they provide a regular after-tax yield that is superior to other investments of a similar risk. They are buying them for the expectation of exceptional and regular tax-free capital gains that can be earned from a highly leveraged investment.
They are taking advantage of the capital adequacy rules in banking systems globally that incentivise banks to lend against land and buildings.
And so far that strategy has worked spectacularly well.
It's also been affordable in the short term because interest rates have been historically low, and remain only just above those lows for landlords who have fixed below 6%.
The New Zealand Property Investors Federation this week even cited IRD figures showing landlords reported NZ$1.476 billion of taxable profits in the year to March 2013, while interest rates were at those record lows.
It all makes perfect sense while house prices keep rising at 10% plus per annum and interest rates stay below 6%. A rise in mortgage rates to over 8%, which the Reserve Bank is currently forecasting, would break the investment logic behind Auckland rental property, particularly when rents are only rising broadly in line with worker incomes.
The scale of the gap that has opened up between rents and house prices was reinforced this week with the release by Strategic Risk Analysis' Managing Director Rodney Dickens of his analysis of national rents and house prices.
It showed how a close relationship between the two broke completely around 2002 and they have diverged dramatically since then.
It has driven New Zealand's house prices 70% above their long term average relative to rents, which makes them the highest in the OECD relative to rents. That measure is a national one, so the Auckland one would be even more extreme.
So why would Auckland investors double down on property that is at least 70% over-valued at a time when interest rates are rising and rents are not even close to keeping up with rates and maintenance costs, let alone interest costs or any sort of comparable alternative?
The simple answer is because they can being given low fixed mortgage rates, and because they are second-guessing the powers-that-be, who have wrongly predicted much higher interest rates and subdued house price inflation for almost a decade.
Property investors have successfully bet that politicians will never impose a capital gains tax, that Auckland's NIMBY home owners and their captured councillors will never allow significant new housing supply, that migration will keep surging and that inflation will not rise sharply.
They could be right on all counts for some time to come. But for how long?
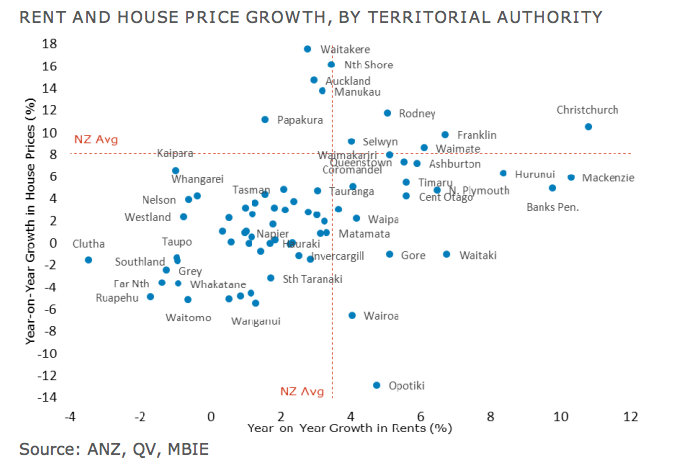
Here's an ANZ compiled chart showing rent and price growth over the last year by territorial authority.
-----------------------------------------------------------
A version of this article was first published in the Herald on Sunday. It is here with permission.
(Updated with SRA and ANZ charts)
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.