By Gareth Kiernan*
If you’ve gone to the fridge and taken a swig of milk from the bottle lately, you will have noticed it’s got lumps in it – which is hardly surprising when you look at the “best before” date.
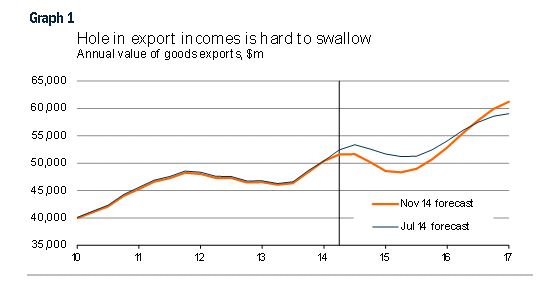
Prospects for the dairy payout and GDP growth looked pretty tasty back in February, but things have soured markedly throughout the course of this year.
Plunging dairy prices will have significantly reduced farmers’ appetite for spending, and there will be a number of highly leveraged operators who will be feeling nauseous about the payout possibly dropping below $5/kgms.
The lid will be kept on economic growth in many provincial areas due to the dairy sector’s struggles, although soaring meat prices will mitigate the negative effects in some regions.
Elsewhere in the kitchen, the construction sector is coming to the boil across Auckland and Canterbury.
This activity has contributed to a record influx of migrants looking for their next meal ticket.
More building work and above-average population growth will be key factors helping to keep nationwide economic growth above 3.0% pa until early 2017.
The lower outlook for dairy prices and GDP growth means that fewer interest rate rises are on the menu over the next couple of years. Recent data shows that inflationary pressures have been kept on ice so far, despite the strong performance by the economy and tightening labour market over the last 18 months.
We now expect the official cash rate to be at just 4.0% by the end of 2015 and 4.5% by the end of 2016.
This combination of factors has also taken the heat out of the New Zealand dollar.
We expect the TWI to fall by 18% over the two years to September 2016 as international investors enjoy improving relative returns elsewhere, such as in the US.
A side dish accompanying the lower exchange rate will be higher tradable prices – so even though domestic price pressures will be less intense than we had previously expected, inflation is still set to top 3.0% pa during 2016. More expensive imported goods will make it more costly for consumers to satiate themselves and cramp growth in the volume of household spending, which will slow from 3.2% pa in June 2015 to 1.9% pa by March 2017.
The government was hoping to dine out on a return to surplus in the current fiscal year.
Although we are still forecasting this outcome to occur, the target is in jeopardy due to the risks of reduced growth in the tax take.
Nevertheless, the recipe for government policy over the next three years is mostly more of what we’ve been fed over the last six years – spending restraint, with a focus on populist “problem” areas such as child poverty, housing affordability, and the Resource Management Act.
----------------------------------------------------
This piece is a light-hearted overview of Infometrics latest economic forecasts. The full forecasts are available to subscribers at Infometrics.co.nz.
----------------------------------------------------
Gareth Kiernan is the managing director at Infometrics, an economic consultancy and forecasting service, and he manages the forecasting team. You can contact him here »
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.