
By Janine Starks*
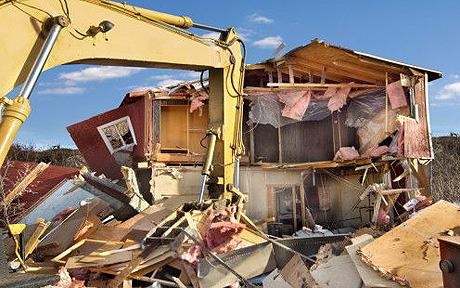
Imagine this; two houses in the same street – a liquefied red-zone street in Christchurch, where the residents must up-stakes and leave. The houses were built at the same time, from the same materials and they’re the same size (hang on, one is actually four square metres bigger than the other, but near enough). They have both been classed as a ‘total loss’ by their insurers and both are covered by replacement insurance policies. But that is where the similarity ends.
The first insurance company settled their claim with their customer a few months back. The insurer sent in a professional firm of quantity surveyors, who added in sensible things like ‘preliminaries and general’ (that covers a multitude of things from council consent to an onsite portaloo), contingencies for price increases and professional fees. They came up with a number of $430,000, took off the $115,000 already paid by EQC and settled the rest.
In this case the insurance policy was what I would call the ‘Rolls-Royce’ variety, because it allowed a cash-payout at the replacement value. Most policies I’ve come across don’t allow this. Regardless, this can be set aside because it’s the method of calculation we are looking at.
A few doors up the road, quite a different conversation is going on. State Insurance sent in their project managers Hawkins construction to price up a rebuild. Hawkins calculations come to just over $1,000 a square metre. When you add on GST and a few bits and bobs like fencing and the driveway, it works out around $1,200 a square metre, or $234,000. A few doors down, they got $430,000. That’s a $200,000 difference, in the space of a couple of cartwheels to a neighbouring property.
Rateable value vs replacement value
Even more perplexing, the rateable value of the house insured by State is $370,000 ($260,000 for the house and $110,000 for the land). State Insurance can build a brand new replacement house for $26,000 less than the rateable value. For this family, even though they have a ‘total loss’, they would be better off with the government offer, leaving the tax-payer to foot the $26,000 difference.
The taxpayer feels stung and the family concerned can’t believe their insurer can replace their house so cheaply, when other insurers are using different calculation methods.
This family live in the red-zone and they can’t afford to borrow more to get a new section. The method State uses to calculate the value of their home matters enormously, because they have to accept an ‘alternative offer’.
What are their options for the house-component of their payout?
In order of attractiveness:
1. First place; the government. With a rateable value of $260,000, they win hands down. I doubt they’ll be thrilled – as a taxpayer I’m not.
2. Runner up; State Insurance, with an offer of $234,000 if their customer wished to purchase an existing second-hand house. This replacement value can’t be taken in cash (the policy is clear about this and the technical answer is that State have a contract with their re-insurer which mirrors the contract with their customer – if they pay cash when the contract prevents it, they won’t get reimbursed).
3. Bronze plate; State Insurance, with a cash offer of $195,000 for the pre-quake market value. That’s 25% below the rateable value.
Is anyone aware of well maintained mid-sized homes selling that cheaply pre-quake? I can only guess States Valuers’ split the land and house prices in quite different proportions to that of the council’s rateable value, giving a distortion.
With sucked in cheeks and pursed lips, I spoke to State Insurance to get to the bottom of things. After a number of conversations and written evidence provided, I was left perplexed. The one thing about the top brass at State is that they are good communicators. They’re open about how they calculate their payouts and they provide evidence. It takes the wind out of your sails a bit.
In this situation, the home could be described as a ‘package home’. One of those smart, but simply designed houses for which TV jingles abound. State was able to show me plans for three very similar homes from Benchmark, Jennian and GJ Gardener Homes which ranged from $200,000 to $220,000 including GST. Each was about $1,200 a square metre.
If the family could buy another section, State say they could easily replace their home for this price as this is the “true cost to replace a home, which is what the policy is designed to do”. They tell me that Hawkins utilise independent professionals such as quantity surveyors and loss adjustors and their numbers have been market tested using prices from a range of builders across the region.
They also factor in all costs required to get the house to the point of consent.
Spot the difference
One of the differences which I can spot in States policies, is they don’t pay out all professional costs as a matter of course (some insurers will).
For example, with architects’ fees, they will only pay them if they are necessary and with a ‘package’ home they are not essential. State also won’t include the cost of project management fees from Hawkins, in the replacement value. You could argue this isn’t entirely fair as very few people are capable of managing their own rebuild.
If you don’t have the privilege of a full-service architect, you need a project manager. This is a very real cost, but State say it’s “only payable if incurred” and won’t factor it into an alternative offer.
What it comes down to is that Home Insurance Policies which give cover for ‘full replacement’ might look the same and smell the same to most of us, but the payout calculations between different insurers can vary to an enormous degree.
Two seemingly reasonable methods of calculating a payout produce entirely different results and co-exist on a spectrum of commercial-fairness. The bottom line is that it matters who you are insured with.
To be fair to State, these anomalies come about when customers can’t rebuild on their own land.
If the customer could supply land, a like-for-like home would be provided under the policy.
Room to negotiate?
When it comes to the next steps for this family, they have a number of options.
1. Put in a formal complaint to State: all insurers have an internal complaints system. The cynics will roll their eyes, but rest assured insurers take a formal complaint seriously. A full review will be carried out with more senior staff involved. State tell me they may even get a mutually agreed independent third party to carry out the review.
2. Get your own quantity survey. This might cost $500-$1,000, but it gives you evidence from an independent expert on the rebuild cost of your home. This could help with negotiations.
3. See a lawyer. Lawyers are a great second pair of eyes, will spot areas of the contract you have missed. They are calm negotiators and can talk to your insurer on your behalf. They’ll give you a practical perspective on the issue.
Do you have a question for Janine?
Email her directly at starkadvice@gmail.com with the subject line: Financial Agony Aunt. Anonymity is guaranteed.
*Janine Starks is Co-Managing Director of Liontamer Investments. Opinions in this column represent her personal views and are not made on behalf of Liontamer. These opinions are general in nature and are not a recommendation, opinion or guidance to any individuals in relation to acquiring or disposing of a financial product. Readers should not rely on these opinions and should always seek specific independent financial advice appropriate to their own individual circumstances.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.