
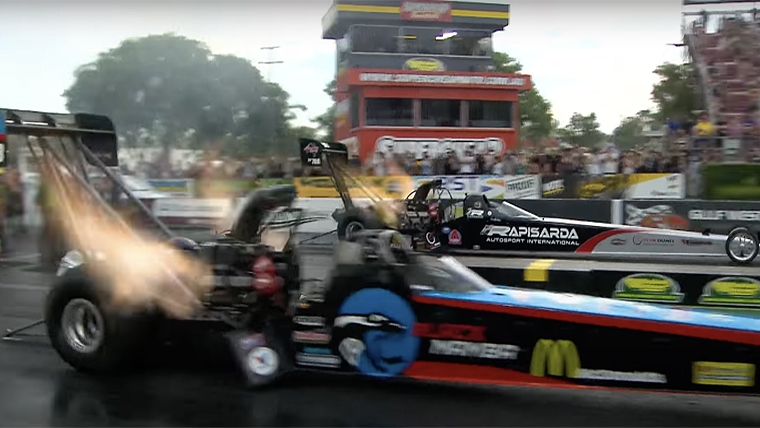
The starting lights just turned to orange and the two political dragsters of Labour and National are getting ready to burn budgetary rubber in the race to Election 2023.
They now both know they have a lot of nitromethane and rubber to burn in a fiscal drag race over the next year, especially at the end when inflation is likely to have receded as a near-and-present danger for the Reserve Bank. By then, mortgage rates and bond yields are expected to have gone over the hump and be on their way down.
Expect Labour to be dreaming up new forms of middle class welfare over the summer that it can pitch as healthy for society and not (very) inflationary in the election campaign. Expect National to double down on the rhetoric about 'fiscal creep' and look to hand back plenty of those tax revenues to those who earn the most and those with multiple properties. Unlike Liz Truss, both Grant Robertson and Nicola Willis have plenty of budgetary room to move without spooking markets or worrying the Reserve Bank too much.
This week's Crown Accounts show the Government's financial position is in rude, good health, despite Covid. In some part, it's so strong because of Covid. The Operating Balance Excluding Gains and Losses for the year to June 30 was $9.7 billion, which was just half the deficit expected just five months ago. That's because tax revenues were $5.8b more than forecast and spending was $3.9b less than expected.
The Inland Revenue Department's new computer system is now a finely tuned machine sucking every last drop of tax out of PAYE, corporate income and GST in an economy that grew 5.1% in nominal terms over the year. Just as the dragster with the biggest wheels and engine goes fastest, the Government with the fastest growth in nominal incomes grows its tax revenues even faster. High inflation turns the IRD's Hoover into a Dyson with a turbo button.
Government subsidies boost profits to $71b
The phenomenon of fiscal drag and higher profit margins with fast-growing top-line business revenues is an impressive thing from an IRD point of view. Households are seeing (but not feeling) annualised income growth of 8% to 10% because they're working more hours and are getting hourly wage increases of around 5%. That means they're migrating up the PAYE tax thresholds to the higher tax rates. That $180,000 per year threshold for the new 39c tax rate seemed a long way away for most in 2020 when Labour pitched it at the election. Now it's racing up in many taxpayers' rear vision mirror at a great rate of knots. PAYE revenues rose $4.3b or 11.2% for the year, which was more than double nominal GDP growth and included $3.3b in extra taxes from higher wages and jobs growth.
The same leveraging effect of strong nominal GDP growth was evident in corporate tax revenues being $4.1b higher than the previous year, in part also because of the nearly $9.6b in cash in wage subsidies, resurgence payments and loans paid to companies in the financial year and an estimated 13% increase in profits. So much for the squeezed profit margins companies talk about all the time in business confidence surveys. These figures indicate corporate profits rose by $15b to $71b in the last financial year. That's after companies had to pay extra for wages and input costs. Top-line revenue growth from price increases obviously outpaced input costs, although nearly two-thirds of that top-line growth came from a very friendly source: the Government. A 28% corporate tax rate is one way to get back some of that cash gifted to companies, I suppose.
Inflation is the Government's friend
The end result of the Hoover turning into a Dyson because of fiscal drag and strong nominal GDP growth is that the Budget is powering its way towards a surplus before the election and net debt is sitting at just 17.2% of GDP. That is well below the new 30% net debt ceiling the Government has set for itself and just a fraction of the 60-120% debt levels that New Zealand's AA+-rated peers are laden with. It also illustrates what strong nominal GDP growth (ie inflation plus a bit of real growth) does for the denominator in a debt-to-GDP ratio. It's why Governments of all persuasions love a good burst of inflation. They can use fiscal creep and the diluting effects of fast-rising nominal GDP and negative real interest rates to water down the strength of public debt.
'A balanced approach to buying a third term'
Finance Minister Grant Robertson was preaching a good sermon on Wednesday about fiscal conservatism and taking a 'balanced' view that kept a lid on debt and didn't add much to inflation. He has a multi-decade and probably unending task to rebut the argument that Labour is the 'tax-and-spend' party that is 'addicted to spending' and is 'always blowing out the debt'. That has not been objectively true for 30 years, but these public narratives are hard to turn. The idea that National is the natural party of Government and always better for business is a hard idea to shift. Mere evidence that Labour and National have been just as fiscally conservative (or rightly not during crises) as each other since 1990 is not nearly enough to change voters' minds.
The fact that a Labour Government generated two-thirds of a $15b increase in corporate profits to record highs will not touch the sides. Or that a Labour Government ran Budget deficits of just 1.3% and 2.7% of GDP respectively in two of the most economically dramatic and risky years in our history. Governments elsewhere have racked up deficits of 10%-plus and have happily pushed their net debt to GDP ratios over 100%. Just imagine if you had just had a massive shock to your household's usual income of $100,000 per year and had feared a complete collapse, only to come out the other end of the crisis with a mortgage that rose from $10,500 to $17,200. That's what just happened to the Government's finances. No wonder Mum and Dad are not worried about promising some holiday spending next year.
National Finance spokesperson Nicola Willis will also see room to use the Government's strong finances to try to win the Treasury benches, but through handing back the fruits of fiscal drag to those who have to pay most of it, but also those who need it least.
Robertson, meanwhile, will be dreaming up ways to use that strong position to repeat the magic trick of 2005 when Labour won a third term against the political odds by promising interest-free student loans. That was also a Grant Robertson special when he was an advisor to then-Finance Minister Michael Cullen. There is an even bigger hat for him to pull a rabbit out of next year.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.