By David Skilling*
Farewell wolf warrior diplomacy?
A defining characteristic of Chinese foreign policy under President Xi has been its aggressive ‘wolf warrior diplomacy’. But there have been recent changes. There was a different Chinese tone at October’s G20 meeting in Bali.
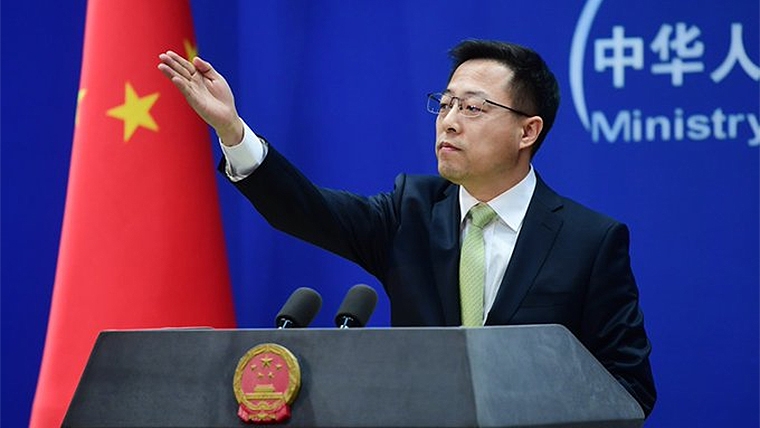
And over the past week or so: lead wolf warrior Zhao Lijian, the MFA spokesman, was moved to a peripheral role – suggesting a change in approach; China’s Ambassador to Australia noted the potential to overcome obstacles in the relationship – including the lifting of sanctions on Australian exports; and the outgoing Chinese Ambassador to the US, and incoming Foreign Minister, said he was ‘deeply impressed’ by the American people. And China is stepping up engagement with Europe.
This may represent course correction, reflecting the need to strengthen the Chinese economy. The previous approach was clearly counter-productive; and China is facing a much more competitive environment. And it may be easier for Mr Xi to do this after the CPC meetings in October.
But the strategic logic behind US/China strategic competition remains intact. On this, I read ‘The Long Game’ by Rush Doshi over Christmas, which makes a persuasive case on the long-term game plan of the CCP. Indeed, China’s behaviour remains unchanged elsewhere: continuing incursions into Taiwan’s ADIZ; and imposing new restrictions on visas for Japanese and South Korea visitors to China.

Commodities make the world go around
Despite headlines about technology breakthroughs, the world still runs on commodities – from energy to food and industrial metals. And recent developments in commodity prices and flows provide a useful gauge of global dynamics and relationships.
Commodity prices have been volatile over the past year, on the Russian invasion of Ukraine and economic uncertainty. But remarkably, the FAO world food price index is now below its pre-invasion levels after spiking higher in 2022; European gas prices have retreated on warm weather, efficiencies, and very high reserves (as I noted last week); and oil prices are roughly where they were a year ago.

But this volatility has left a mark. Commodity exporting countries, such as the Gulf states, have done very well with expanding current account balances – that are now being reinvested. And commodity importers, such as in Europe, have widening current account deficits – and have had to adjust their growth models (with success so far).
And the net zero transition will lead to further changes in the balance of power and trade relations. In general, renewable capacity will strengthen the energy independence of economies. And a new geography of energy flows is emerging. This week, for example, the CEO of Italian energy company Eni was the latest to note the potential for a north-south link connecting Africa’s renewable and hydrocarbon assets with the European market.
Slowing global flows
After a strong Covid recovery, growth in global trade flows is easing. Container shipping data to November shows that international movements are reducing, suggesting some further weakness ahead in world trade flows. Industrial production, which tends to be traded across borders, is also moderating around the world. And export growth from leading Asian economies – from Singapore to Taiwan and South Korea – that tend to lead global trade flows is now in negative territory.
As a consequence of this ‘demand destruction’, measures of global supply chain pressure are reducing. Many indexes of shipping container costs are back below pre-Covid levels. And congestion outside major ports has reduced markedly over the past several months. All of this will contribute to reduced inflation.
Looking forward, the big wildcard is China’s reopening. The removal of Covid restrictions in China may cause some further disruptions to global supply chains, to the extent that Covid-related sickness leads to problems with production and logistics in China (although so far, there is not much evidence for this). But the pent up consumer and industrial demand from China may lead to stronger trade flows and place some pressure on global supply chains and costs. We are already seeing Chinese tourists beginning to move, trade flows may follow.

Peak West and multipolarity
One of the regular themes in my small world notes is the emergence of a multipolar world. And across the West and beyond, we can see fluid, overlapping networks of countries developing.
The US has imposed sweeping restrictions on engagement and technology transfer with China on semiconductors, and is trying to bring key countries along. [For background on semiconductors, I’d recommend ‘Chip War’ by Chris Miller]. The Netherlands and Japan are moving towards the US position; Korea is reluctant to fully commit. But a fully united ‘Western’ response is unlikely because of differing economic interests (see my note on ‘Peak West?’).
More broadly, there is daylight between the US and Europe on a range of strategic economic issues. There is growing European pushback against the US Inflation Reduction Act that includes subsidies and local content requirements around green investment. German Chancellor Scholz was the latest to call for a European version to strengthen the competitiveness of European firms.
‘The US, our partner . . . they call our industry. And they tell them why are you investing in Europe? You should come over to the US. Calling German firms and Belgian firms in a very aggressive way — don’t invest in Europe, we have something better’, Belgium Prime Minister Alexander de Croo
Other groupings are emerging. At their end of year meeting in December, China and Russia agreed to work together to ‘actively advance BRICS membership expansion’ beyond Brazil, Russia, India, China, and South Africa. Saudi Arabia, Turkey, and Egypt are reportedly engaged in the membership process. Although not a fully coherent grouping, note that these countries abstained or voted against UN resolutions to condemn Russa.
Elsewhere, the Middle East/China energy relationship is developing. And Africa is being courted. The new Chinese Foreign Minister’s first trip this week was to five African countries; and US Treasury Secretary Janet Yellen is visiting South Africa, Zambia and Senegal next week.

Japan
Japan Prime Minister Fumio Kishida has been on the road this week, as well as other Japanese Ministers, across G7 capitals as part of preparations for hosting G7 meetings this year. Key announcements have included: a major defence agreement with the UK (note also Japan’s recent deal with the UK and Italy to jointly develop advanced fighter aircraft); enhanced cooperation with France; and strengthened military relations with the US. He is Washington today to meet with President Biden.
This is the latest chapter in Japan’s emergence as an active part of the security architecture across the Indo-Pacific: from membership of the Quad, to strengthened security relations with the US and Australia and others, and constitutional changes to allow it to take a more forceful military posture. It has taken a tough approach on Russia’s invasion of Ukraine; as well as on Taiwan.
‘Japan is stepping up big time and doing so in lock step with the United States, partners in the Indo-Pacific, and in Europe’, Jake Sullivan (US National Security Advisor)
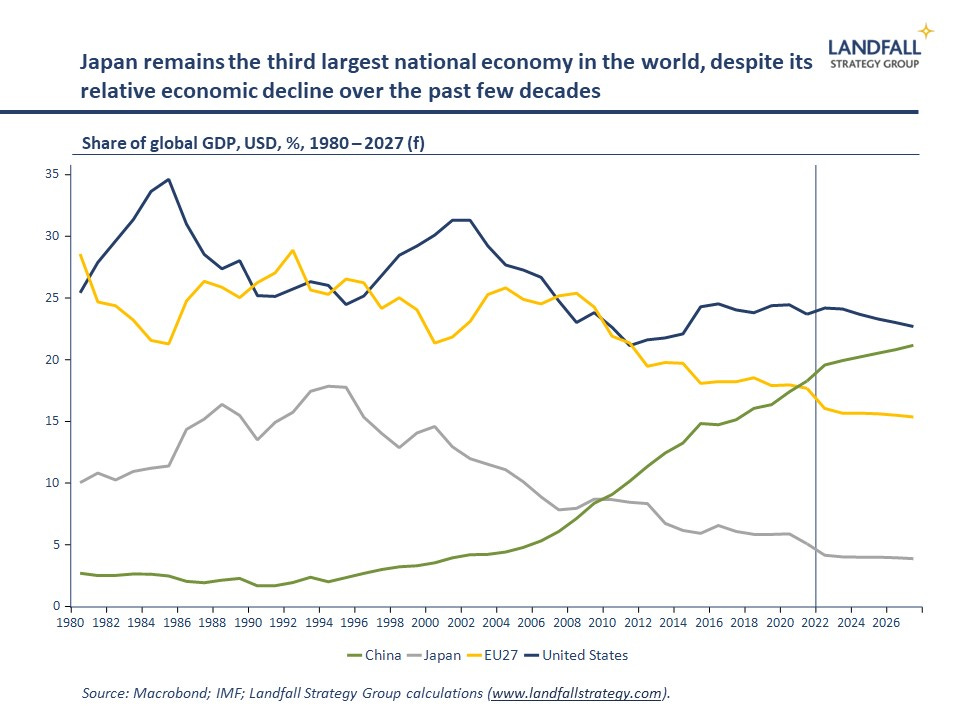
More broadly, Japan was instrumental in keeping the TPP alive after the US walked away. And it is part of all the major economic groupings in Asia (from RCEP to IPEF). Despite an aging population and weak headline GDP growth over the past few decades, Japan remains the 3rd largest national economy in the world – with leading technology positions in areas from robotics to semiconductors and hydrogen. Keep an eye on Japan as an increasingly indispensable country in the Indo-Pacific.
*David Skilling ((@dskilling) is director at economic advisory firm Landfall Strategy Group. The original is here. You can subscribe to receive David Skilling’s notes by email here.
**Get in touch (by reply email or at contact@landfallstrategy.com) if you would like to access the full paper referred to in the article above.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.