By Martien Lubberink*
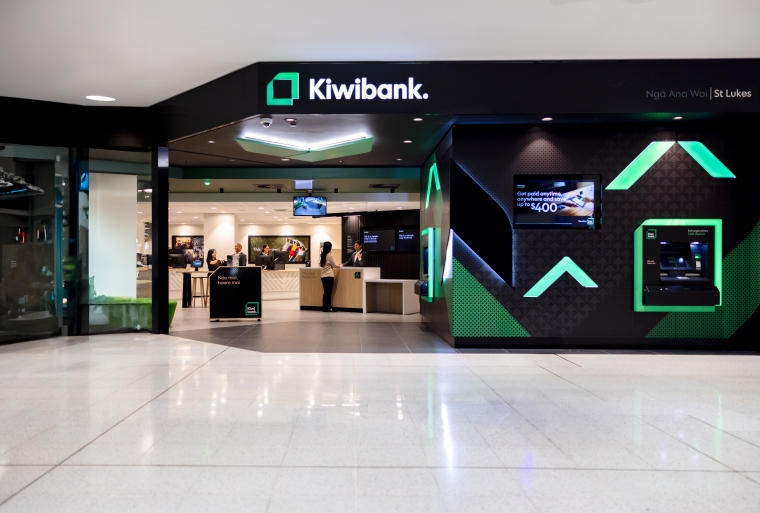
The New Zealand government is proposing a $500 million capital raise for state-owned Kiwibank to boost its competitiveness against the dominant Australian-owned banks. The funds will be sourced from KiwiSaver funds, local investors, and New Zealand-based institutions.
Finance Minister Nicola Willis highlighted that this capital injection would support Kiwibank’s growth, enabling up to $4 billion in new business lending or $10 billion in home lending. This, in turn, could enhance competition and potentially lower interest rates for all bank customers.
In the longer term, the government envisions a public share offering once Kiwibank completes its digital transformation, expected by 2028. If an IPO doesn’t proceed, investors could have the option to sell shares back to the Crown at a fair value. This move follows recommendations from the Commerce Commission to better capitalize Kiwibank to increase competition in the banking sector. The proposal also aligns with broader regulatory reviews aimed at creating a fairer banking environment.
The haunted bank
After a $225 million capital injection last year, the New Zealand government is once again looking to pump money into Kiwibank. However, the results of that injection have been far from promising. Kiwibank remains one of the weakest players in the market. Its capital ratio has stagnated since 2018, leaving it with the lowest core capital ratio among New Zealand banks. Its profitability is also among the lowest in the sector, making it hard to believe that more capital injections will solve its problems. And yet, the bank's CEO, Steve Jurkovich, continues to ask for funding of the kind without strings attached, without much to show for past efforts. Watch his Q&A interview for a sense of his brave approach.
Today’s announcement raises several concerns.
First, Kiwibank is financially weak. Its profits are too low to cover the cost of capital, and its capital ratios have shrunk over time, while the Reserve Bank (RBNZ) wants these ratios to increase under the 2019 capital rules. The bank is busy updating its systems and software, but such projects are not risk-free. The weak position of Kiwibank and its exposure to multiple sources of operational risks gives investors leverage in any price negotiations and signals that the bank is not yet in a position to challenge the larger players in the market.
Second, the outlook for Kiwibank remains bleak. Even with another capital injection, it is unlikely that the bank will be in much stronger shape in two to three years. In fact, it is much more likely that Kiwibank will face multiple rounds of capital raising, much like Italy’s Monte dei Paschi di Siena, which required several bailouts over the years.
Third, the government's 'put option' is problematic. If an IPO does not happen, the government has promised to buy back the shares at a fair value, but institutional investors are likely to have a say in determining that value before they commit. The fair value is likely higher than the true market value at the future redemption date.
Finally, the government’s role as a guarantor opens a dangerous can of worms. During the global financial crisis, regulators learnt the hard way that such guarantees are risky because, in times of crisis, the government may not be willing or able to repay investors. Or, the expectation of a compensation may haunt the government (or the bank) for years. That is why, under Basel III capital rules, these types of guarantee disqualify such shares from counting as capital. See criterion 12 of Common Equity Tier 1 in the Basel Rules book:
"The paid in amount is neither secured nor covered by a guarantee of the issuer or related entity, or subject to any other arrangement that legally or economically enhances the seniority of the claim."
The RBNZ has not fully implemented Basel III, but has its own definition of what qualifies as capital. According to RBNZ rules, Common Equity Tier 1 (CET1) capital must
- a. provide a permanent and unrestricted commitment of funds; and
- b. be freely available to absorb losses; and
- c. not impose any unavoidable servicing charge against earnings.
An exercise in futility?
With the government’s put option, the shares would probably not meet the first two criteria. The government’s commitment to buying back shares makes them dated (non-permanent). It is unclear whether these shares would truly absorb losses in practice, especially given the arrangements between the government, Kiwibank, and investors. In short, while the shares may technically absorb losses, in reality, any losses could linger for years, haunting both Kiwibank and the government, in particular Finance Minister Nicola Willis. If the shares do not meet the RBNZ's capital definition, this entire initiative will be an exercise in futility — failing to get Kiwibank back on track.
So, while the government’s plan may seem like a quick fix, it is fraught with potential pitfalls. Don't say that I didn't warn them.
*Martien Lubberink is an Associate Professor in the School of Accounting and Commercial Law at Victoria University. He has worked the the central bank of the Netherlands where he contributed to the development of new regulatory capital standards and regulatory capital disclosure standards for banks worldwide and for banks in Europe (Basel III and CRD IV respectively).
This article first ran here and is used with permission.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.