
When the data is released for June 2025, we will find that two thirds of all bank lending is for housing.
While that may not be 'news' for regular readers, it will be an important milestone.
The core data is revealed in the RBNZ's Dashboard. When that series started, it was 58%, so that share has risen since 2018 by eight percentage points. And in a industry loan book of $556 bln (total bank lending), every 1% is $5.5 bln of additional mortgage lending. As at March 2025 it totaled $368 bln. And given that on June 19, Stats NZ will release Q1-2025 GDP data, that probably means it is equivalent to more than 85% of nominal GDP.
Housing and housing lending dominates our economy - still, even after capital gains have evaporated in the sector.
In the seven plus years that the Dashboard data has been available, it is the largest banks who have driven this shift.
Share of each bank's mortgage lending of all its lending
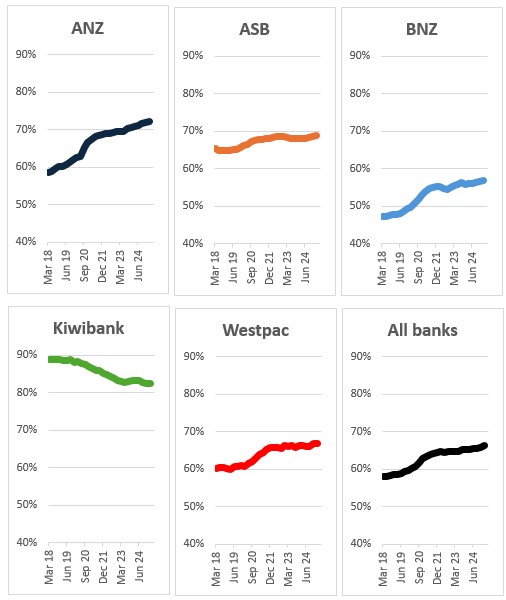
ANZ has led the way, twisting its lending share into housing from 59% of all its loans to 72%, a 13 percentage point shift.
ASB, which started out higher, has been more restrained, but going from a high 65% to an even higher 69%.
BNZ, which saw itself underweight in housing loan exposures at just 47% in 2018, has added ten percentage points to 57%. It is still the smallest concentration of any retail bank.
Westpac has gone from 60% to 67% over that same period.
Kiwibank, which started life exclusively lending for mortgages still has an outsized twist to housing but has managed to reduce its concentration from a sky-high 89% to 83%, still far more than the mortgage market leader ANZ's 72%.
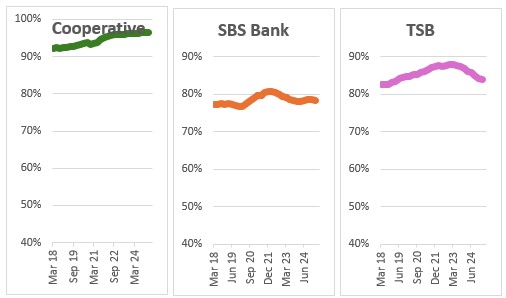
Among the key retail challenger banks, the Cooperative Bank is all in on mortgage lending, SBS Bank has been stable and high, and TSB has a higher level but has managed to wean itself off the March 2021 giddy heights.
Of course, the inverse is true too, the other side of lending for personal loans, business loans and rural lending are all at record low shares.
Share of all bank non-mortgage lending of all its lending
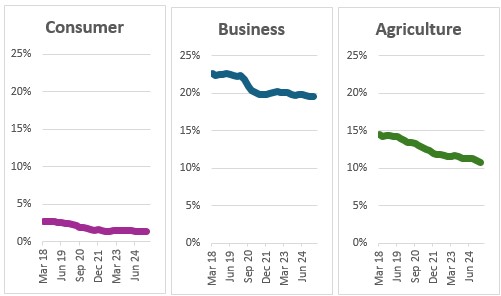
That may not be a bad thing, per se. But the consumer loan business has a heavy influence of non-bank lenders and the bank share doesn't really reflect that sector's activities - except to show banks aren't that interested mainly because it can never move their profit needle.
Bank lending for business and corporates is also only a part of company borrowing. Big licks of debt funding is raised in the corporate bond market. The NZX lists $25.6 bln in corporate debt (excluding central and local government debt and bank det issues, but including SOEs). There is also unlisted debt.
Lending to the rural sector has a number of non-bank institutions active as well, and recent strong cashflows in the dairy sector encourages paydown of loans. Rabobank's active specialist engagement has tended to limit the main banks, as do the widely shifting risk profiles of borrowers.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.