
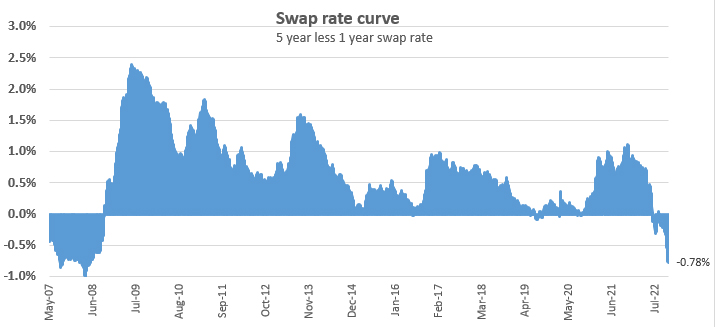
In July, 5 year wholesale swap rates slipped below the one year rate. And they stayed below for the next three months. Not by much, but the inversion was recorded.
However in the past week or so, that inversion has grown, and quickly.
It is now its largest since before the GFC. Back then it ballooned out to a full -1%.
No one knows what it will do this time, but it is entirely possible it could sink to a new record.
That is because the global influences are strong. The local influences are at the short end and are tending to hold rates high. But globally, markets are suddenly pushing rates sharply lower. And that is powering the current wholesale inversion.
An inverted interest rate curve shows that long-term interest rates are less than short-term interest rates. With an inverted yield curve, the yield decreases the further away the maturity date is. Sometimes referred to as a negative yield curve, the inverted curve has proven in the past to be a reliable indicator of a recession.
Hindsight showed that this was certainly true in 2008. A recession lingered for five years or so for most of the world, even if New Zealand got off relatively lightly.
Back in April 2007 well before the collapse of Lehman Brothers and the start of the sharp GFC reactions, the average one year bank fixed rates were 8.80% and the five year rates were 8.55%, so rates were inverted -30 bps. A year later, also also before Lehman Brothers but after some American mortgage banks started to waver and roll over, local one year rates were 9.85% and five year rates were 9.45%, and a -40 bps inversion at retail.
For reference, the OCR in April 2007 was 7.75%, and in April 2008 it was 8.25%. Allan Bollard was the RBNZ Governor at the time.
Of course there is no way of knowing what will actually happen this time. But it would not be surprising to see the inversion deepen on wholesale markets, and well beyond -100 bps. If that did happen, an equivalent shift in retail mortgage rates is a possibility too. One and two year rates might move up a little as the OCR rises. But 3, 4 and 5 year fixed rates might well fall from here, creating a real retail inversion. We are not predicting that, but it is more possible now that at any time over the past 12 years.
But will that also mean we are facing a recession? (Yes, I know, DGMs think we are already in one.) This is a less certain outcome and a lot depends on the labour markets. Unlike 2008-2014, our present labour markets are strong. Participation rates are unusually high. Jobless rates are unusually low. And pay rates are rising quite quickly now. Vacancies are widespread. This is a very different situation now than previously. Of course, we all know that the RBNZ is working to take these pressures out of the economy to quell demand and therefore the inflationary impulse and inflationary expectations. They know inflation won't be beaten without these things happening.
Inflation makes debt easier to repay. It also 'helps' Government finances with higher tax collections and bracket-creep.
If the RBNZ succeeds, then a downshifting economy may bring economic conditions like we saw in 2008-2014, which weren't great.
But it is not all up to the RBNZ. There is an election in 2023, and promises and policy levers will be working overtime to avoid an economic downturn.
Overseas, economies will have a large part to play in the general economic direction too. A healthy US and a healthy Australia will insulate us from too much pain and make the RBNZ's task harder. A reoriented China may spark a global upturn, building on the US, Japan and Australian situations.
But the reverse is just as likely. It has been almost a decade since the last 'real' recession (not counting the pandemic slowdown). The world is due.
And a recession will then likely bring sharply lower interest rates - and more normal rate curves.
There's more to life than interest rate curves. For a fuller discussion about what 2023 will bring, David Hargreaves has a savvy review here. And here.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.