
Here's our summary of key economic events overnight that affect New Zealand with news the road is getting very rocky as we transition to inflation-fighting mode.
The financial markets are re-rating equity prices following the clear signals that the Fed efforts to lean heavier against inflationary forces is gathering steam. Not only will equity p/e ratios fall, but there is likely to be considerable collateral damage in less developed nations as the inflationary fight builds. The US dollar is rising quickly, and the Chinese yuan has dived to a one-year low overnight, and its been a painful week for Chinese stocks (see below).
But the US factory sector is expanding faster, even as concerns about the future build. Their manufacturing PMIs came in at their strongest in 7 months due to faster rises in output, new orders and employment. A rise in export orders is coming too. Inflationary pressures remained high but firms are managing to pass on all of that effect to customers. But all this isn't really improving sentiment as inflation and geopolitical uncertainty make it hard to be optimistic even if the present situation is improving. Those sentiment concerns weigh heavier on their services sector, but that too is expanding well still.
Canadian retail sales were expected to slip in February, but they rose in data released overnight, even if only marginally. They would have risen much more except vehicle sales were weak there.
Canadian producer prices rose very sharply in March, now running higher than +18% pa. In fact that is their fastest pace in almost 50 years.
Japan finally seems to be getting some [minor] inflation. Consumer prices rose by +1.2% in March, the most since October 2018, after a +0.9% gain a month earlier. The latest figure marked the 7th straight month of annual inflation, with food prices rising at the fastest pace in over 5 years at +3.4%.
And the flash April PMI for Japan brought signs their economy is expanding this month. The latest data showed that Japanese private sector activity improved at a sharper rate. Services companies recorded an expansion in activity for the first time since last December, while manufacturers saw output levels rise for the second successive month. April data signaled the sharpest expansion in four months, though the pace of growth was only marginal, to be fair, mainly because new order levels weren't growing. But it is better than a contraction.
However, EU growth is accelerating in April as reviving services demand offsets a near stalling in their manufacturing sector. But prices are rising at record rates. In Germany, a drop in manufacturing production contrasts with continued service sector growth. But in France, business activity is rising at its fastest pace in more than three years. The UK however is still recording an expansion, but at lower levels. British retail sales were particularly weak in March, recording a decline.
In Australia, Westpac's respected economist Bill Evans has noted that 'underlying' inflation will rise to 3.4% when the March data is released next week, and their jobless rate will fall below 4% in April, and "on the basis of those forecasts we expect the RBA will decide to lift the cash rate by 40 basis points at its Board meeting on June 7" to 0.5%.
Australia's businesses are still expanding at healthy levels. Their private sector recorded a third straight month of growth, according to flash PMI data. Both output and demand expanded at strong rates in April, leading to the continued expansion of workforce capacity. Supply constraints persisted, however, contributing to record input cost inflation while backlogged work also rose solidly.
And we should note that prices for corn have hit their highest price in a decade, and could easily surge to a new all-time record soon. This will exacerbate the world food crisis.
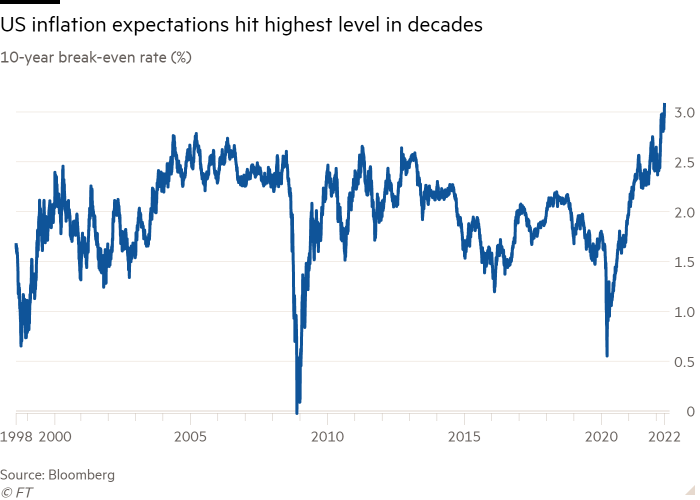
The UST 10yr yield starts today lower by -2 bps bps at 2.90% and taking the weekly rise to +7 bps. The UST 2-10 rate curve is flatter at +19 bps. Their 1-5 curve is flatter too at +89 bps. Their 30 day-10yr curve is also flatter at +244 bps. The Australian ten year bond is now at 3.11% and up +5 bps. The China Govt ten year bond is up +1 bp at 2.89%. And the New Zealand Govt ten year up +8 bps at 3.60% and that is a +17 bps rise in a week.
On Wall Street, the S&P500 ending its Friday session down -2.3% as prospects of an aggressive monetary policy tightening seems to have spooked investors. For the week they are heading for a -2.3% loss. Overnight, it was similar red ink in all European markets, But both Paris and Frankfurt ended with small +0.4% weekly gains, London with a weekly -0.8% retreat. Yesterday Tokyo ended its Friday session down -1.6% but that locked in a net +1.0% gain for the week. Hong Kong was down -0.2% capping a week where they lost a massive -3.8%. Shanghai eked out a small +0.2% gain on Friday, but that still left them with a -3.1% loss for the week. The ASX200 ended down -1.6% to end the week flat. The NZX50 closed down -0.4% on the day but closed out the week up a net +0.3%.
The price of gold starts today down -US$14 since this time yesterday at US$1933/oz. That is a -US$44 fall for the week however.
And oil prices are -US$1.50 lower at just under US$101.50/bbl in the US while the international Brent price is now just over US$105.50/bbl.
The Kiwi dollar will open today down more than -1c at 66.3 USc taking it to its lowest since mid-February. Against the Australian dollar we are marginally firmer at 91.6 AUc. But against the euro we are more than -¾c weaker at 61.4 euro cents. That all means our TWI-5 starts today at 72.8 and another -70 bps lower. The devaluation so far this month has been -2.6%, but in the longer scheme of things it is only back to its ten year average.
The bitcoin price has dropped -5.4% from this time yesterday to US$39,415. Volatility over the past 24 hours has been high at just under +/- 3.0%.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.