
Here's our summary of key economic events overnight that affect New Zealand, with news international travel may be back on the agenda for many, but it is likely to cost a lot more post-pandemic.
But first, US jobless claims came in virtually unchanged last week from the week before. That remains a low level. There are now 1.916 mln people on these benefits. Still this leading indicator isn't yet showing labour market stress rising.
But those monitoring major layoffs are finding more now. US-based employers announced 102,943 cuts in January, and far higher than the 19,100 cuts in January 2022. As spectacular as these changes are, you need to keep in mind the US workforce is 156 mln, so this new level is just 0.07% of that.
American labour productivity rose in the December quarter and labour costs rose at a much slower pace than anticipated, only at a +4% annual rate. Financial markets kicked along on this news.
And US factory orders bounced back to growth in December from their big and unexpected November fall, but not by as much as expected.
Going the other way, Canadian building consents fell more than expected in December after an unexpectedly large rise in November.
In what might be seen as an act of desperation as Beijing's grip on Hong Kong tightens and confidence leaks away, the city's governor is giving away 500,000 free airline tickets to try and entice visitors back in 2023.
As expected, the ECB raised it policy rate by +50 bps to 3.0% during its February meeting, its highest level since late 2008 and indicating to will deliver another +50 bps rate hike at its meeting in March.
And in a mirror decision as expected, the Bank of England raised their rate by the same +50 bps, taking their policy rate to 4.0%.
In Australia, their building consent levels rebounded very strongly in December ending a period where they languished. Bouncing back most strongly were approvals for new apartments, surging by more than +50%. However, despite this December jump, Q4-2022 consent levels are still lower than Q4-2021.
The IMF has been reviewing Australia, and its report says specifically: "The capital gains tax exemption for the sale of main residences, costing around 2½ percent of GDP annually in foregone revenues, should be restricted." (See page 14.)
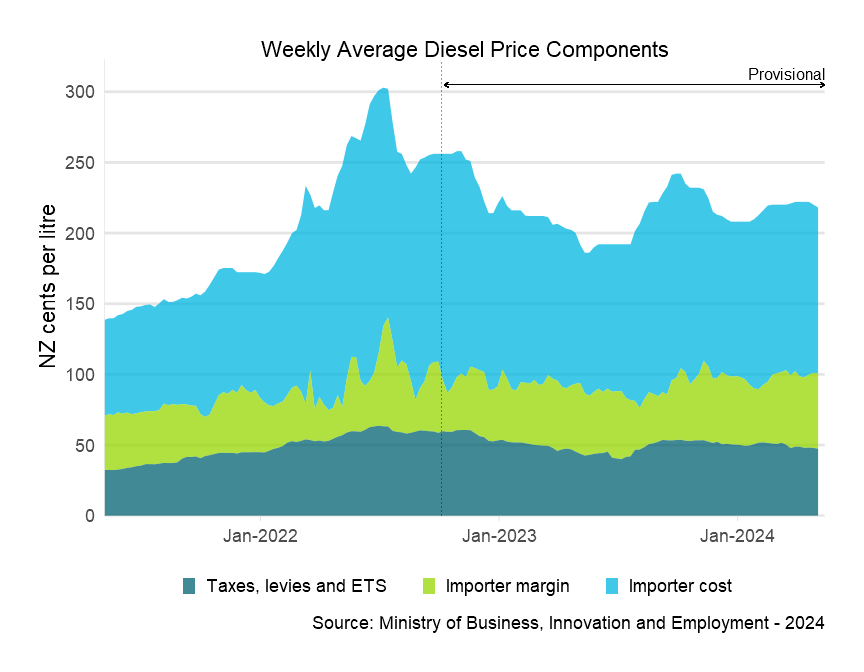
A commodity we don't watch much is the cost of aircraft jet fuel. But it is in shortish supply, made worse by a sudden shift higher for air travel demand, which started in the US and is expected to grow rapidly in Asia now. We are talking +20% to +60% year-on-year rises. Just in the past few weeks the cost of this fuel has risen +11% since the start of 2023. It is hard to see it reverting back any time soon.
One commodity we do watch regularly is container shipping rates and they were unchanged last week. Bulk cargo rates seem to have stopped falling, bottoming out at a low level.
The UST 10yr yield starts today at 3.38%, and down another -8 bps from this time yesterday. That has added up to a -15 bps retreat in a week, most in the past two days since the Fed decisions. The UST 2-10 rate curve is slightly less inverted at -70 bps. And their 1-5 curve is more inverted at -118 bps. Their 30 day-10yr curve is more inverted at -114 bps. The Australian ten year bond is down another -14 bps at 3.40% and a big shift lower. The China Govt ten year bond is down -2 bps at 2.93%. And the New Zealand Govt ten year is starting today at 4.10% and -11 bps lower.
Wall Street has opened it Thursday session with a +1.5% rise on both good earnings reports and encouragement the Fed is nearing the end of its hiking phase. The tech sector is doing especially well. Overnight, European markets all rose led by Frankfurt's +2.2% and trailed by London's +0.7%. Yesterday, Tokyo ended its Thursday session up a minor +0.2%. Hong Kong fell -0.5% on the day. Shanghai ended little-changed. The ASX200 ended up barely, up +0.1% yesterday while the NZX50 ended with a better +0.5% gain.
The price of gold will open today at US$1916/oz and down -US$8 from this time yesterday.
And oil prices start today with little net change at just under US$77/bbl in the US. The international Brent price is now just under US$83/bbl.
The Kiwi dollar is firm at 64.9 USc and up +½c. Against the Australian dollar we start today back up +½c too at 91.6 AUc. Against the euro we are back up +½c too at 59.5 euro cents. That all means our TWI-5 starts today at 71.4 and up +50 bps from yesterday and back to where we were this time last week.
The bitcoin price is now at US$23,817 and up a strong +3.6% from this time yesterday. Volatility over the past 24 hours has been high too at +/- 3.2%.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.