
Here's our summary of key economic events over the weekend that affect New Zealand, with news questions are deepening about the Chinese economy, and how it will extract itself from the on-going funk - or whether it can.
But first, we are now in the heart of the northern hemisphere annual vacation season. Anything happening now is reactive to the general inactivity among investors, company managers, and regulators.
The week ahead will be somewhat light for key data releases, probably the most important one being US factory orders for July. And at the end of the week, the Powell speech at the central banker shindig at Jackson Hole, WO, will be closely watched. Locally, July retail sales levels will feature (via the electronic cards version), and in Australia there is little of substance on the agenda.
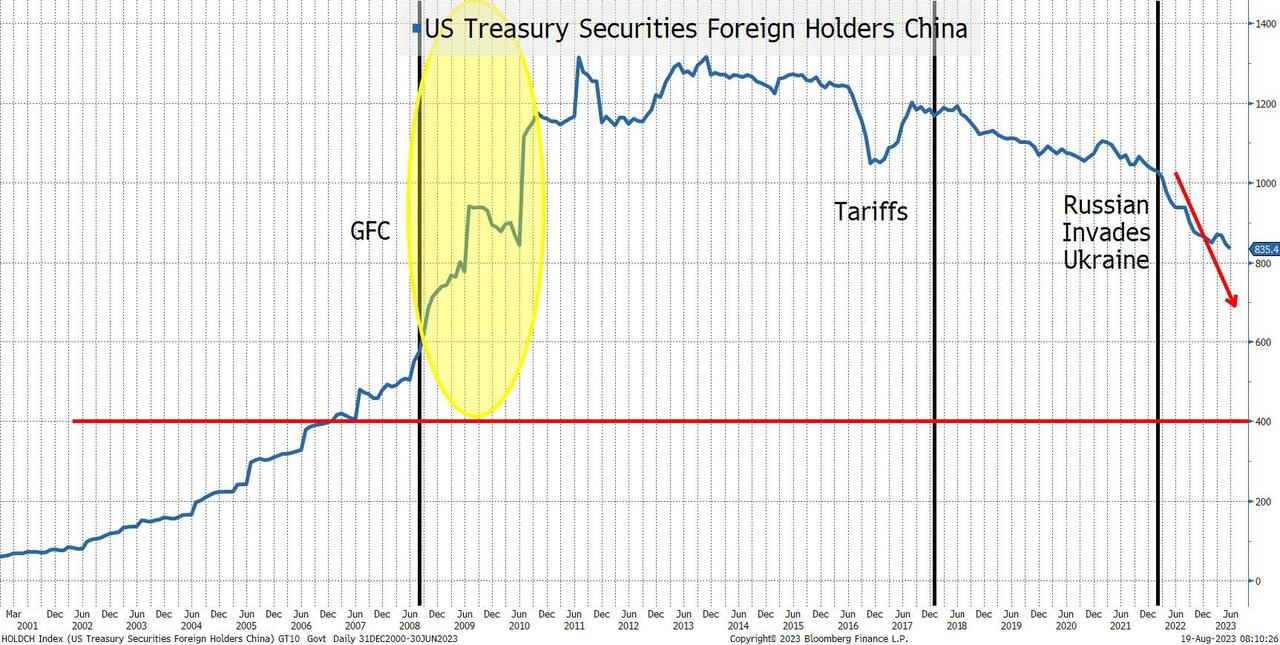
In China, they released foreign direct investment data and that remained modest in July with the main inflows coming from 'friends'. Western companies are now moving to the exits. And their central bank moves to keep the yuan value elevated for wider stability reasons means those leaving now are not getting hurt by the exchange rate
Meanwhile, China's Evergrande Group, once the country's second-largest property developer (Country Garden is now the largest), filed for bankruptcy in New York on Friday (NZT). It was a Chapter 15 bankruptcy filing meaning its actually a Chinese (Hong Kong) bankruptcy, a move that protects its US assets from creditors while it works on a restructuring deal elsewhere. Rival Country Garden is going down the same 'restructuring' path. In fact, Country Garden is to be cut from the Hong Kong Hang Seng index now.
And it is not only property developers reporting huge and widening losses. Chinese carmakers are too. Cutbacks are widespread among companies and across all demographics. Anxiety levels are rising.
Over the weekend it was reported that at least five local governments will be allowed to sell ¥1½ tln (NZ$350 bln) in bonds - to repay earlier debt from local shadow financing.
Later today, China will review its prime loan interest rates. No-one seems to be sure whether they will cut them or not, but a cut seems likely. More analysts are asking whether China's 40-year development boom is over - and what that means for investors. Ratings agency Fitch is nervous. They have had China's sovereign rating at A+ (Stable) for more than 15 year, but is now signaling that conditions are changing to the downside as they see it. The Fitch downgrade of the US sovereign rating (to AA+ earlier this month from AAA) has triggered a widespread reassessment of international yields. A China downgrade won't be seen positively either. (S&P is also at A+ Stable for China, and Moody's is at A1 Stable. Both have been at these levels for six years. For comparison, both S&P and Fitch have New Zealand at AA+, Moody's at Aaa.)
In Japan, CPI inflation rate was unchanged at +3.3% in July but this was notably higher than market expectations of +2.5%. Core inflation stayed above 3% too. Prices continued to rise for food which was up +8.8% in July from a year ago, compared with +8.4% in June. The latest figures are well above the Bank of Japan's 2% target, and for the 16th consecutive month.
In Canada, producer prices rose +0.4% in July from June, a big shift from the -0.6% decline in the previous month. This was their first rise of producer prices since October 2022. Year-on-year Canadian PPI is down -2.7%.
In Australia, their pipeline of investment projects has climbed to a new record high in 2023. The value of projects in the investment pipeline was worth AU$946 bln in the June quarter 2023, a +AU$180 bln (+22%) increase on the level prior to the pandemic.
The UST 10yr yield will start today at 4.25%, unchanged from Saturday but +9 bps higher than week-ago levels. Their key 2-10 yield curve inversion is still at -69 bps. Their 1-5 curve is unchanged at -97 bps. Their 3 mth-10yr curve is still at -113 bps. The Australian 10 year bond yield is now at 4.23% and unchanged from Saturday. The China 10 year bond rate is holding at 2.58% and its lowest since the temporary drop at the start of the pandemic in early 2020. Apart from that it is a 20 year low. And the NZ Government 10 year bond rate is down -1 bp, now at 5.08%. A week ago it was 4.90%.
The price of gold will start today at US$1890/oz and little-changed from Saturday. But it is down -US$12 from a week ago.
And oil prices are holding at just over US$80.50/bbl in the US. The international Brent price is now just over US$84.50/bbl. These levels are a net -US$2 lower than week ago levels.
The Kiwi dollar starts today slightly softish at just on 59.2 USc. Against the Aussie we are little-changed at 92.6 AUc. Against the euro we are marginally softer at 54.5 euro cents. That all means the TWI-5 is at 68.4 and down a mere -10 bps from Saturday and the same over the past week.
The bitcoin price is a little lower again today and now at US$26,127 and down -0.5% from Saturday. But for the week it is down more than -10%. Volatility over the past 24 hours has been very low at just on +/- 0.4%.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.