Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
No changes to note today. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
None here either. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
SEPTEMBER WAS A TOUGH OLD MONTH
The REINZ PR department has gone full-spin with their September housing market report, headlining 'activity is continuing' and ignoring the retreats. In fact these latest REINZ figures show a -12% annual drop in September house sales, while stock levels rose. +11%. The ANZ economists nailed it - "Another down notch".
LEAVING BUT NOT RETURNING
The number of departing NZ citizens was steady in August at just under 65,000 for the year in the latest migration data. The net population gain from migration more than doubled in August year to 20,500, but number of returning NZ citizens remains low by historical standards.
WHOEVER WINS WILL HAVE A TOUGH RECOVERY JOB
The NZIER says a challenging economic environment will face the next Government, with fiscal choices constrained by both the inflation outlook and the Government’s deteriorating fiscal position. Greater policy certainty and well-targeted investment remain important for lifting productivity and long-term growth, they say.
BACK WHERE WE WERE SEVEN YEARS AGO
After achieving pre-pandemic levels in July, inbound tourism almost did so again in August. Most international visitors are arriving in Auckland, but Queenstown has the stellar growth story for inbound tourism. China continues to lead growth in visitor arrivals, overtaking Australia as a growth driver in August. Chinese arrivals grew +32% in August, accounting for 35% of total visitor arrival growth. Australian arrivals rose +4.9%, accounting for 32% of total growth.
ELECTION UNCERTAINTY 'NOT A HANDBRAKE'
New analysis from ASB economists challenges the widely held view that Kiwi businesses and households put financial decisions on hold in an election year. While confidence does weaken pre-election, business and household activity tends to be more resilient, this ASB research finds.
PRICES RISE IN BOTH USD & NZD
The overnight Pulse dairy auction was a positive one with WMP and butter up more than +2% from the prior week's full auction event, and SMP continuing its rise, up +1%. Prices in NZD were up slightly more.
NZX50 SOFT
As at 3pm, the overall NZX50 index is down -0.3% today. From a week ago it is up +0.2%; from six months ago it is up +5.3%. From a year ago it is up +3.3% now. Market heavyweight F&P Healthcare is down less than -0.1% so far today. There are gains for Vector, The NZX, Investore and Stride while Oceania, Serko, Infratil and Vista Group lead the decliners.
FLETCHER BUILDING’S RESIDENTIAL BUSINESS REMAINS ‘CHALLENGING'
Fletcher Building says the number of Residential + Apartment units taken to profit in the first quarter of its 2027 financial year came to 54, down 75.5% from the previous quarter (Q4 FY26). The Residential & Development business remained “challenging”, consistent with broader market conditions, particularly in the Auckland market. Inflation and interest rate uncertainty are impacting the timing and commencement of new commercial and residential projects, according to Fletcher. The construction management company expects the Residential & Development Division to make a minimal contribution toward Fletcher’s half-year earnings, set to be released in February 2027. However, Fletcher says its other core businesses delivered a “solid start” to the 2027 financial year, with first-quarter sales volumes ahead of the prior corresponding period in most business units.
MERCURY’S Q1 TRADING MARGIN UP TO $445 MLN
In a Q1 update, Mercury Energy says the energy generator-retailer (gentailer) delivered a strong first quarter in the three months ended September 2026, with a trading margin of $445 mln. This was up 19% or $70 mln on the previous corresponding period in 2025, despite Waikato hydro inflows being at the second percentile (very low). New wind and geothermal generation were up 307 Gigawatt-hours (GWh); however, this was offset by lower hydro volumes, which decreased by 332GWh or 24%. Mercury says that, based on the company’s current outlook, it remains on track to deliver its FY27 earnings guidance of $1.07 bln.
PAYING MORE
The Government is paying Channel Infrastructure to extend the agreement for the 550,000-barrel strategic diesel reserve until August 2027 to maintain our fuel resilience. This is on top of them subsidising the infrastructure at Marsden Point to the tune of $21.6 mln out of the Regional Infrastructure slush fund.
SETTLEMENT ACCOUNTS
Our banks had $28.5 bln parked in institution settlement accounts at the RBNZ (earning the OCR rate), the most they have had there in 2026, although less than the $30.7 bln they had there in September 2025. (And recall, there are now more than banks who can have these accounts.) $28.5 bln at 2.75% generates interest earnings for these institutions of $780 mln per year - or a cost to the RBNZ of the same. Also, the government has $25.6 bln parked in their settlement account at the RBNZ.
A RED FLAG FROM FITCH
Ratings agency Fitch is pointing out that higher bond yields in almost every developed economy will mean a rise in government interest expenditure and wider budget deficits as debt matures and is refinanced at prevailing market rates. Fitch estimates that the median 10-year bond yield is +161 bps above the current average effective interest rate on debt stocks, although the impact of the bond market shock will take time to feed through to average borrowing costs due to the generally long maturity of government debt. Fitch forecasts that developed general government debt will rise to 102% of GDP by the end of 2026, up sharply from the 68% of GDP 20 years ago. This has eliminated any wiggle room, so substantial retrenchment of primary budget balances (before interest payments) will be needed to stabilise debt ratios in many countries. But they know that strong secular expenditure demands and political constraints will make it difficult to implement fiscal consolidation. Without it however, things will get "interesting". Just look at France.
SWAP RATES HOLD AGAIN
Wholesale swap rates will likely be unchanged to marginally firmer today. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was up +1 bp at 3.23% on Tuesday. Today, the Australian 10 year bond yield is up +3 bps at 5.33%. The China 10 year bond rate is now at 1.65% and down another -1 bp. The Japanese 10 year bond is now at 3.01% and up +2 bps. The NZ Government 10 year bond rate is now at 5.02% and unchanged from yesterday. (The RBNZ 10 year rate is 'prior day' and was down another -4 bps at 4.98% on Tuesday.) And the UST 10yr yield is now at 5.22% and up +3 bps from yesterday at this time.
EQUITIES MOSTLY SOFTER
The NZX50 has softened slightly, now down -0.2%. The ASX200 has opened down a full -1.0%. Tokyo is up +0.3%. The KOSPI has recovered +1.2% after yesterday's very large drop. Hong Kong is down -0.2% in Wednesday trade while Shanghai up +0.1%. Singapore is unchanged in early Wednesday trade. Wall Street closed slightly lower, down less than -0.1% on the S&P500, down -0.2% on the Nasdaq.
OIL UP AGAIN
American oil prices have risen another +US$2.50 from yesterday with the WTI benchmark now at just over US$95/bbl, while the international Brent price is just under US$107/bbl and up +US$2.
CARBON PRICE HOLDS LOWER
There have a few trades and slightly larger ones and the price has firmed +50c to $50.50/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD HOLDS
In early Asian trade, gold has held, down just -US$3/oz from yesterday, now at US$4163/oz. Silver is down another -US$1 however at US$59/oz.
NZD FIRMS
The Kiwi dollar is up +40 bps at just under 56.3 USc from where we were yesterday. Against the Aussie we are up +10 bps at just over 80.4 AUc. Against the euro we are up +20 bps at 50.2 euro cents. This all means the TWI-5 is is now just on 60 and up +30 bps.
BITCOIN MARGINALLY FIRMER
The bitcoin price is now at US$83,319 and up +1.1% from yesterday at this time. Volatility has been modest at just over +/- 1.0%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
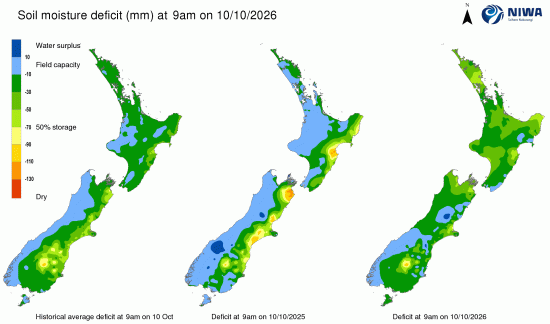
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.