
Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
TSB has reduced its 1 year fixed rate to 4.99%, now matching most of its larger rivals. Meanwhile, UnityMoney raised its 2 year rate to 5.49%. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
No updates to report here today. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
"THE OCR IS GOING UP"
Financial market pricing has a +25 bps OCR hike almost fully priced in for October 28. Major analysts have also come to the view that the RBNZ will need to act decisively because inflation is clearly on the rise again - despite what Thursday's Q3 CPI data will show. BNZ thinks an October OCR hike will need to be followed up with the RBNZ talking about more again.
THE SERVICE SECTOR SAGS
Although manufacturing activity expanded at a 'notably stronger rate' in September, the latest Performance of Services Index shows services sector growth has slowed as businesses shift into a 'wait and see' mode ahead of the election. It is now in a neither expanding for contracting state. New orders are up in the services sector, which is good. But inventories are also up, so if the new orders are just filling inventories, it won't last.
WE CAN'T AFFORD THE IMPORTS WE ARE BUYING
The impressive +12.3% rise in September exports over year-ago levels has been more than overshadowed by the +17.7% rise in imports - of course caused by the +95% rise in fuel imports. In fact, fuel imports have jumped to be the single largest product we import. That has meant that the goods trade deficit came in at almost -$2 bln in September, up sharply from the -$1.6 bln last year. The combined trade deficit for the three months July-to-September is now a painful -$5.6 bln, +10.6% more than in the longer July-to-October period in 2025. It will be a very much worse situation when the October data is released in a month's time.
BANK WORKERS 'STRIKE'
Some Kiwibank workers have been on strike today between 12 pm until 2 pm over the bank’s 2.25% pay offer. The strike included customer service workers in branches and on the phones, along with workers in other roles across the bank. They pointed to Kiwibank's rising profits and rising investment in technology to bolster the idea that the bank can afford more. They are seeking a "fair pay rise" of at least the 4.1% CPI inflation.
TRUCKING PRIORITIES
In a pre-election announcement, the Government is "consulting" on changes to benefit the heavy transport sector. Included are proposals to allowing heavy vehicles to carry more weight and freight, "reducing the number of vehicle movements on the roads". exempting fire trucks from mass limits, allowing crane trucks and sucker trucks to operate more easily under specialist vehicle weight limits, and giving over-dimension vehicle operators more flexibility about when and where they can operate, including on Auckland motorways and tolled roads.
NZX50 FADES
As at 3pm, the overall NZX50 index is down -0.5% today. From a week ago it is down -1.0%; But from six months ago it is up +6.0%. From a year ago it is up +2.6% now. Market heavyweight F&P Healthcare is up +0.2% so far today. Tourism Holdings, a2 Milk, Ryman and Investore advance while Infratil, Skellerup, SkyCity and Chorus retreat.
STILL IN A FUNK
In China, 16 of their 70 largest urban areas had a small rise in new house prices in September from August, four has no change, while the rest reported small declines. Overall, these new house prices were down -2.8% from a year ago, a slightly smaller decline than in August. For existing homes, the improvement was less and the year-ago change approached -6%. So not noticeable improvement in their housing markets.
MEETING TARGET
China reported that its Q3-2026 economic activity grew +4.5% from the same quarter a year ago. That was better than the 4.3% in Q2-2026. They have a GDP growth target of "about 4.5%".
DIVERGENT
China said its industrial production was up +5.5% in September, better than the 5.2% claimed for August. But they also said their electricity production was -1.2% lower from a year ago, which doesn't really support the claim of higher production - unless they have had the surge of productivity that this implies.
CHINESE CONSUMERS STAY SUBDUED, BUT LESS SO
Chinese retail sales were up +1.0% in September from a year ago according to the same official data release, more than August's +0.4% and better than expected.
SWAP RATES ON HOLD
Wholesale swap rates will likely be little-changed again today. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was up +3 bps to 3.26% on Friday. Today, the Australian 10 year bond yield is unchanged from this morning at 5.24%. The China 10 year bond rate is now at 1.65% and up +1 bp. The Japanese 10 year bond is now at 2.90% and down -4 bps. The NZ Government 10 year bond rate is now at 5.04% and down -1 bp from this morning. (The RBNZ 10 year rate is 'prior day' and was up +6 bps at 5.00% on Friday.) And the UST 10yr yield is now at 5.06% and down -4 bps from this morning's open.
EQUITIES MIXED
The NZX50 has softened another -0.8% so far today. But the ASX200 has opened up +0.2%. However Tokyo is down -1.2%. The KOSPI is down -0.5% at its open. Hong Kong is up +0.5% in early Monday trade while Shanghai down -0.5%. Singapore is down -0.2% in early Monday trade. Wall Street futures suggest the S&P500 will open up +1.2% tomorrow.
OIL SOFTISH BUT STILL VERY HIGH
American oil prices have eased -US$1 from this morning with the WTI benchmark now at just over US$100.50/bbl, while the international Brent price is just under US$108/bbl and down -US$2.
CARBON PRICE UNCHANGED
There have been very few trades and the price is little-changed, still at $50/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD FIRMISH
In early Asian trade, gold has held firm, up +US$13/oz from yesterday, now at US$4179/oz. Silver is up +50 USc at US$57.50/oz.
NZD HOLDS
The Kiwi dollar is unchanged from this morning's open at just on 56.5 USc. Against the Aussie we are down -30 bps at just over 81.1 AUc. Against the euro we are unchanged at 50.3 euro cents. This all means the TWI-5 is now just over 60.3 and down -10 bps.
BITCOIN FIRM
The bitcoin price is now at US$82,534 and up +1.9% from this morning. Volatility has been modest at just over +/- 1.1%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
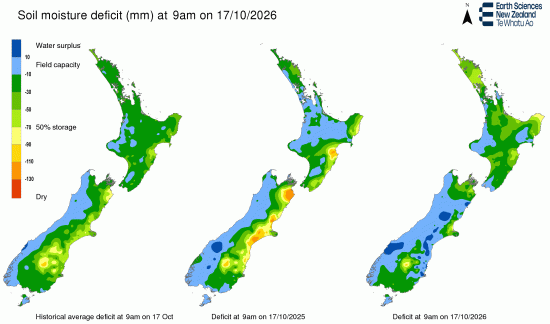
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.