
Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
No changes to note so far today yet. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
New-to-New Zealand Revolut Bank (see below) launched a 3.50% 4 month introductory at-call rate. Nelson Building Society (NBS) has raised its one year TD rate to 4.50%. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
BARFOOT SALES ACTIVITY DROPS AWAY
Auckland's largest real estate agency had fewer sales in October but selling prices were up. The spring selling season in the Queen City is off to a weak start with many buyers not tempted by the growing choice
NEW HOUSE BUILDING UPTURN
The September building consent figures released today suggest good growth in residential construction, but not so good for commercial building work.
A FINTECH BECOMES A BANK
Global fintech Revolut becomes NZ's 27th registered bank, and offers new customers a 3.50% p.a. introductory savings rate on personal accounts.
MORTGAGE STRESS VERY LOW
The latest Centrix data finds home loan arrears remain at their lowest level since December 2022, but broader credit demand stays mixed.
NZX50 DIPS FURTHER
As at 3pm, the overall NZX50 index was down -0.3% today in a further retreat. From a week ago it is now down -0.2%. From six months ago it is up +4.3%. From a year ago it is up only +0.7% now. Market heavyweight F&P Healthcare is down another -0.4% so far today. There are 30 gainers so far led by Briscoes, Synlait, NZX, and Fletcher. There are 42 decliners led by Channel Infrastructure, Napier Port, a2 Milk and Tourism Holdings.
ELECTION PORK
The coalition Government is rolling out a series of funding and grant decisions ahead of the election. That includes $1 mln to rebuild a Kaipara Harbour fishing wharf at Tinopai, for two geothermal projects near Rotorua, a Westport aged-care facility, $12 mln more for the Picton-Kaikoura Whale Trail, and $845,000 for Air Napier.
TOUGH IN FIJI
The Fijian statistics department says inflation is now running at 9% there in October, up from 6.8% in September. That is its highest level since 2011. A year ago in September it was falling at the rate of -3.8%.
EYES ON THE RBA
At 4:30 pm the RBA is widely expected to announce that it has raised its cash rate target to 4.85%, another +25 bps hike. Because it is 'widely expected' if they do it, little will happen. But if they don't, there will be sharp financial market adjustments. We will cover this on interest.com.au and will add a link here when the result is known.
SWAP RATES HOLD SOFTISH
Wholesale swap rates will likely be marginally softer today. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was down -1 bp at 3.15% on Monday. Today, the Australian 10 year bond yield is also down -1 bp at 5.14%. The China 10 year bond rate is now at 1.61% and little-changed. The Japanese 10 year bond is up +1 bp at 2.78%. The NZ Government 10 year bond rate is now at 4.92% and down -2 bps from yesterday. (The RBNZ 10 year rate is 'prior day' and was up +1 bps at 4.91% on Monday.) And the UST 10yr yield is now at 4.91% and down -2 bps from yesterday at this time but that masks some jumpiness in between.
EQUITIES MOSTLY LOWER
The NZX50 has eased -0.3% so far today. The ASX200 has opened unchanged. Tokyo is closed today for Culture Day. The KOSPI is down -2.4% at its open. Hong Kong is up +0.2% in early Tuesday trade while Shanghai is down -1.1%. Singapore is also down a sharp -1.1% in early Tuesday trade. Wall Street was up for most of its Monday trade but faded at the end when the S&P500 ended down -0.5% and the Nasdaq ended down -1.1%
OIL DROPS
American oil prices have fallen -$4.50 with the WTI benchmark now at just over US$96.50/bbl\, while the international Brent price is also lower by -US$6 just over US$104.50/bbl.
CARBON PRICE HOLDS
There has been some trading reported today but the price is still at $48/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD FIRM AGAIN
In early Asian trade, gold has risen +US$33 from this morning, now at US$3944/oz. Silver is up +50 USc at just under US$50.50/oz.
NZD DIPS AGAIN
The Kiwi dollar is down -10 bps from this morning at just under 56.1 USc. Against the Aussie we up +20 bps at just under 80.2 AUc. Against the euro we are down -20 bps at 50.1 euro cents. This all means the TWI-5 is now just over 59.8 and down -10 bps.
BITCOIN LOWER
The bitcoin price is now at US$76,976 and down -1.8% from yesterday. Volatility has remained modest at just over +/- 1.3%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
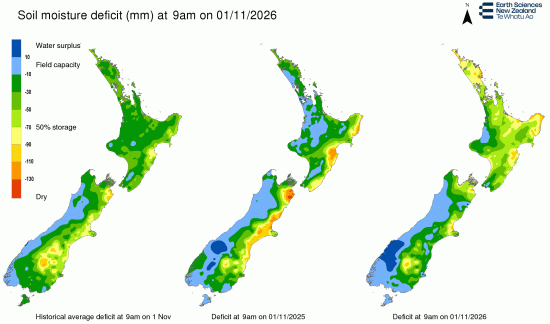
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.