Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
WBS (Wairarapa Building Society) has cut its 1 and 2 year fixed rates. Resimac cut its 1 year fixed rate. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
Squirrel raised its on-call rate by +30 bps today, taking it to a similar level as its main rivals. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
BETTER SERVICE SECTOR SIGNALS
The BNZ-BusinessNZ service sector monitor (PSI) shows a rising expansion, even if it is still modest. It is now at its highest level since 2023. Activity is up, encouragingly helped along by expanding new order levels. It is a good sign for a sector important to the economy and, therefore, the broader outlook for GDP. But the jobs market isn't strong in this sector, a sign firms aren't confident it will last. The 'good news' won't be sustainable until employment starts growing.
NO, GROCERY PRICES ARE NOT RISING FAST
The pace of supplier cost increases to Foodstuffs supermarkets in September slowed last month, with the Infometrics-Foodstuffs New Zealand Grocery Supplier Cost Index (GSCI) showing an average +1.7% increase in what suppliers charged in October, compared with a year earlier.
MORE BANK BONDS COMING
Kiwibank says it is planning an offer of up to $200 mln of 10 year unsecured subordinated notes to local investors. No mention of accepting over-subscriptions. The bonds are expected to constitute Tier 2 Capital for Kiwibank’s regulatory capital requirements.
A STABLE SECTOR
AM Best said it is maintaining a stable outlook on the New Zealand insurance industry (both life, and non-life), citing in part ongoing regulatory reforms that are expected to strengthen market discipline and governance for the non-life sector over the long term - and for the life sector, based on its "solid profitability'.
NZX50 RISES
As at 3pm, the overall NZX50 index was up +0.4% today. From a week ago it is now up +1.8%. From six months ago it is up +11.4%. From a year ago it is up +5.4% now. Market heavyweight F&P Healthcare down -0.3% so far today. There are 46 gainers today led by Synlait, NZME, EBOS and Freightways. There are 33 decliners led by Tourism Holdings, Kathmandu, Ryman and Vulcan Steel.
MORE OF THE SAME
Rabobank is forecasting that the 2027 beef market will be little-changed from the 2026 realities with farmgate prices staying relatively firm next year. They see lower supplies, higher costs, margin pressures, and shifting trade patterns, all as we had in 2026.
BARDY QUITS
The FMA says Deputy Chair Steven Bardy will resign from the FMA Board, effective November 20, 2026. He was the interim Chair after the Craig Stobo affair and through the Samantha Barras issues. He had signaled his intention to resign earlier but agreed to wait until after the election to do this formally. Bardy was a senior ASIC executive before he joined the FMA board in 2022.
HUGE MARKET UNDER THE RADAR
Last week's NZGB bond turnover on secondary markets was $84.9 bln, and there is a noticeable trending up since early June even though there have been occasional weeks in between that were higher than last week. In any event we should keep an eye on this market because it is probably the largest transaction market of any domestically. $85 bln in weekly turnover is a lot. (The NZX doesn't even make $1 bln of weekly turnover. The housing market is a touch over $1 bln/week. In its best month, export sales are just on $2 bln/week. All retail sales $2.4 bln per week. None of these are anything like the bond market, even combined.)
JAPAN PADDLES FAST, GOING NOWHERE
To the surprise of many, Japan said its Q3 GDP was unchanged from Q2 and declined slightly from a year ago. All its nominal growth was just inflation at work. Private consumption, the biggest component of GDP, shrank -0.3%. The result reflects a period of bad weather and typhoons, as well as weaker consumer sentiment amid rising prices. Inflation-adjusted real wages have been higher than the previous year for nine consecutive months through September. But thrifty consumer behavior under a deflationary mindset is still dominant in Japan.
DOWNWARD PRESSURE EASES
Updated October data out from China today shows that Shanghai remains one of the only a very few major cities where prices for new housing is rising. Beijing's recovery ended and they are falling there now according to this official data. Price falls elsewhere continue but at a slower pace. Price falls are faster for existing homes, although Shanghai again bucked the trend.
TEPID AT BEST
October data shows that Chinese electricity production fell -2.1% from a year earlier with electricity generated by coal down -7.3% and hydro production down -18.9%. Stemming the decline were big increases from nuclear sources (+17.5%), and both wind and solar rose more than +30% from a year ago. But the fact remains, overall they are generating less electricity. They claim that despite this they managed to produce +4.8% more industrial production, by value at least. Hard to reconcile. Retail sales in October were only a marginal +0.4% more in value than in the same 2025 month. Chinese CPI inflation was +0.7% in October. 'Tepid' at best. They run hard just to stand still.
SWAP RATES FIRMISH
Wholesale swap rates have probably firmed again today but only slightly. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was up +1 bp at 3.20% on Friday. Today, the Australian 10 year bond yield is up +2 bps at 5.14% from this morning. The China 10 year bond rate is now at just over 1.62% and up +2 bps. The Japanese 10 year bond is unchanged at 2.87%. The NZ Government 10 year bond rate is now at 4.88% and up +3 bps from this morning. (The RBNZ 10 year rate is 'prior day' and was up +9 bps at 4.82% on Friday.) And the UST 10yr yield is now at just on 5.14% and down -1 bp from this morning.
EQUITIES WAITING FOR WALL STEET
The NZX50 has risen +0.5% so far today. But the ASX200 has opened down -0.1%. Tokyo is down -1.4% at its open. The KOSPI is down a sharper -2.8%. Hong Kong is up +0.7% in early Monday trade while Shanghai is down -0.9%. Singapore is unchanged. Wall Street futures aren't signaling much either with the S&P500 expected to open down -0.1% and the Nasdaq futures are down just -0.2%. In advance of the Anthropic IPO and the Nvidia politics, investors are just waiting to see in anything market-moving develops. Their don't have any inkling in advance.
OIL PRICES STABLE
American oil prices have essentially held from this morning, with the WTI benchmark still at just on US$88.50/bbl, while the international Brent price is down -50 USc at just over US$95/bbl.
CARBON PRICE EDGES UP
There have been a few good-sized trades reported today so far, and the price is up almost -50c at $49.95/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD SOFTISH
In early Asian trade, gold has retreated another -US$14 from this morning, now at US$3868/oz. Silver is down -US$1 at just over US$47.50/oz.
NZD ON HOLD
The Kiwi dollar is little-changed from this morning's open, still under 55.3 USc. Against the Aussie we up nearly +20 bps at just under 81.47AUc. Against the euro we are unchanged at 50.1 euro cents. This all means the TWI-5 is now just over 59.4 and little-changed from this morning.
BITCOIN LITTLE-CHANGED
The bitcoin price is now at US$64,754 and up a minor +0.2% from this morning. Volatility has been moderate at just on +/- 2.7%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
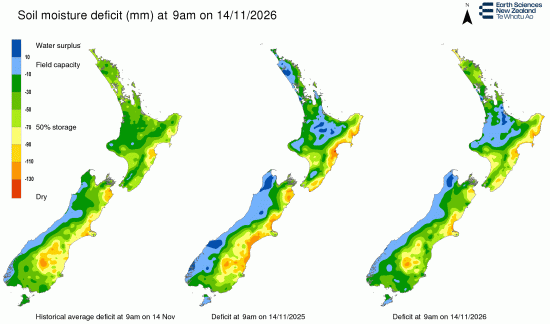
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.