Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
No changes to report today. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
TSB has raised its 6 month, 9 month and one year TD rates today. Only their six month 3.70% rate compares well with the main banks. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
KOOKMIN BANK GONE
According to a Companies Office filing, the Auckland branch of Kookmin Bank has closed and they are no longer doing business here.
A TEMPORARY PAUSE?
The October BNZ-SEEK job ads tracking came in at lower levels than in September. BNZ observed: "The subdued nature of this data across many industries and regions suggests a common cause. Cost pressures would be an obvious candidate and perhaps uncertainty ahead of the election. If the latter played a part, some relief may occur once a new government is formed. Only time will tell."
UNDER COST PRESSURE
Producer input costs rose +4.5% in the September quarter from the same period a year earlier, their highest rise since March 2025. Meanwhile producer output prices didn't keep up, rising +3.9%. From the prior quarter output prices were up at a faster pace, input costs up at a slower pace as first struggled to catch up.
IT ISN"T CHEAP RUNNING A FARM, (UNLESS YOU ARE A FARM EMPLOYEE)
Farm expenses rose +1.7% in the September quarter from the June quarter, and that put them +6.5% higher than year-ago levels. So the pace of increase of non-livestock farm running costs is staying high. That was obviously driven by fertiliser (+19.1% pa) and fuel (+35.8%), but also electricity (+4.2%) and government charges (+9.0%). Not everything is rising; interest rate costs were down -1.1% and wages paid only rose +1.5% from a year ago.
SAVED BY THE WEAK DOLLAR
The overnight full dairy auction brought no overall change in prices in USD terms but the retreating NZD enabled it to report a gain of +2.1% in NZD terms. Within the flat result were some sharp component changes, especially notable being the weakness of the milk fats: cheddar was down -4.1%, AMF down -8.2% and butter down -6.5% from the prior full event two weeks ago. However that was covered by a good +2.2% rise for SMP and a +2.7% rise for WMP and these two made up more than three quarters of the volumes sold.
NZX50 FIRMISH
As at 3pm, the overall NZX50 index was up +0.2% today. From a week ago it is now up +1.1%. From six months ago it is up +12.3%. From a year ago it is up +7.4% now. Market heavyweight F&P Healthcare is up +0.9% so far today. There are 35 gainers led by Napier Port, Infratil, Synlait and Channel Infrastructure. There have been 46 decliners led by Vulcan Steel, Vital Heathcare, Summerset and Oceania.
SAVING GAMBLERS FROM THEMSELVES
The FMA is putting energy into protecting retail traders who want to trade in commodity and financial derivatives. They found some firms were not doing enough to ensure retail investors understood the products they were trading and the risks involved. The FMA also found that highly leveraged derivatives can expose investors to significant losses. (NSS) From 18 November 2027, derivatives issuers will be required to obtain sufficient information to assess whether a product is suitable for a retail investor before allowing them to trade it. Firms must also ensure investors understand the product and its risks and must not permit trading where a product is unsuitable or not understood.
NO REAL PROGRESS
The latest Health Survey has found that daily smoking continued its long-term decline. In 2025/26, 5.9% of adults smoked daily, down from 9.4% five years earlier. BUT, the same survey found that daily vaping rates are now up to 11.2%. (If you included those younger users who were not surveyed, what would the result be?)
THE PRESSURE STAYS ON
In Australia, wage cost data out today shows this aspect of their inflation activity is rising. Annual pay growth at 3.5% is still below the 2023 peak, but a further sign of price pressure in the Aussie economy.
A MANGEABLE DEFICIT
Japanese exports rose a startling +20.5% in October from a year ago to a record high NZ$134 bln in the month. But their imports were up even more by +21.6%, also to a record high. However than enabled them to hold their trade deficit to just -NZ$5.4 bln which is not significant for the world's fourth largest economy at about -1% of GDP. (A year ago it was a deficit of NZ$3.5 bln in the October month.) They are absorbing the oil shock with relative ease.
SWAP RATES ON HOLD
Wholesale swap rates are probably unchanged today. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was unchanged at 3.21% on Tuesday. Today, the Australian 10 year bond yield is down -1 bp at 5.12% from yesterday at this time. The China 10 year bond rate is just over 1.59% and down -3 bps. The Japanese 10 year bond is also down -3 bps at 2.85%. The NZ Government 10 year bond rate is now at 4.89% and up +1 bp from yesterday. (The RBNZ 10 year rate is 'prior day' and was unchanged at 4.85% on Tuesday.) And the UST 10yr yield is now at just on 5.10% and down -4 bps from this time yesterday.
EQUITIES IGNORE NVIDIA, SEE ANTHROPIC PRICED IN
The NZX50 has firmed a minor +0.1% so far today. But the ASX200 has opened down -0.4%. Tokyo is down -0.4% at its open. The KOSPI is up +0.6%. Hong Kong is down -0.5% in early Wednesday trade while Shanghai is up +0.1%. Singapore is down -1.1%. Wall Street ended with the S&P500 down -1.0% and the Nasdaq down -0.7%. The strong Nvidia earnings report has not induced investors to rush non-American markets before Wall Street reopens. The Anthropic IPO prospect isn't doing anything either. Wall Street futures are essentially unmoved.
OIL PRICES MIXED
American oil prices have fallen -US$1.50 from yesterday at this time, with the WTI benchmark now at just over US$85.50/bbl, while the international Brent price is up +US$1.50 at just under US$93/bbl.
CARBON PRICE HOLDS
There have been few trades reported today so far, and the price is still at $50/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD FALLS
In early Asian trade, gold has fallen, down -US$74 from yesterday, now at US$3793/oz. Silver is down -US$1 at just over US$46/oz.
NZD ON HOLD
The Kiwi dollar is basically unchanged, still just under 55 USc and still a 17 year low. Against the Aussie we up +10 bps at just under 81.7 AUc. Against the euro we are also unchanged at 50 euro cents. This all means the TWI-5 is now just on 59.2 and on hold from this time yesterday.
BITCOIN MOVES LITTLE
The bitcoin price is now at US$64,321 and down -0.6% from this time yesterday. Volatility has been modest at just on +/- 1.4%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
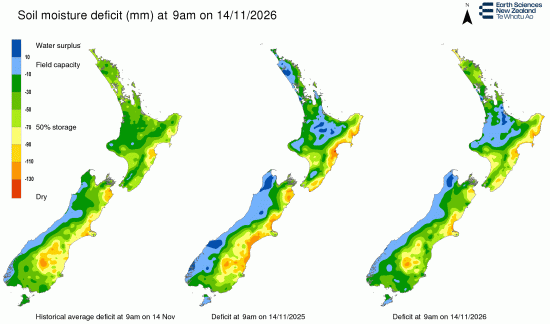
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.