Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
No changes to report today. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
NBS has dropped its 1 year rate back to 4.30% but added a 15 month rate at 4.50%. General Finance has trimmed all its shorter rates from 4 to 9 months. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
RISING MILK PRICE
Rising milk powder prices sees Fonterra raise it's 2026/27 payout forecast by +35c to a $10.10/kgMS midpoint. If it is sustained, it will be the second highest level since the 2024/25 $10.16/kgMS payout.
WHAT FINANCIAL MARKETS ARE PRICING
There are a set of major central bank rate reviews due over the next four weeks. Financial markets are pricing in a high chance that almost all of them will raise their policy interest rates as they battle inflation. The RBNZ will review on December 9 and currently markets price in a 80% chance of a +25 bps hike, taking the rate to 3.0%. The next day the US Fed will review and markets price in a 100% chance of a similar hike, in their case to 4.25%. The ECB meets on December 17 and pricing is 100% for a +25 bps hike to 2.90%. The English also review the same day and 72% of a +25 bps hike is priced in there, to 4.25%. The Canadians next review on December 9, and markets price in a 68% chance of a hike to 2.50%. The only one where no hike is priced in is Australia where the rate is already 4.85% but they have the highest inflation threat (4.3% and rising). Go figure.
CARD USE SAGS
Domestic billings on New Zealand issued credit cards were $4.0 bln in October, down -0.3% from September but up +3.5% from October 2025 - but only +1.1% if you don't seasonally adjust the actual data. That means this type of retail spending isn't keeping up with inflation.
NOT RISING BUT STILL VERY HIGH
In their November household expectations survey, the RBNZ found that household annual CPI inflation expectations for the one-year-ahead horizon decreased from 5.6% to 5.3% this quarter. The median estimate for one-year-ahead annual inflation decreased from 4.5% to 4.0%.
FADING
The same survey revealed that households no longer expect any house price 'inflation' over the year ahead and the expectations for five years ahead are falling away too.
NZX50 ENDING LOWER
As at 3pm, the overall NZX50 index was down -0.6% today. From a week ago it is now little-changed. From six months ago it is up +11.0%. From a year ago it is up +5.4%. Market heavyweight F&P Healthcare is down -0.1% so far today. There are 29 gainers led by Turners, Tourism Holdings, SkyTV and AirNZ. There are 47 decliners led by Fletchers, Genesis, Summerset and Ryman.
A NEW TAX-FREE BASE
Morrisons, the manager behind Infratil, has opened an office in the international financial center and financial free zone in Abu Dhabi, UAE. The center operates under a legal system based on English common law. Qualifying income there attracts a 0% income tax, and there is no personal income tax there either. The other attraction for Morrisons is that their focus across digital infrastructure, energy transition, and critical supply chains is closely aligned with Abu Dhabi’s stated long-term economic priorities.
RISING AGAIN
Japan's inflation is rising. It was reported at 2.3% in October, up from 2.1% in the prior month to be the highest level since November 2025. A year ago it was 3.0% and on its way down. Current core inflation, which excludes fresh food, edged up to 2.2% from 2.1% in September. All of these rates are above the Bank of Japan’s 2% target.
UNCHANGED AGAIN
China held its Loan Prime Rates unchanged in its November review.
SWAP RATES DIP MARGINALLY
Wholesale swap rates are probably slightly lower today, again. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was unchanged at 3.21% on Thursday. Today, the Australian 10 year bond yield is down -7 bps at 4.96% from yesterday at this time. The China 10 year bond rate is just over 1.57% and down -5 bps. We make that an all-time low. The Japanese 10 year bond is down -3 bps at 2.81%. The NZ Government 10 year bond rate is now at 4.82% and down -3 bps from yesterday. (The RBNZ 10 year rate is 'prior day' and was down -6 bps at 4.79% on Thursday.) And the UST 10yr yield is now at just on 5.02% and down another -5 bps from this time yesterday.
EQUITIES FALL SHARPLY
The NZX50 is down -0.5% so far today. But the ASX200 has opened down -1.4%. Tokyo is down a massive -4.2% at its open. The KOSPI is down -4.4%. Hong Kong is down -1.6% in early Friday trade while Shanghai is down -1.7%. Singapore is also down -1.6%. Wall Street ended with the S&P500 down -2.0% while the Nasdaq was down -2.3%.
OIL PRICES EASE
American oil prices have fallen another -US$1.50 from yesterday at this time, with the WTI benchmark now at just under US$82.50/bbl, while the international Brent price is down -50 USc at just under US$92.50/bbl.
CARBON PRICE STALLED
This market is still very quiet again today, and the price is still at $50/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD FALLS SHARPLY, AGAIN
In early Asian trade, gold has fallen again, down -US$102 from yesterday, now at US$3561/oz. Silver is down -US$3.50 at just over US$42/oz.
NZD HOLDS LOWER
The Kiwi dollar is down -10 bps just over 54.8 USc and a new 17 year low. Against the Aussie we up +20 bps at just on 82.4 AUc. Against the euro we are down -10 bps at 50 euro cents. This all means the TWI-5 is now just on 59.2 and little changed from this time yesterday.
BITCOIN LOWER AGAIN
The bitcoin price is now at US$61,488 and down another -2.1% from this time yesterday. Volatility has been moderate at just on +/- 2.1%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
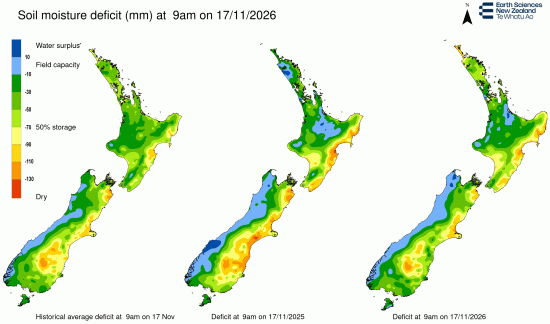
This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.