
Here's our summary of key events overnight that affect New Zealand, with news the crisis in emerging markets is rocking first world investors.
Overnight, Turkey's worsening currency crisis sent world equities lower and cut into the value of emerging market stocks and currencies, while boosting the price of assets that investors flock to in a crisis.
This morning, Wall Street is lower, but not excessively so. But late yesterday, Tokyo closed -2% lower in a major reaction. Hong Kong was down -1.5%, and Shanghai was down -0.3%. Sydney closed -0.4% lower while the NZX was down -0.7%. The fact that Wall Street's correction is restrained, and most European markets aren't slipping like the Asian ones did yesterday probably means the immediate threats are subsiding in investor eyes.
But the situation in Turkey is not good. It has alarmed investors by making its central bank a political arm of its President. He has appointed a family member as Finance minister. And he is saying he is looking for 'new friends' and that means NATO's southern flank is now exposed. Turkey is promising a 'new plan'.
The ECB is worried some EU banks are excessively exposed to Turkish risks, which is why bank stocks are getting marked down.
And the fallout extends to India, and to Argentina, where they just raised their policy rate by +500 bps to 45% (not a typo). South Africa is being buffeted hard too. This has all the signs of a contagion.
In China, they are working hard to insulate themselves from the US tariffs, and now this growing emerging market pullback. They are doing it with more debt, "easier credit". In July, Chinese banks beat expectations with +76% jump in lending from the same month a year ago. However, the July growth was less than the June growth, even if it did beat expectations. (They also have a growing bad loans problem.)
The UST 10yr is holding at 2.88%, with the US 2-10 curve still at just +26 bps. The Aussie Govt 10yr is at 2.58% (down -1 bp), the China Govt 10yr is at 3.60% and up +3 bps, while the NZ Govt 10 yr is at 2.60%, down -1 bp.
Gold is down sharply today by -US$18 and now a just at US$1,193/oz in New York. The price of gold hasn't been this low in eighteen months.
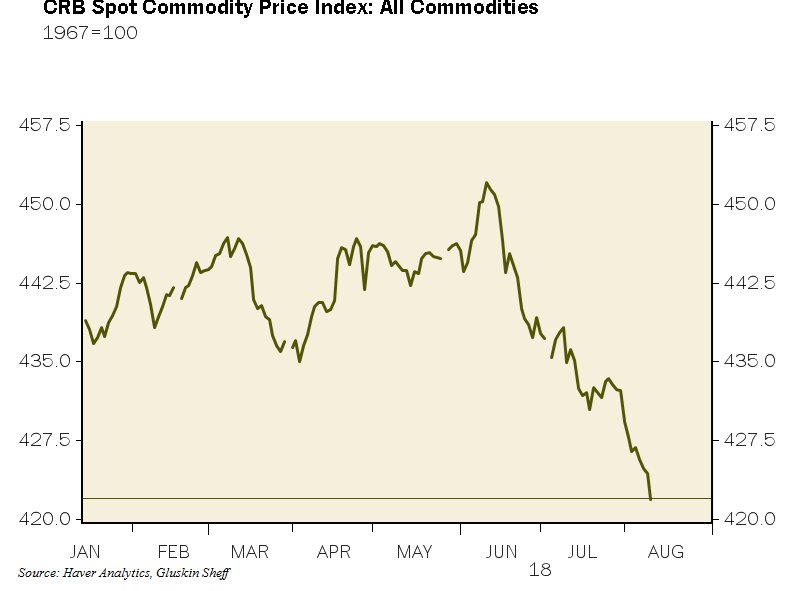
US oil prices are soft today and now below US$66/bbl. The Brent benchmark is now just over US$71/bbl. These represent a -US$2 fall, driven it seems by rising production and softening demand prospects, especially by emerging market economies.
The Kiwi dollar is starting today little changed from yesterday at 65.8 USc. On the cross rates we are still at 90.5 AUc, and at 57.7 euro cents. That leaves the TWI-5 at 69.8, unchanged from yesterday but still very near a three year low.
Bitcoin is also little changed at US$6,217 which is just -1.3% lower than this time yesterday.

This chart is animated here. For previous users, the animation process has been updated and works better now.
The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.