Here's my politico-economic blogroll this week. Had a break for a couple of weeks there. Fridayitus kicked in a bit. Have a great weekend all.
No right or left this week. Everyone crosses over all the time now anyway it seems.
1. Why we should be floating Genesis, Mighty River Power, Meridian and Solid Energy. David Farrar at Kiwiblog thinks this would lead to more transparent financial reporting, after Meridian announced NZ$90 million in write-downs as it prepares for its listing.
Being listed on the NZX means the companies have to be more transparent with their finances, and have obligations such as continuous disclosure.
As an SOE it looks like Meridian has been carrying these impaired assets for some years at an unrealistic valuation. You can’t do that so much when you are a publicly listed company.

EBITDA of US$37 Billion
Revenue up 35 per cent to 71 billion.
And an operational profit of $31 bill.
This statement:
"...labour and contractor costs are broadly correlated with the mining industry’s level of activity. In the current environment, tight labour and raw material markets are presenting a challenge for all operators, and BHP Billiton is not immune from that trend."
That is: as mining industry profits rise, wages go through the roof.

For months now the pollsters and their media messengers – most prominently (since they are on television) the political soothsaying duo of Garner and Espiner – have been telling us, with a degree of schadenfreude bordering on glee, that Goff and Labour are toast. It seems naive in the extreme to believe that this has no effect on voting preference. The polls, in a word, have a built-in tendency to be self-fulfilling.
This might be of less significance – and the results might be slightly or even significantly different – if political issues were discursively debated on prime-time television. They aren’t. There is no programme on prime-time television devoted to the analysis of political issues. This reflects, and has for decades reflected television executives’ belief that politics are boring and of little interest to the prime-time viewer. Hence the marginalisation of political debate to Saturday and Sunday morning. Q & Aand The Nation are both good programmes, but their audiences are, of necessity, small in comparison to programmes broadcast in the evening.
This absence of informed, in depth, prime-time television debate of political issues serves to favour and encourage political judgements made on the basis of on-screen personality or facility with the medium rather than on the basis of policy or the national interest. What the politician says or believes is of less importance than how he or shecomes across. As a long-time media advisor to the political Left, I am of course complicit in all of this. But this does not prevent me from bemoaning the failure of the television networks to meet what I consider their obligation (certainly Television New Zealand’s obligation) in a democracy to foster and promote political literacy among their viewers. Politics has been reduced in prime time to the level of a beauty contest in which the contestants’ attractiveness is the main criterion for winning the judges’ approval.
It’s interesting to watch the economists flip as the economic system implodes. The most dramatic (and welcome!) NZ example has been Bernard Hickey but many of his colleagues are also throwing off their neoliberal blinkers.
5. Don't listen to the forecasters, watch the entreprenuers. Peter Cresswell at Not PC isn't the least bit surprised at Rodney Dickens' analysis of economic forecasters over the last year.
Why? Because the future is inherently uncertain, and econometric analysis can’t change that one whit. All it does is provide mathematical justification for going wrong with confidence.
Now, it’s true as economist Ludwig Von Mises say that “historians and statisticians content themselves with prices of the past,” while “practical man looks at the prices of the future”--and that econometricians pretend to use the prices of the past to predict the prices and conditions of the future. But the fact they can’t, and never can, just reinforces the crucial role of entrepreneurs in driving economic activity: in taking risks on the future with their own money based on their own individual estimations of the future.
It’s not blind crystal-ball readers who move the world, it’s entrepreneurs. And most econometricians wouldn’t even know how to spell the word.
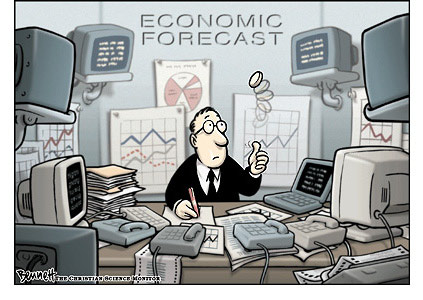
6. Ease up a bit. Infometrics economist Matt Nolan defends his peers at his blog TVHE.
I would be seen as a forecaster myself – but outside of making sure my data is up-to-date and that my empirical methods are robust, I spend all my time catching up on reading, talking to people, and trying to bring as much information together as I can. I then distill it down and try to give it to clients in an easy to digest way – so that they can understand what is going on, and what the risks are for the future.
It's a service, we are paid to provide information, and to always be available to help inform people in government and business – so that they can make the decisions they think are appropriate. If any of you have been to one of my presentations, you’ll remember how much I bang on about this – and how I spend the whole time focus on “why” and discussing “risks” and the reasons for them, rather than focusing on arbitrary numbers.
Now, I thought this would be obvious – as Peter says it is entrepreneurs that make the choices, and so they will value this type of service insofar as it helps give them information that allow them to make better informed choices. Explanation, discussion, and helping to make the economic jargon transparent, is the sort of service that is provided by all these guys … so what’s with the angst?
But the view of the last year has been very wrong
Undeniably, and if it was possible to forecast the sharp rise in fuel prices, the impact of new banking regulations (with no relevant history), the global droughts, the earthquakes in Canterbury, the snow storms during lambing in the South Island, and government policy changes they would have been less wrong – but there is no change someone would have picked the actual numbers.
But just because so much is “unknowable” does not mean there isn’t value in discussing what we do know – and keeping informed. If a client feels ill-informed, the guy is failing and needs to up their game – that is the issue that really needs to be looked at if we want to judge these people.
7. Why you shouldn't be taking GST off fresh fruit and veg. Eric Crampton Seamus Hogan at Offsetting Behaviour has been responding to John Pagani's position that taking GST off fresh fruit and veg is a good idea. Eric doesn't favour a 'dirty GST' to say the least.
When one considers the overall tax system rather than just the GST in isolation, it becomes clear that excluding a class of goods from the GST is a lousy way to achieve income redistribution. To illustrate, consider an economy with a broad-based GST, but one that includes an exemption for a particular class of goods done for equity reasons rather than to encourage consumption of those goods.
Now consider an alternative system in which the exemption is removed, and the extra revenue earned is returned as a negative poll tax to every adult in the country. Such a redistribution would be easy to implement. It simply means bringing the implementation of the benefits (dole, superannuation, DPB, etc.) into the same system as income tax, and then either increasing benefits or reducing the tax liability by a fixed amount. This policy will eliminate the distortions implied by having differing rates of tax, and would eliminate the compliance and enforcement costs that come from having different tax rates across different goods.
And the impact on equity? As long as the rich spend a greater absolute amount on the good that had been zero rated than the poor, even if the good is a necessity that takes up a smaller fraction of their income, this policy will see the tax bill of the rich being raised by a greater amount than the poor while all receive the same rebate back. That is, removing a GST zero-rating would be a distortion-free way of taking from the rich to give to the poor!
Only if the good in question were one where poor people spent a greater absolute amount than the rich would removing the zero-rating not be equity enhancing. Are there such goods? I haven’t seen data on this, but at a guess the only candidate goods would be fast food and cigarettes.

8. RBNZ ready to intervene again? Radio NZ economics correspondent Nigel Sterling penned this piece on Natrad's website about how the Reserve Bank had its foreign reserve holdings back down to a position where it had intervened in the past. ...but will it intervene? We wait with baited breath for news on QE3...
A cursory look at the Reserve Bank's balance sheet suggests it could be getting ready for an intervention.
When it intervened in the markets in 2007 and 2008 it took on a big financial risk, selling several billions of New Zealand dollars for foreign currency. It risked big losses on those foreign reserves if the Kiwi had continued to surge.
But as the Kiwi plummeted during the global financial crisis, the bank's financial markets department was able to make hundreds of millions of profits. It was able to make these as it bought back New Zealand dollars for less than it sold them for in 2007 and 2008.
In the process, the bank also reduced its unhedged foreign reserves down to its long-term target of about $2 billion.
The head of Massey University's Centre for Banking Studies, David Tripe, says it could be argued that reserves at these lower levels sets the central bank up to again intervene in the currency markets.
If it intervenes in the markets and sells the Kiwi, then the potential losses it would suffer if the currency continued to rise would be much less than if it had held on to the reserves from the 2007-08 interventions.
9. Don't just read the headlines. Homepaddock has a look at a list of the world's 50 safest banks. Half of them are in Europe it seems, although the rankings are based on credit ratings.....
But almost half the institutions on Global Finance’s list of the 50 safest banks are European and the commentary has more reassurance:
With more than 40 of the top 50 banks from last year once again making the list, the Global Finance ranking shows that most of the top echelon of banks are truly worthy of the moniker World’s Safest Bank.
Winners were selected through an evaluation of long-term credit ratings—from Moody’s, Standard & Poor’s and Fitch—and total assets of the 500 largest banks worldwide.
The list includes the four Australian banks which opponents of foreign investment crticise for owning trading banks in New Zealand.
10. Video. My flatmates and I were listening to Pulp last night, so thought I'd share it with the rest of you. Cracker song. Have a good weekend all.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.