New Zealand is one of the most “trusted” countries in the world with estimates of at least 500,000 trusts in a population of just five million.
Trusts are one of the most flexible asset ownership vehicles that we have, and while there are good reasons for many of the trusts in New Zealand, a large proportion of them are more than likely not needed.
Trusts have been around since the days of the Crusades in the middle ages. The knight would go off to fight in the crusades, not sure whether he would return, so would leave his estate in the hands of his neighbour to hold the property in trust for his wife, children and future generations – a worthy reason to have a trust relationship.
Trusts really began to take off in New Zealand in the 1980s and 1990s. Back then we had estate duty, meaning that if you died, depending on your wealth, a proportion of your estate would have to be paid to the government as a tax. Carefully planned trust structures could help to ensure that estate duty was not payable, by taking assets out of your hands and placing them in trust.
Over time, other benefits of placing assets in trust became apparent – it could mean that income wasn’t assessed for superannuation qualification (back when there was a surcharge which effectively meant means testing) and for many New Zealanders that they would still qualify for a rest home subsidy as their assets were no longer in their own names.
There were also tax planning opportunities with the ability to tax split through a trust structure – simply put, many people set up trusts and moved their assets into them because their accountant told them to. Many others set them up because that was what everyone else was doing and they didn’t want to get left behind – perhaps a case of the Emperor’s new clothes?
Over time though, many of these perceived advantages of trusts have been eroded. The surcharge on superannuation was abolished in the early 1990’s. Death duties were zero rated in the late 1990s and then subsequently abolished. Limitations on being able to allocate income to minor beneficiaries at their lower tax rates was introduced in the early 2000’s and then in the late 2000’s, marginal tax rates were flattened, pulling the top personal tax rate down to be in line with the trust tax rate of 33%. This reduced many of the tax benefits in having income producing assets in trust.
Lastly, the landscape of rest home care in New Zealand has vastly changed since the 1990s. Rest home subsidies are now very difficult to get and are only really available for those in need. Having a trust will certainly not ensure that you will get the subsidy if you go into care, regardless of how long you have had your assets in trust or when you gifted them.
For many people, particularly those whose main asset is their family home, having a trust may in fact be detrimental when applying for the subsidy. Some people may be in a position where they are more likely to receive the subsidy if they don’t have a trust than if they do.
Coupled with some of the perceived benefits no longer being there, a higher duty on trustees to keep accurate records, hold trustee meetings and provide certain information to beneficiaries, means that the costs of continuing to run some trusts will outstrip any potential benefits.
The new Trusts Act 2019 which comes into force in January 2021 outlines more stringent rules for how trusts must operate. This has got many people thinking as to whether a trust is actually the best asset owning vehicle for them.
There are of course many good reasons why a trust might be right for you and your family. The simple flow chart below can help with the decision as to whether you need a trust or maybe should be thinking about other ways of dealing with your assets. The benefits are great for many.
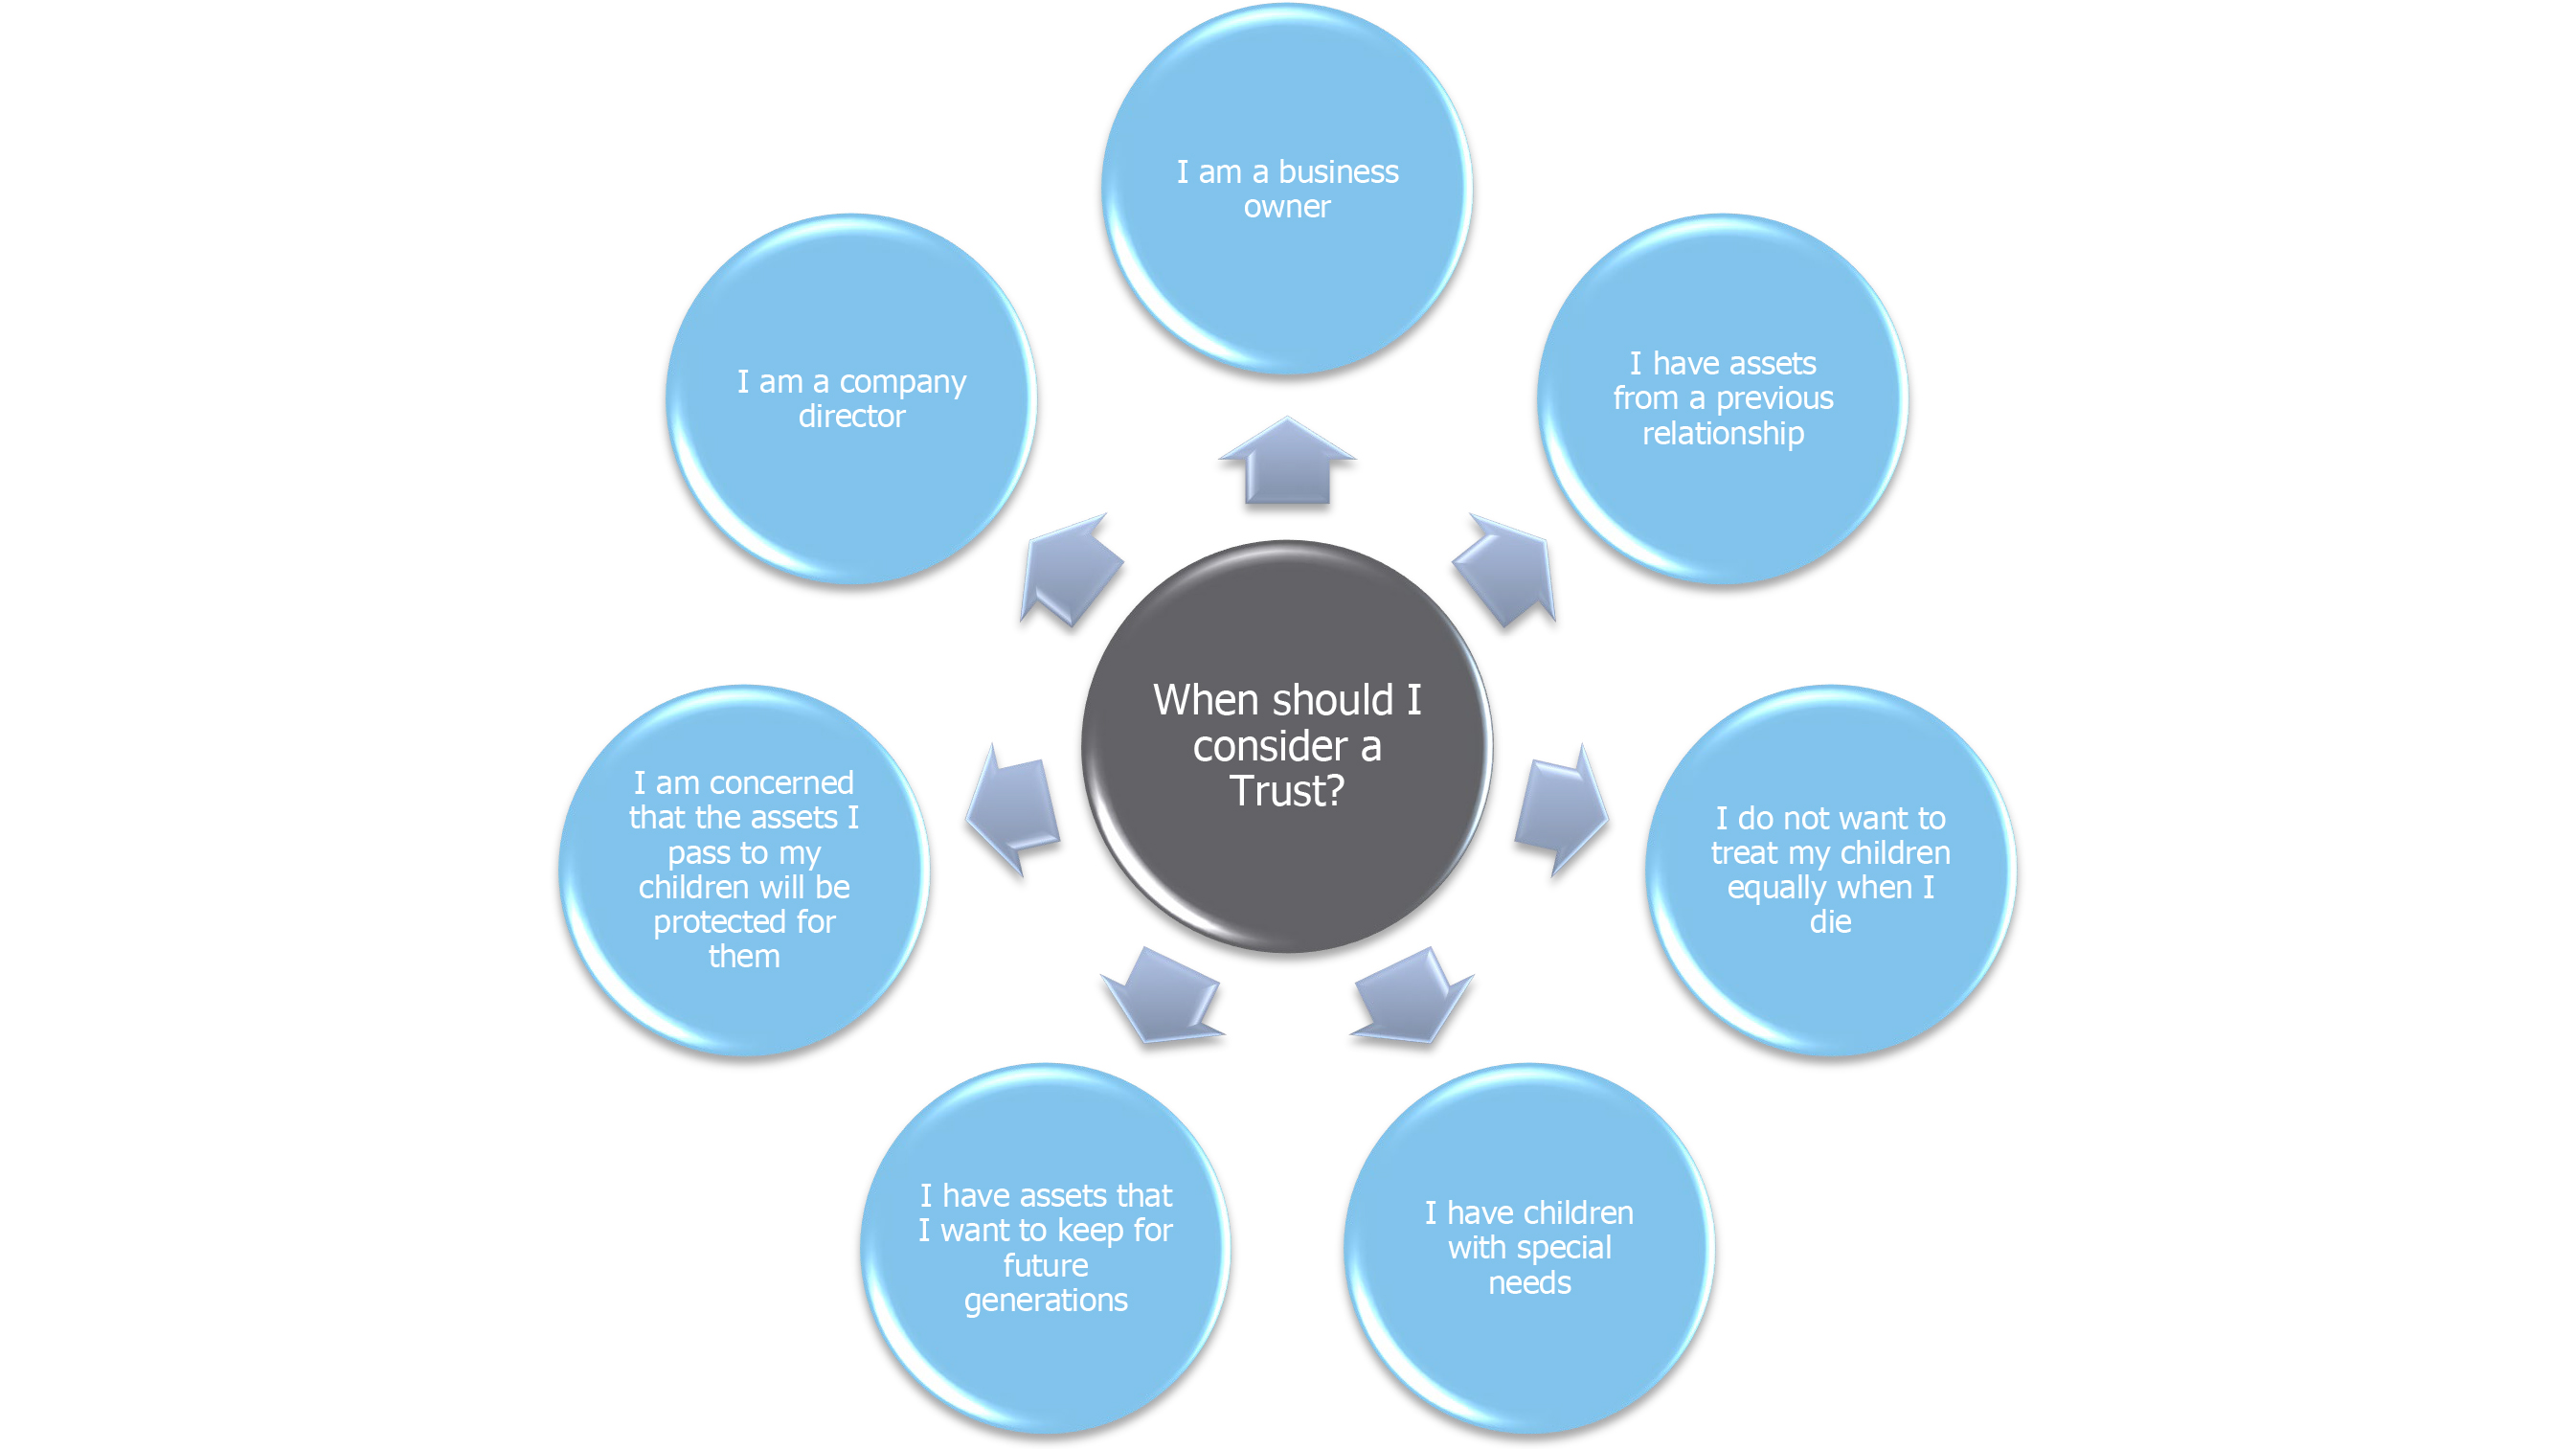
However, trusts are not the only asset planning tool and for many New Zealanders; a well-crafted Will may be the best thing for them rather than a Trust. The important thing is to take advice, consider your options and do what is best for you and your family.
Tammy McLeod is the is the managing director at Davenports Harbour, specialising in the areas of personal asset planning, trust law and Property (Relationships) Act.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.