
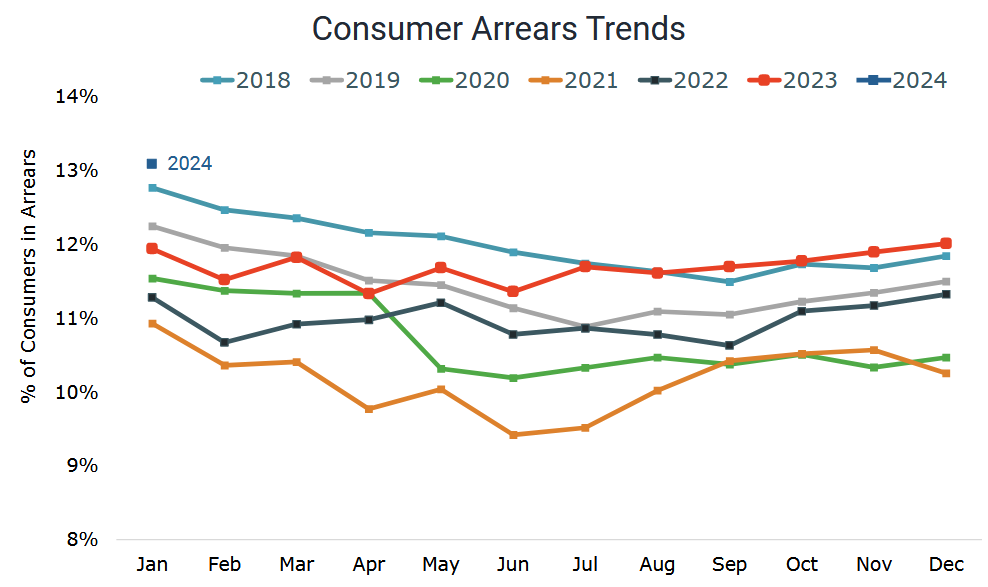
Credit arrears hit a seven-year high in January and were up 9.6% year-on-year, according to credit bureau Centrix.
The arrears are at the highest level since February 2017.
Centrix managing director Keith McLaughlin said in the company's latest monthly Credit Indicator that the rise in credit arrears reflected seasonality following the festive season and summer holiday break.
"There are 480,000 consumers across the country in arrears," he said.
McLaughlin also noted that the percentage of mortgages in arrears climbed to 1.47% in January 2024, up from 1.40% in December and reaching the highest level reported since pre-Covid.
This equates to over 21,800 mortgage accounts past due, up 16% year-on-year.
Separately, Reserve Bank (RBNZ) figures for January released last week showed that the amount of non-performing mortgages had risen by over 10% in the month.
McLaughlin said the percentage of vehicle loans in arrears also climbed - to 6.0% in January, up 5.0% year-on-year. Credit card arrears also rose to 4.9% - "although this remains low compared to historical levels".
"Interestingly, telco/communications arrears have reached a new high of 11.7% as households fall behind on these account repayments. Personal loans and Buy Now Pay Later arrears also climbed to 9.9% and 9.0% respectively," he said.
Kiwi businesses saw defaults and liquidations climb overall in January 2024, with retail trade seeing the biggest number of liquidations followed by construction, hospitality and transport. Overall business defaults were up 28% year-on-year in January 2024, while company liquidations were up 16% over the same period.
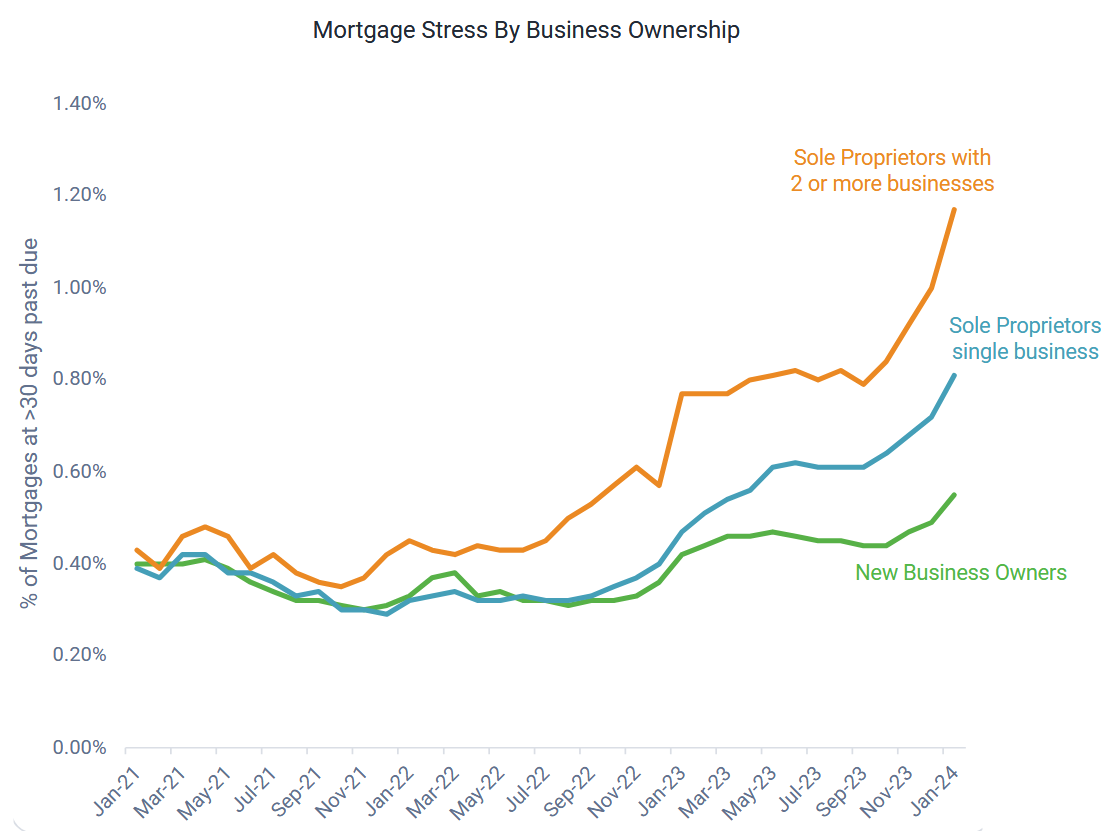
"We’ve also observed an upswing in mortgage stress for a sole proprietor [of a business], with many needing to leverage their home equity to continue funding their businesses – a concerning trend that could spell trouble for these owners in the long term.
"It’s clear the cost-of-living is continuing to impact Kiwi households and businesses across the country."
McLaughlin said the financial strain "skews towards the younger demographics".
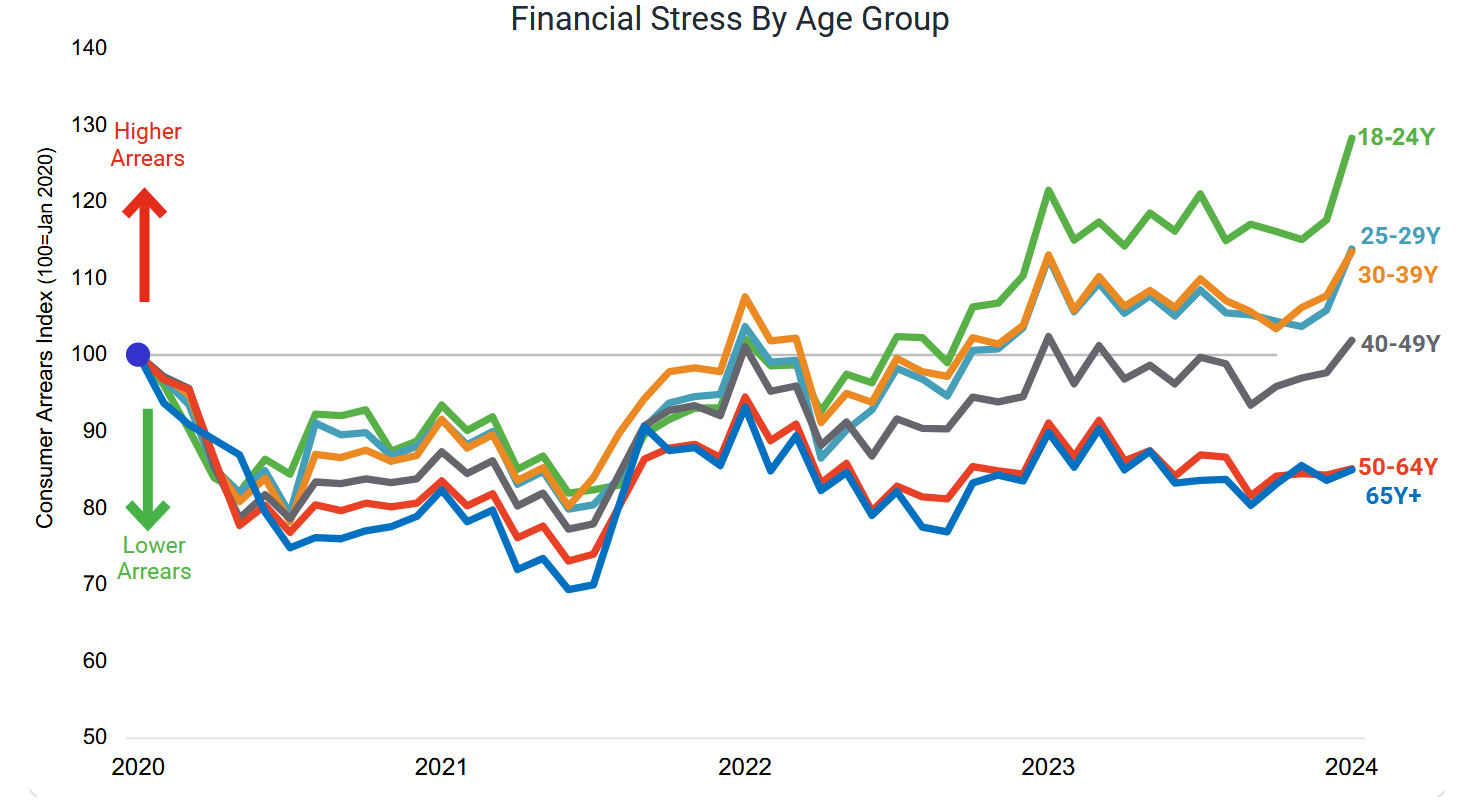
"Those under 25 years old are more prone to cash flow problems due to likely lower incomes, limited savings and less financial experience.
"We are now starting to see the squeeze flow onto 30-40 year olds, who are likely more financially stable but have perhaps used their buffers."
McLaughlin said that alongside climbing arrears, demand for credit was also up in February 2024. This was driven by increased interest in credit cards and Buy Now Pay Later products.
There was also an uptick in mortgage enquiries, which could point towards a warming of the real estate market in 2024.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.