We spend most our working lives conscious of building a nest egg.
But what then? How do we make sure that nest egg sees us through 10, 20, 30 years of retirement?
The Society of Actuaries has released a report outlining four strategies it suggests New Zealanders consider as a guide to deciding how much of our retirement savings to spend each year.
In its paper, ‘Decumulation Options in the New Zealand Market: How Rules of Thumb can help’, it details different approaches, who they may be best suitable for, and what their pros and cons may be.
It poses its strategies based on the assumption a retiree has around $100,000 in a conservative or balanced investment fund (including KiwiSaver), receives New Zealand Superannuation and has some savings to call on in an emergency.
Its research indicates the median KiwiSaver balance of those aged 65 will reach $100,000 in inflation-adjusted terms in 25 years’ time.
Here are the Society’s ‘Rules of Thumb’ (in its own words):
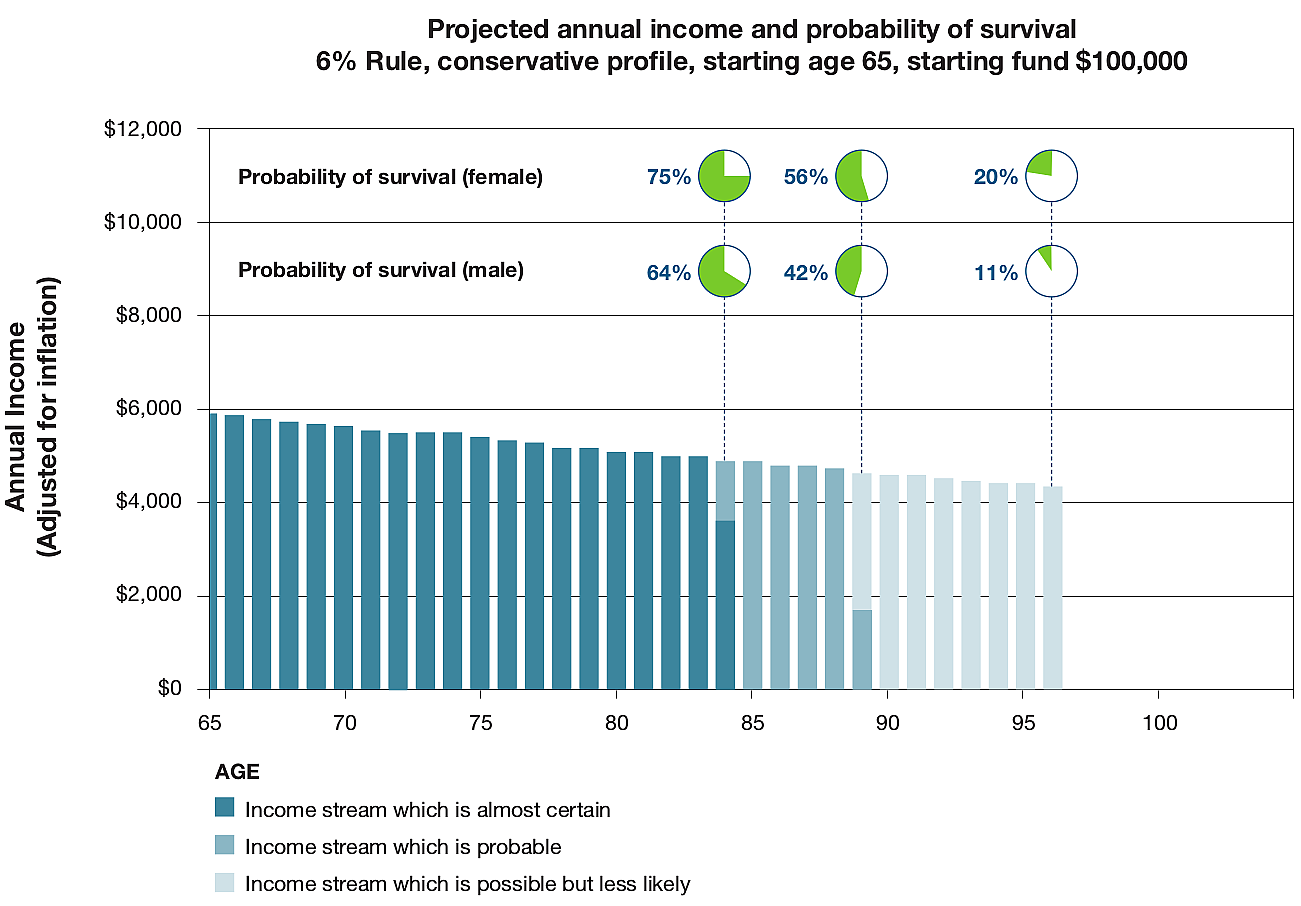
RULE 1: 6% RULE
| Rule | Most suitable for | Pros | Cons | Inheritance |
| Each year, take 6% of the starting value of your retirement savings. | People who want more income at the start of their retirement, to “front-load” their spending, and are not concerned with inheritance. | Very simple. Known, regular income. |
Income will not rise with inflation. Risk of retirement savings running out within lifetime. |
Average inheritance low if drawdown commences at age 65; larger if it commences at a later age. |
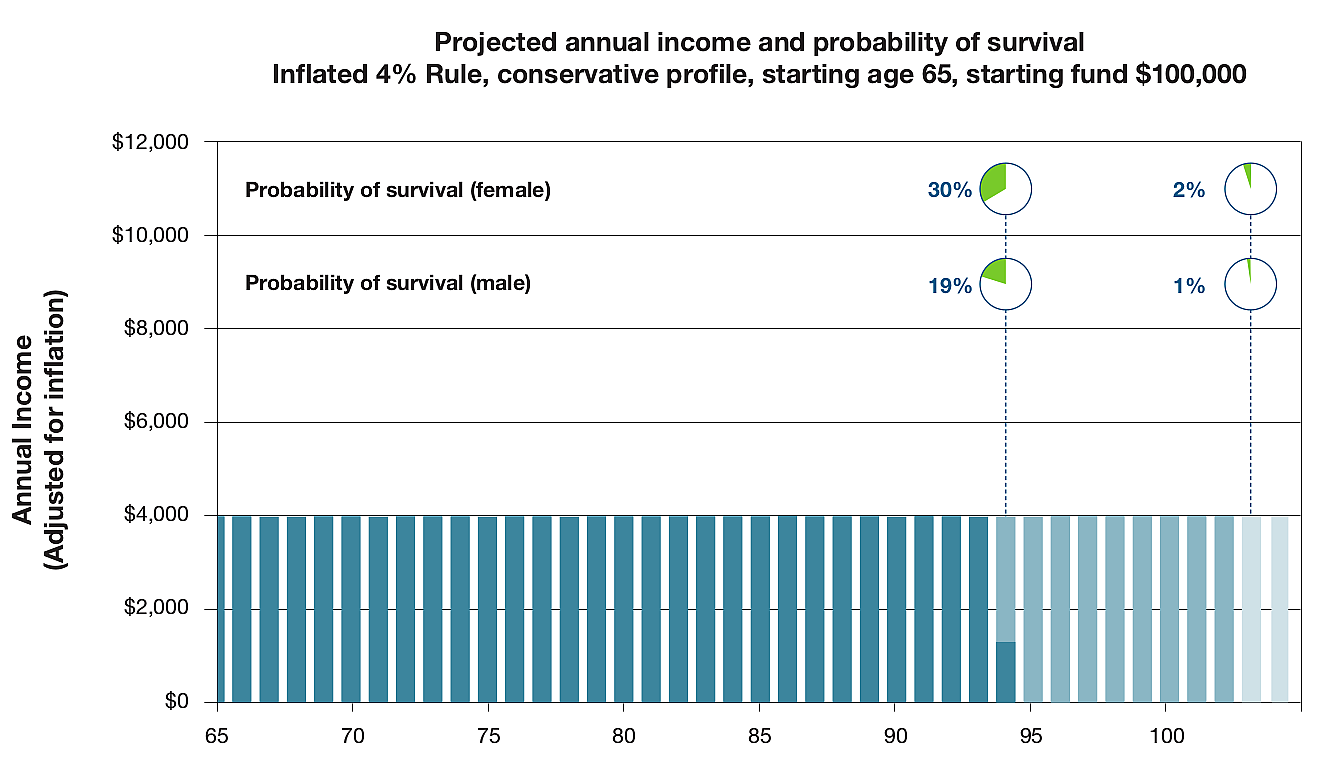
RULE 2: INFLATED 4% RULE
| Rule | Most suitable for | Pros | Cons | Inheritance |
| Take 4% of the starting value of your retirement savings, then increase that amount each year with inflation. | People worried about running out of money in retirement or who want to leave an inheritance. | Fund likely to last a lifetime. Income will rise with inflation. |
Lower income than other options. | Inheritance payment likely and average inheritance amount large in relation to starting value. |
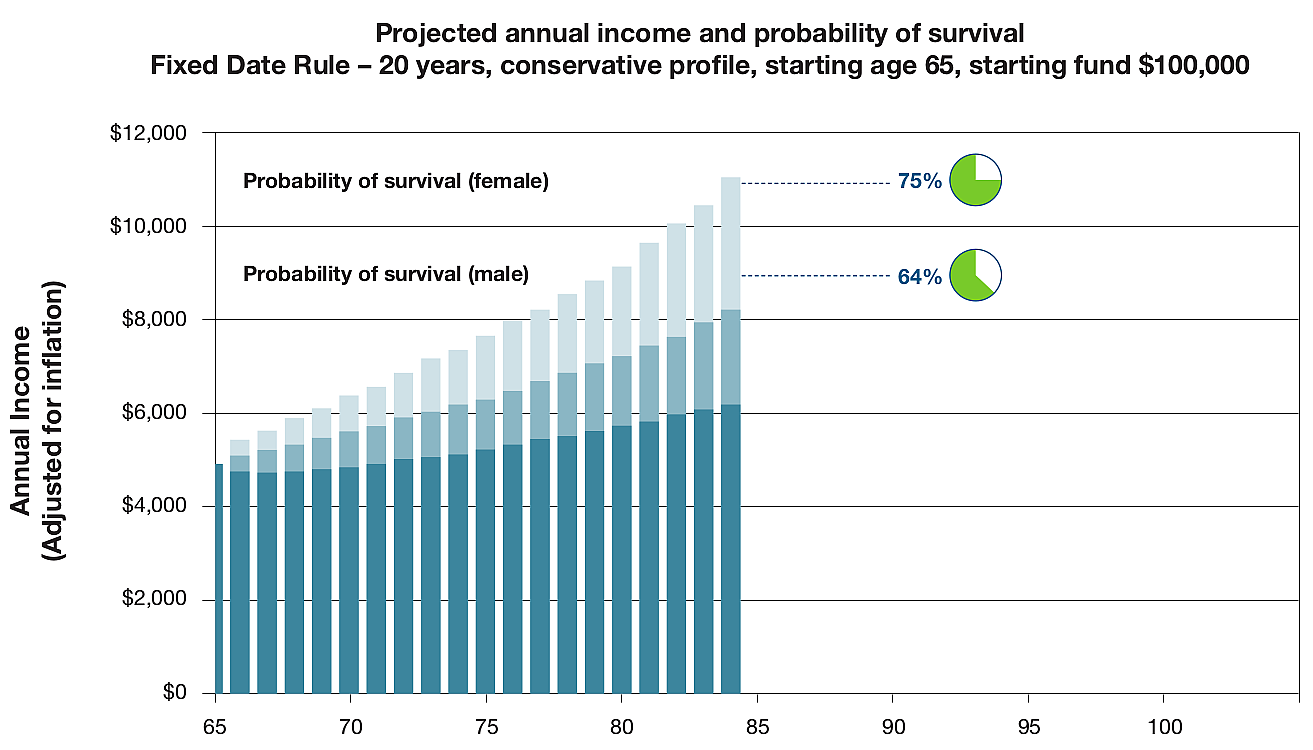
RULE 3: FIXED DATE RULE - 20 YEARS
| Rule | Most suitable for | Pros | Cons | Inheritance |
| Run your retirement savings down over the period to a set date – each year take out the current value of your retirement savings divided by the number of years left to that date. | People comfortable with living on other income (for example New Zealand Superannuation) after the set date. Those wanting to maximise income throughout life, not concerned with inheritance. |
Income for a known selected period. | Amount of income varies from year to year. Annual calculation necessary. |
Lowest average inheritance amounts. High probability of no inheritance, especially if selected date is age 85 or earlier; average inheritance amounts greater when selected date is later. |
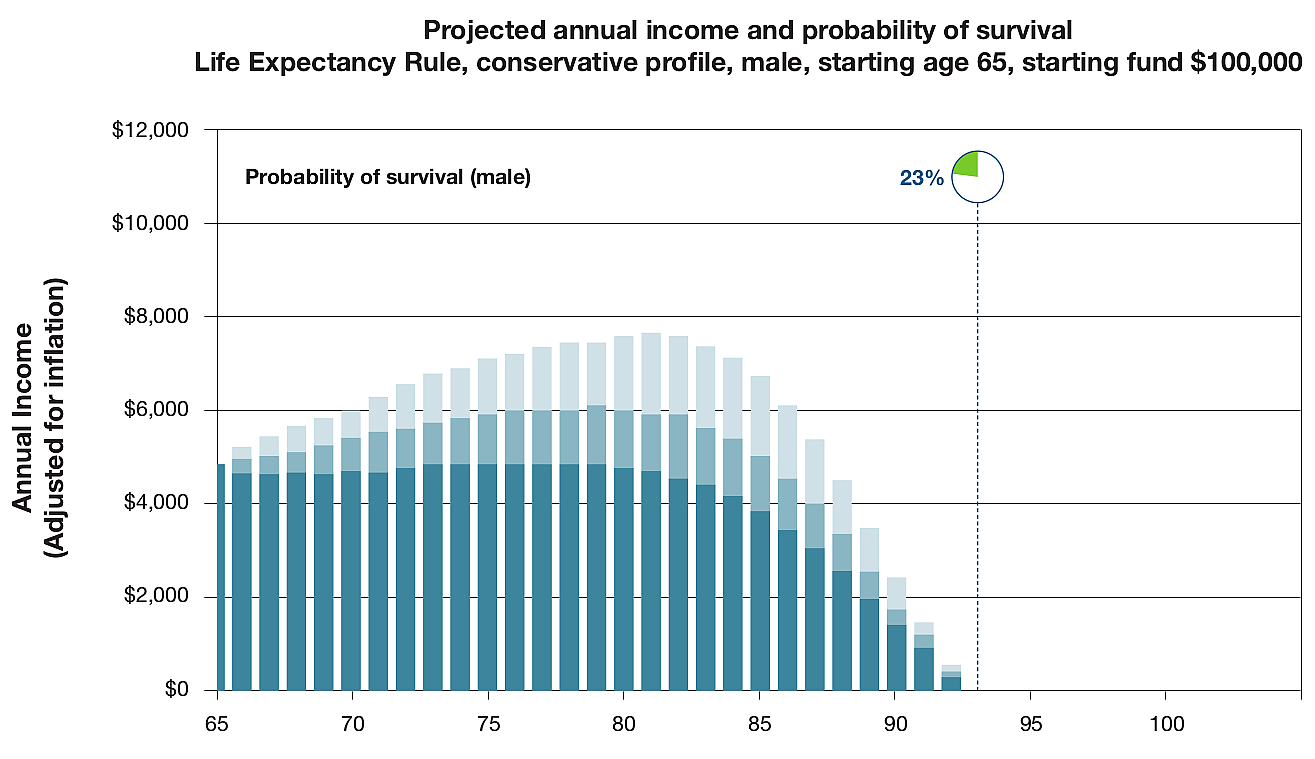
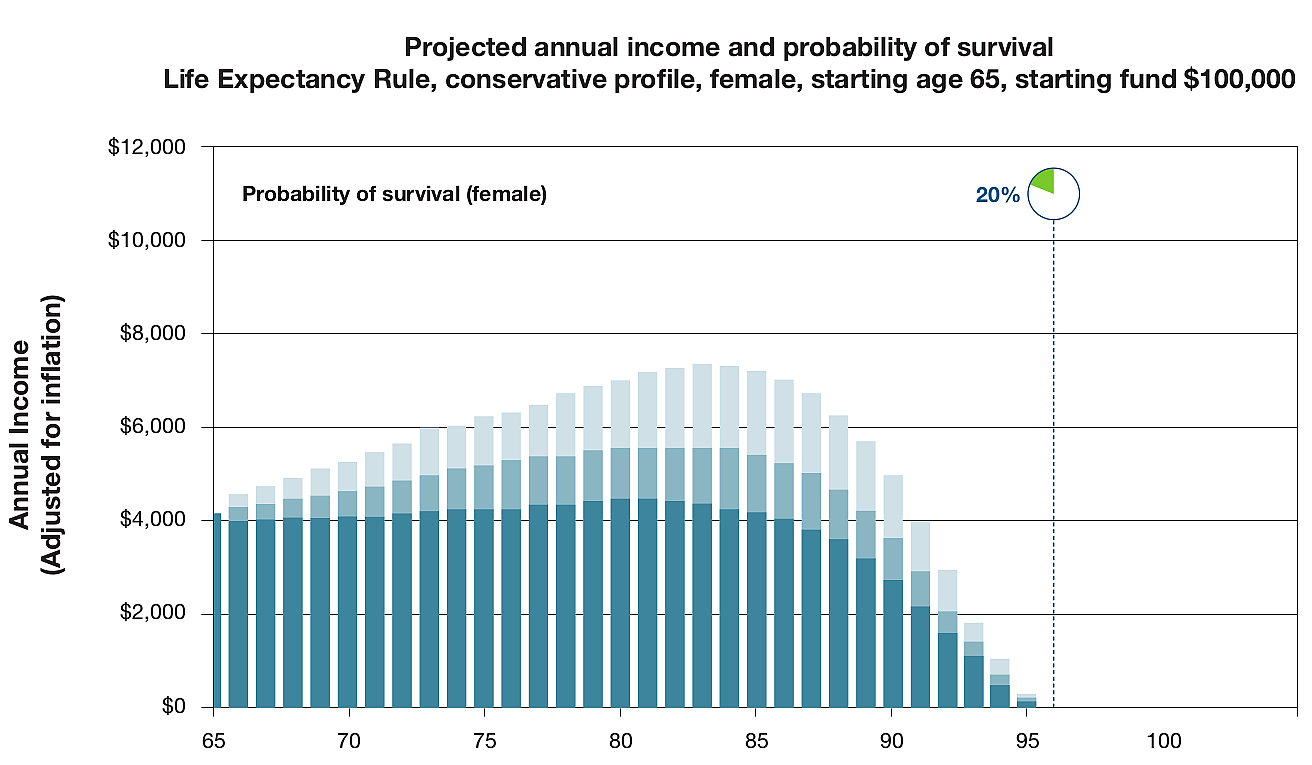
RULE 4: LIFE EXPECTANCY RULE
| Rule | Most suitable for | Pros | Cons | Inheritance |
| Each year take out the current value of your retirement savings divided by the average remaining life expectancy at that time. | Those wanting to maximise income throughout life, not concerned with inheritance. | Efficient use of fund to provide income for whole of life. | Amount of income varies from year to year; low in later years. Annual calculation necessary and relatively more complicated. |
Some inheritance normally paid; average inheritance amount moderate. |
While the Minister of Commerce and Consumer Affairs Minister Jacqui Dean has effectively endorsed the Society’s paper by launching it an event at Parliament, the Society says:
“We believe that Rules of Thumb will be most effective if there is a single set of Rules that is referenced widely and consistently.
“This set of Rules would be available to providers, distributors, regulators, commentators and others who communicate with New Zealanders on decumulation matters.
“There would need to be confidence in this set of Rules and we envisage the Financial Markets Authority approving a set of Rules for this purpose.”
For more on decumulation, see this interview interest.co.nz has done with the Retirement Commissioner. Diane Maxwell believes New Zealand's "love affair” with property is preventing our suite of financial products for retirees from growing as it needs to.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.