
Discussions around housing affordability often focus on how difficult it is for first home buyers to get into a home, with how current conditions are affecting the ability of existing home owners to move on up into their next home often overlooked.
Interest.co.nz's latest data suggests the kiwi passion, or should that be obsession, with moving up the property ladder remains a surprisingly affordable option for many, in spite of the currently high mortgage interest rates.
The data takes the example of a working couple who bought their first home 10 years ago at what was then the lower quartile selling price, and are looking to sell and move up to the next rung on the property ladder by buying a home at the current median price.
According to interest.co.nz's calculations this should be well within reach, because the couple would be likely to have accumulated enough equity in their original home to put a 50% deposit on a home at the current median price, and the mortgage payments on the balance would only take up just over a quarter of their after-tax pay, assuming they are on average rates of pay.
Let's take a closer look at the numbers.
A home at the the Real Estate Institute of New Zealand's national lower quartile price 10 years ago (February 2014) would have cost $280,000.
If that same property was sold at the February 2024 lower quartile price it would fetch $595,000.
Interest.co.nz estimates after the owners had repaid the mortgage and paid their selling costs such as agent's fees, they would be left with net equity of $392,309 to put towards another home.
Those calculations assume the original mortgage was for a 30 year term, had remained on the prevailing two year fixed rate and the owners had not made any lump sum payments.
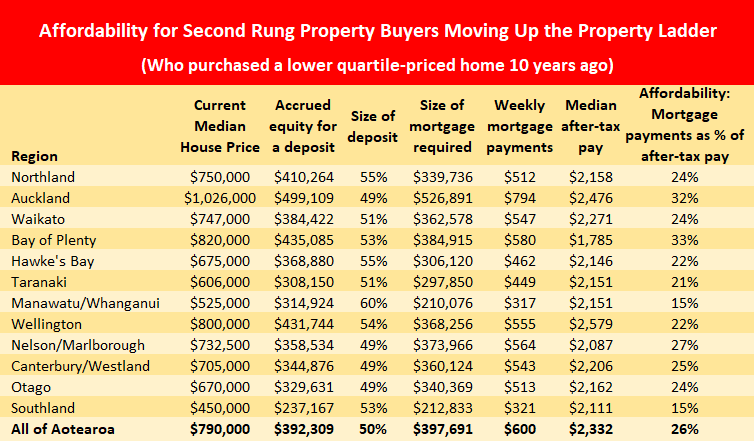
That would give them a 50% deposit (using rounded percentages) on a home home at the REINZ's February 2024 national median price of $790,000, meaning they'd also need to take out a mortgage for $397,691.
The mortgage payments on that would work out at about $600 a week.
Using median pay rate figures for people aged 34-39 would give the couple combined after-tax pay of $2332 a week.
That means the mortgage payments would take up 26% of their take home pay.
Essentially they would be able to move up the property with 50% equity on their new home and be paying about a quarter of their take home pay on the mortgage.
By almost any measure that makes moving up the property ladder an extremely affordable option, even for people on average wages.
Although there are regional variations on the above figures, they are not substantial.
For example, In Auckland, which is the second most expensive region for housing in the country (behind Queenstown), the same scenario as above would have given the home owners a 49% deposit on a median priced home, and while the mortgage payments would increase from a quarter to a third of take home pay, that's still well within affordable limits.
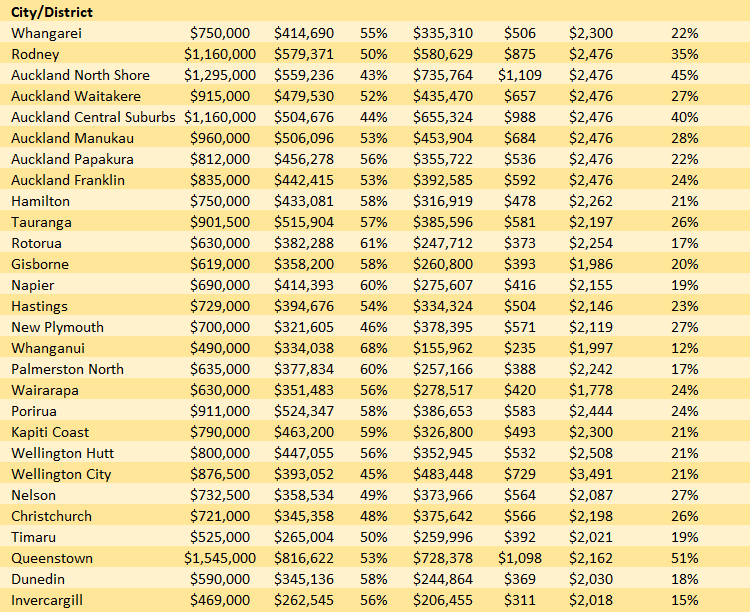
The table below shows the current affordability measures for the example given above, in all of the major urban centres around the country.
The comment stream on this article is now closed.
•You can have articles like this delivered directly to your inbox via our free Property Newsletter. We send it out 3-5 times a week with all of our property-related news, including auction results, interest rate movements and market commentary and analysis. To start receiving them, register here (it's free) and when approved you can select any of our free email newsletters.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.