By Andrew Coleman*
Between 1975 and 1977, New Zealand scrapped the compulsory saving scheme that was introduced in August 1974 and adopted what is now the most unusual retirement income and tax policies in the OECD. It is becoming increasingly obvious that this system has problems. To mark the 50th anniversary of the compulsory saving scheme, this series of articles re-examines whether New Zealand’s retirement income policies could be modified or redesigned to better suit the 21st century.
Pay-as-you-go and save-as-you-go retirement income schemes
The welfare and contributory pensions that most older people in OECD countries receive from governments differ significantly in terms of their philosophy and delivery mechanisms, but both can be organised on either a pay-as-you-go or a save-as-you-go basis. If a country has a welfare-based system organised on a pay-as-you-go basis, the taxes that are collected are immediately paid out as pensions and nothing is saved. This is largely what happens in New Zealand. If the same system were funded on a save-as-you-go basis, the taxes that are collected would be accumulated in a sovereign wealth fund and invested before the pensions are paid out at a subsequent date.
Whether a pension is operated on a pay-as-you-go or save-as-you-go basis is an “under the hood” issue that is often ignored. But just as the engine of a car affects its performance and fuel economy, pension schemes run on a pay-as-you-go basis and pension schemes run on a save-as-you-go-basis have very different consequences. They affect the overall structure of the economy, including the amount of capital people own and the way industry is financed; they affect how much it costs different generations to provide pensions; and they affect the way that the overall costs of a pension scheme are split between different generations. A rule of thumb based on one hundred years’ investment returns is that a pay-as-you-go pension scheme doubles the amount of taxes that people have to pay to get a pension. That is substantial – a bit like the different operating costs of a petrol and an electric car. Most current and future generations of young people would be substantially better off if the government had chosen a save-as-you-go funding system years ago – for instance, in 1977 or 1997, when previous generations voted for New Zealand Superannuation. Young people have inherited a system which is expensive and getting more expensive every year.
In the next three articles I shall examine several differences between save-as-you-go and pay-as-you-go schemes. This article looks at the effect on capital accumulation, while the next one looks at the circumstances where a pay-as-you-go system ends up costing young people much more than a save-as-you-go system. The third one discusses some of the transition difficulties that arise when you attempt to switch from a pay-as-you-go to a save-as-you-go pension scheme. Although this material is not often discussed in New Zealand, it is well established and based on the economic ideas developed in the 1950s and 1960s by four Nobel-prize winning economists, Peter Diamond, Franco Modigliani, Edmund Phelps, and Paul Samuelson. They showed the basic arguments are the same whether a country adopts a welfare-based or a contributory pension scheme, although some details change. Consequently, it is easiest to discuss the case where New Zealand keeps New Zealand Superannuation, but the funding is organised differently.
Save-as-you-go schemes and the 'bathtub' model
A mature government save-as-you-go pension scheme has three parts. The first part is a large government investment fund, like the New Zealand Superannuation Fund, but bigger. The second part is the payments made by young or working-aged people, which are paid into the fund rather than transferred to old people. The third part is the pension payments received by older people in the future. They will still get paid every fortnight, but the pensions are paid from the interest and dividends and profits earned from the investments made by the fund when they paid taxes earlier in their lives, plus some of the capital of the fund.
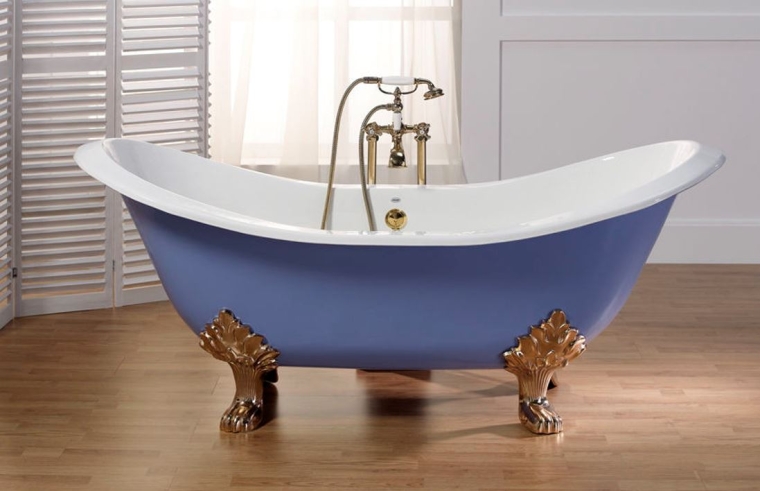
In some ways the fund can be likened to a big bathtub, with new water pouring in from a “tax-tap” at the top, and old water flowing out from a “pension plughole” at the bottom. A bathtub does two things. It creates a delay between when the water flows in and when it leaves; and it stores a lot of water. The difference with an investment fund is that the “water” in the “bathtub” expands as it earns interest and profits and dividends, increasing the volume in the tub without putting any more “water” in. The earnings of the fund mean less water needs to flow through the tap for any amount flowing out from the plughole.
A pay-as-you-go system is missing the tub – so it is like a pipe. The water coming out of the tax-tap goes straight out through the pension plughole and there is no chance for it to increase in volume. This doesn’t mean there isn’t a return to the people paying the taxes. If young people are born at a time that there are not very many old people, each person only has to pour a little bit of “tax” into the pipe for each older person to get a generous flow. In contrast, if there are lots of old people around each young person will have to turn the tax-tap up to ‘high’ to generate a sufficiently large flow for all the old people to have enough. This, in a nutshell, is the situation New Zealand increasingly finds itself in.
In contrast to a pay-as-you-go water-pipe, the inflows and outflows of a save-as-you-go system are not meant to be equal all the time. If there are lots of working-age people, the inflows will be greater than the outflows and the fund – the water level in the bathtub - will increase. If there are a small number of working-age people and lots of old people, the fund will decrease. This is the point: once the system matures, each generation will put in an amount that, combined with the interest and dividends and earnings, pays out the pensions they will receive when they are older many years down the track. The system can become intergenerationally neutral, because the amount each generation takes out reflects how much they put in at an earlier stage. This solves some of the problems that arise when generations are different sizes.
A save-as-you-go pension system accumulates more capital than a pay-as-you-go system – the extra “water” in the tub. When a government introduces or expands a pay-as-you-go system, saving and capital accumulation decline. The government raises taxes and immediately makes additional payments to retired people – just as if it siphoned off some of the water that was going into the bathtub and diverted it into a pipe. The retired people typically spend rather than save these additional pension payments. Since contemporaneous working-aged people are paying more taxes but are also expecting a larger pension in the future, they typically reduce their private savings and maintain their spending. In total saving decreases and spending increases and less capital is accumulated in the economy.
Of course, the working-age people become retirees in subsequent years. Their pensions enable them to spend, because of the taxes levied on new generations of young people who also have less need for private saving. The process is repeated year after year, and each subsequent generation ends up saving less and accumulating fewer assets. At the economy-wide level, the decline in saving means there is less locally-generated capital to invest in firms or infrastructure or in overseas countries. Unless this capital is fully replaced by foreign-sourced capital, this reduces the earnings of businesses and firms. It also reduces wages, as firms are less productive.
Something like this happened in New Zealand in 1977, when National Superannuation was introduced, and all people over 60 became entitled to a larger pension. There was an almost immediate decline in the national saving rate. This decline has not been fully reversed, even though the age of eligibility has subsequently been increased, as people are slower to cut consumption when taxes increase than to increase it when taxes decrease.
If New Zealanders had a pension scheme that was based on save-as-you-go funding, the amount of saving and the size of the capital stock would be larger. This has another implication: it could help in the battle to prevent climate change. We are all conscious of the rapid progress in solar and wind energy technologies in the last decade, and many more transformational technologies will be developed in the next 50 years. Many of these technologies are capital intensive and will only significantly reduce greenhouse gas emissions if they are implemented on a large scale at home and abroad. This will require large scale saving and investment. The pension funds of many countries already are making green energy investments in less developed countries, to help them increase their energy use without so much coal or gas. Greater domestic savings stemming from a save-as-you-go funded pension scheme will enable New Zealand firms to increase the amount they already invest in these types of projects.
If New Zealand changes from pay-as-you-go funded pensions to save-as-you-go funded pensions, New Zealanders will collectively save more, allowing them to finance some of these green investments and help tackle climate changes issues. More generally, greater capital under the save-as-you-go scheme boosts firm productivity, increasing earnings and wages. This sounds attractive. For young people it has another benefit – under many circumstances a save-as-you-go system can cost less, much less, than a pay-as-you-go system. This topic is tackled next week.
*This series and an accompanying paper are based on work I started in 2020 with Jeanne-Marie Bonnet while we were both at the University of Otago. I am very grateful for her assistance and insights. All errors remain my own.
(This article is part 3 in the series. Part 1 is here, and part 2 is here).
**Andrew Coleman is a visiting professor at the Asia School of Business. This article is his personal view of retirement policy in New Zealand, based on academic study.
Coleman is on extended leave from the Reserve Bank of New Zealand, while working overseas. The views expressed in this article do not represent the RBNZ and are unrelated to work conducted at the Bank, which has no responsibility for retirement policy in New Zealand.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.