By Andrew Coleman*
Fifty years ago this August, the Labour government passed the New Zealand Superannuation Act (1974) and introduced a contributory saving scheme. This scheme required people to pay 8% of their wages and salaries to the Government and in return offered them a pension based on the size of their contributions.
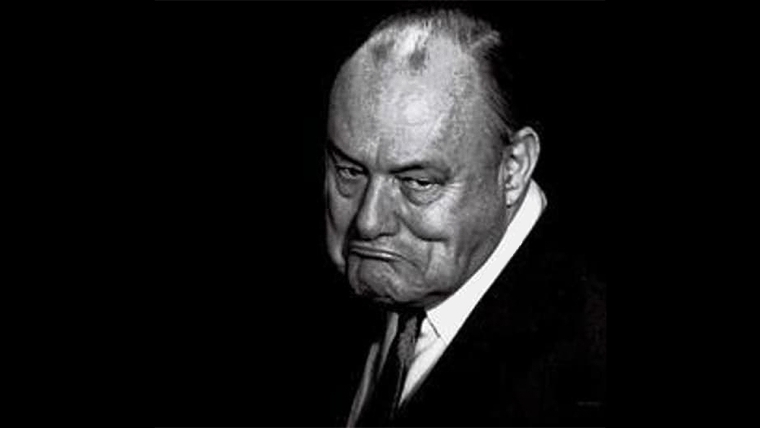
Between 1975 and 1977, the National Government led by Robert Muldoon revoked the Act and replaced it with a new universal retirement income scheme. After two decades of piecemeal reform by both major political parties, this scheme evolved into the current retirement income policy, New Zealand Superannuation. It provides a universal pension to all New Zealanders over 65 who satisfy eligibility criteria, funded from general tax revenues. Seen internationally, New Zealand Superannuation has one remarkable feature. It is fundamentally different from the schemes adopted in almost all other OECD countries.
Different, of course, does not mean bad. But while it has some very good features, the current structure of New Zealand Superannuation has three major downsides. Most importantly, it imposes very high costs on current and future generations of young people, who are required to pay much more in taxes than is necessary to provide the pensions they will receive. It means New Zealand eschews some of the most efficient taxes used around the world, but relies on taxes that artificially distort investment decisions and inflate property prices. And it exacerbates some dimensions of inequality. These are good reasons why none of the high income, low inequality countries of northern Europe have adopted the New Zealand model – and good reasons why the rapidly growing nations of the former Eastern European block have not copied it either.
A referendum held in 1997 overwhelmingly endorsed the new retirement income policy. Nonetheless, various governments since 2000 have expressed concern about the structure of New Zealand’s tax system and wondered about the future affordability of New Zealand Superannuation. In one major development, the New Zealand Superannuation Fund was established to change part of the funding of New Zealand superannuation from a pay-as-you-go-basis to a save-as-you-go basis. This step will reduce costs on future generations, although many New Zealanders, young and old, believe that more could be done.
Other aspects of the 1977 decisions have remained unchanged. In particular, New Zealanders fund current retirement income payments from general taxation, rather than social security taxes or contributions to compulsory savings plans that are used in most OECD countries.
The social security taxes that are used in most countries have two features: the taxes are used for specific purposes, primarily retirement incomes; and they are only applied to labour incomes. New Zealand uses a social security tax to fund contributions to the Accident Compensation Corporation, but it does not fund other social security payments in this manner. This is the single largest difference between the tax systems of New Zealand and almost all other OECD countries. Strangely, it is hardly ever discussed - neither the 2001 Tax Review, the 2010 Victoria University Tax Working Group, or the 2018 Tax Working Group devoted more than a page of discussion to the topic, despite its centrality to the tax systems of most OECD countries.
When Muldoon abolished the nascent contributory tax system introduced by the Labour Government in 1976, he cast a very long shadow over New Zealand’s subsequent tax system.
Its effects are not trivial: as a direct consequence of this choice, New Zealand has very high taxes on capital incomes and very low taxes on labour incomes relative to the rest of the OECD. These taxes artificially inflate house prices and delay the time it takes young people to afford their own homes.
Moreover, because there is no link between the taxes paid and the benefits received, the labour income taxes we use are more distortionary than the taxes used in other countries.
Over the next few weeks, I shall argue it is time for New Zealanders – or at least New Zealanders aged under 45 – to consider a fundamental restructure of New Zealand’s government retirement income system and its associated taxes. Why 45? – because nobody under 45 voted in the 1997 referendum that ensured New Zealand has the most unusual retirement system in the world.
These New Zealanders have spent and will spend their entire working lives in the 21st century, and it is my belief that they should be given the opportunity to decide on the types of taxes they pay, and the retirement incomes they receive, over the course of their adult lives. It should no longer be assumed that a tax and retirement system designed in the middle of the 20th century is suitable for the needs of people living in modern New Zealand.
Are there better ways to raise taxes and fund pensions? Many rich countries such as Norway, Sweden or Germany already collect more taxes than New Zealand – and they do it in ways which keep incomes high, and which generate less inequality than in New Zealand. These countries provide examples of tax system alternatives that are already tried and tested, and in many ways result in better outcomes than the New Zealand system. If young New Zealanders were to choose different types of taxes, they will not be sailing uncharted waters. Different methods of funding retirement incomes exist, and these may prove more appealing to young New Zealanders than the options chosen by their parents and grandparents.
The key requirement is the willingness to discuss the issue and find a solution. If New Zealand doesn’t do something sooner, it will have to do something bigger at a later date. If these discussions are not held now, and current pension entitlements are maintained, young people will face higher and higher taxes.
Young people might choose to pay higher taxes in the future to maintain current pension payments – or they could choose to reduce the pensions older people receive, or leave to countries where the balance between taxes paid and benefits received is more favourable. None of these possibilities are very attractive.
There are many different possibilities for reform. I shall suggest one, modelled on a scheme proposed a decade ago by the Financial Services Council. It combines a compulsory saving scheme with New Zealand Superannuation, like Australia, but with a twist that learns from the Australian experience. New Zealand Superannuation would be retained unchanged for people over 45. Of course, younger New Zealanders might want something completely different – or want no change. That should be up to them, albeit in conjunction with older citizens. Indeed, the purpose of the series is to explore some of the reasons why fundamental reform of New Zealand Superannuation may be desirable, not to argue for any particular replacement.
The international literatures examining retirement income systems and tax policies are simply enormous. This series of articles does not pretend to summarise them. Rather, its purpose is to reflect on of the ways New Zealand’s retirement and tax systems differ from those used in most countries; to discuss some of the social and economic consequences of these choices; and to analyse whether it might be possible to reform the current system to reduce its weaknesses while preserving its strengths. I hope you enjoy them.
*This series and an accompanying paper are based on work I started in 2020 with Jeanne-Marie Bonnet while we were both at the University of Otago. I am very grateful for her assistance and insights. All errors remain my own.
**Andrew Coleman is a visiting professor at the Asia School of Business. This article is his personal view of retirement policy in New Zealand, based on academic study.
Coleman is on extended leave from the Reserve Bank of New Zealand, while working overseas. The views expressed in this article do not represent the RBNZ and are unrelated to work conducted at the Bank, which has no responsibility for retirement policy in New Zealand.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.