

Welcome to our first of these daily summaries in 2022. Here are the key things you need to know before you leave work today.
MORTGAGE RATE CHANGES
No changes to report today.
TERM DEPOSIT RATE CHANGES
None here either.
SOPHISTICATED NEW SCAM
Westpac NZ is warning New Zealanders about a sophisticated new scam that involves a fake Westpac investment prospectus. The prospectus is formatted to resemble a Westpac document and includes professional-looking imagery. This is what it looks like. Westpac said the scammers had put significant effort into making the prospectus look authentic. “Would-be investors are encountering this scam when they do internet searches for information about investments and term deposits. These people are asked to enter personal contact details on the websites which come up in the search results, some of which may purport to help people compare investments. The scammers then email or call the would-be investor using those contact details.” They noted written and verbal communications from the scammers used convincing language and appeared credible. “We have had a handful of reports about the scam so far. We want people to be vigilant and report any suspicious activity so our financial crime team can investigate.”
DECEMBER 'PROVES' THE HOUSING MARKET WILL BE DIFFERENT IN 2022
The housing market was considerably slower in December compared to a year earlier. According to the December REINZ data, there was a big decline in December sales and prices were weaker too. Infometrics says the market has turned a corner. Westpac sees the data showing higher mortgage rates and tighter lending restrictions are having an impact. ANZ says the data confirms the market is slowing. Kiwibank says the housing market looks to have finally cracked.
BUSINESS CONFIDENCE TURNS DOWN TOO
NZIER’s QSBO shows weaker demand and confidence. Just as inflation pressures accelerate, business confidence sinks. More than half of surveyed businesses are to raise prices in early 2022. ANZ says businesses are fretting about inflation and the pandemic. "Today’s data is more evidence showing that the labour market and inflation are probably even further beyond the RBNZ’s targets than they (or we) thought when the November MPS forecasts were published." Westpac says "The persistence of inflationary pressures was one of the reasons why we think that a series of OCR increases in rapid succession will occur this year."
RETIREMENT SECTOR STRUGGLES, LOSING INVESTOR INTEREST
Investors who piled into the retirement/rest-home sector expecting easy gains are probably feeling disappointed. Last week the listed companies in this sector lost -3.3% of capitalisation, getting on for nearly twice the overall market decline of -1.9%. Year-on-year these companies have lost -6.0% of capitalisation whereas the overall market has lost -2.3%. Despite only being 8% of the overall capitalisation, these companies have lost -21% of all the past year's pullback, some -$640 mln. The big loser last week was Summerset (SUM, #14) which fell -3.5% in those seven days. But everyone declined - the least was Arvida (ARV, #29) which shed 'only' -2.5% in the week.
FLP ACCESSED AGAIN
Late last week, another major bank dipped into the RBNZ's Funding for Lending facility, taking $500 mln. Bank treasurers are probably feeling the RBNZ could end this piggy-bank availability soon, so if they need the funding, now is the time - certainly before the February 24 MPS. The FLP has now disbursed $7.2 bln of the $28 blnb originally allocated. It costs banks OCR, so at the moment this is funding at 0.75%. Once allocated, they have this funding for three years
LOOKING FOR A FAST FINISH
There is another dairy auction early tomorrow morning, the 300th since this system was started. Since the last event, Fonterra has advised that New Zealand milk volumes will be about -1.6% lower this season than originally anticipated. The peak was well and truly passed now so there is little chance of making the shortfall up. The dairy futures market is suggesting that the WMP price could rise by as much as +9% and the SMP price rise by +3.5% tomorrow. Of course, anything like this will underpin a strong milk payout price.
UST 10yr YIELD MARCHES UP
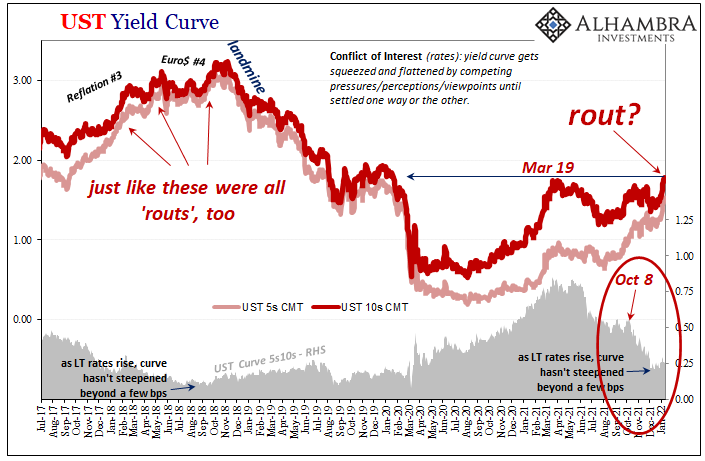
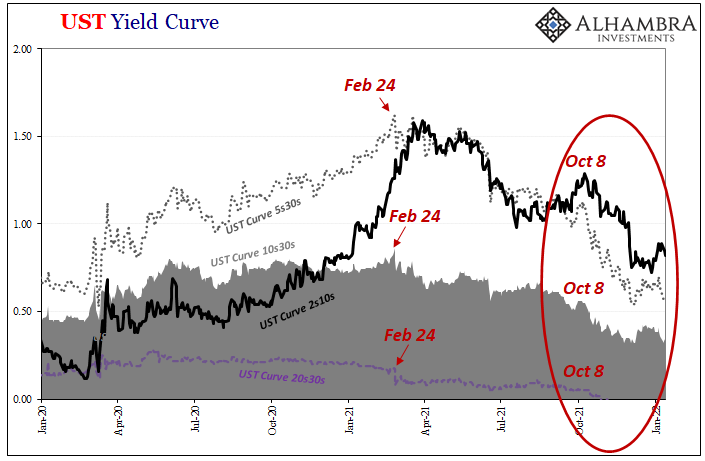
With the US financial markets closed, you might think global interest rates would stay little-changed. You would be wrong. The benchmark UST 10 year yield has risen today to 1.82% and a one year high. There is growing market conviction that the Fed will start raising rates in March, and possibly more aggressively than previously thought. But also see below.
LOCAL PANDEMIC UPDATE - AUSTRALIA'S DEADLIEST DAY
In NSW, there were 16,067 new community cases reported yesterday, a sharp fall, now with 326,356 active locally-acquired cases (and undoubtedly an undercount), and 33 more deaths. There are now 2,850 in hospital there. This is confirming the NSW Chief Health Officer's recent warning there will a high number of deaths in coming days. In Victoria they reported 20,180 more new infections yesterday, and little relief. There are now 235,035 active cases in that state - and there were 22 deaths. A "Code Brown" (mass casualty event expected) has been declared in most major Victorian hospitals. Queensland is reporting 15,962 new cases and 16 new deaths. In South Australia, new cases have risen to 4,685 yesterday with no more deaths. The ACT has 1601 new cases and 1 death and Tasmania 1310 new cases. Overall in Australia, 73,258 new cases have been reported so far although not all counts are in yet. In New Zealand, there were 30 cases stopped at the border, plus 14 new cases in the community.
GOLD FIRM
In early Asian trading, gold is at US$1821/oz and up US$6 from thsi tiem yesterday.
EQUITIES MOSTLY RISING, EXCEPT THE NZX50
The NZX50 is down -0.2% near the close of trading today. The ASX200 is up +0.3% in early afternoon trade. Tokyo has opened up +0.7% in late morning trade. But Hong Kong has opened up +0.6% and while Shanghai has opened up +0.2%. US markets are closed for a public holiday (MLKing Day).
SWAPS UNCERTAIN
We don't have today's closing swap rates yet. They are likely to be little-changed although a jump in the UST 10yr is an unexpected twist for the long end. The 90 day bank bill rate is up +1 bps at 1.05%. The Australian Govt ten year benchmark bond rate is unchanged at 1.91%. The China Govt 10yr is soft at 2.80%. The New Zealand Govt 10 year bond rate is now at 2.54% and up +1 bp but still below the earlier RBNZ fix for that 10yr rate at 2.58% (up +3 bps). The US Govt ten year is now at 1.82% and +3 bps even though Wall Street is closed.
NZ DOLLAR UNCHANGED
The Kiwi dollar is holding at 68 USc and unchanged. Against the Aussie we are also marginally softer at 94.2 AUc. Against the euro we are little-changed at 59.5 euro cents. That means the TWI-5 is still just over 72.2 and unchanged.
Appreciate this coverage? Support us and go ad-free. Find out how.
BITCOIN DOWN AGAIN
The bitcoin price has slipped to US$42,287 and lower by -1.4% from this time yesterday. Volatility over the past 24 hours has been modest at just over +/- 1.7%.

This soil moisture chart is animated here.
Keep ahead of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.