

Here are the key things you need to know before you leave work today (or if you already work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
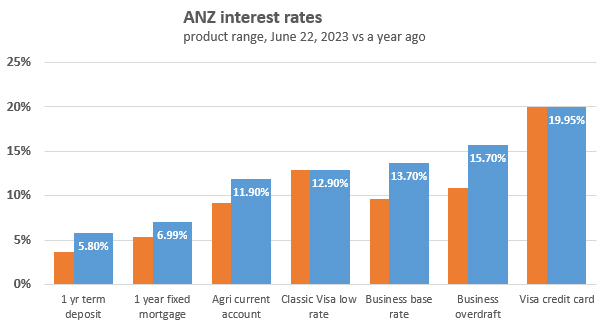
First Credit Union rated floating and fixed rates today. And ANZ raised some non-mortgage rate for business clients taking their Business Indicator rate to 13.7% and their business overdraft rate to 15.7%. Home loan borrowers, especially investors, must feel like they are getting a great deal. See this.
TERM DEPOSIT/SAVINGS RATE CHANGES
ANZ raised most TD rates from 1 month to 1 year late yesterday. Their new 6 month rate is up +10 bps to 5.65% and their new 1 year rate is up similarly to 5.80%. Unity Money raised its 9 month TD rate to 5.60%.
PAYING OUR WAY?
Despite our export values exceeding the value of imports by +$46 mln in May, the running annual deficit hit a new all-time high of over $17.1 bln. The monthly surplus is more than -$100 mln less than we had in May 2022.
$1 BLN PAID SO FAR
Our $3 billion weather woes may linger for some time says the Insurance Council. They report a little over a third of claims have so far been paid out for the twin weather events early this year; warns some claims could take over a year to settle.
HOT DEMAND
Today's Government bond tenders were swamped with demand. And that drove yields lower (in contrast to recently rising secondary market yields). The May 2030 $200 mln offer got 50 bids totalling $820 mln, and the ten winners bid a yield of 4.50% and very similar to what it was in the equivalent tender two weeks ago (4.52%). The May 2023 $150 mln got 52 bids worth $739 mln and only 7 were successful. They took a yield of 4.52%, down from 4.58% two weeks ago. And the April 2037 $50 mln attracted 29 bids worth $199 mln. The 8 successful bidders here got a yield of 4.63%, down from 4.69% two weeks ago. So all up 25 bidders won something out of the massive $1.758 bln from 131 bids. That is 3.4 times oversubscribed.
IMPROVING THE FRAMEWORK FOR SHARING DATA
MBIE is seeking feedback on the Customer and Product Data Bill. This proposed new law will govern the sharing of consumer data. They say it "will give customers more control over their data, allowing them to safely and securely access, manage, and share this data with others. When businesses like banks, power companies and mobile phone companies provide us with services, data is created – for example, account histories, transaction records or information on usage. This is ‘customer data’. It is held by businesses and is protected by business security measures (as well as the Privacy Act 2020 in the case of personal information). Customer data holds enormous value and opportunity, but only if customers can make full use of it by choosing to share it with applications and people they trust." This summary isn't that helpful to understand what they are on about, so perhaps this will help? It seems it is creating rules so businesses can use the data 'safely' in the hope consumers will benefit. Anyway, it does deserve closer inspection, and now is the time to give feedback.
GOING FLAT
Although actual domestic credit card billings rose +$530 mln in May from April, on a seasonally adjusted basis they were lower and the trend isn't positive. Considering year-on-year inflation levels too, the longer term billing levels also tell a story of spending exhaustion. Keeping spending up is what we are putting on them overseas. More here. We've stopped paying down our balances now, ending a long 3+ year period of this virtuous behaviour. And in 2023 there hasn't been the drive to pay off interest-bearing debt that there has been since 2001 (pandemic excepted).
SWAPS RISE
Wholesale swap rates are likely ending today firmer especially at the longer end. However, the real action in swap rates comes near the close. Our chart will record the final positions. The 90 day bank bill rate is unchanged at 5.68% and +18 bps above the 5.50% OCR. The Australian 10 year bond yield is down -1 bp from yesterday at 3.96%. The China 10 year bond rate is up +1 bp at 2.72%. And the NZ Government 10 year bond rate is at 4.57% and up a sharpish +9 bps, and that is still much higher than the earlier RBNZ fix which was up +5 bps to 4.48%. The UST 10 year yield is now at 3.73% and down -1 bp from yesterday.
EQUITIES FALL
Wall Street was down another -0.5% on the S&P500 at the end of its Wednesday trade. Tokyo has opened its Thursday session down -0.1%. Hong Kong is closed and on holiday today (Tuen Ng Day). Shanghai is also closed for the same Dragon Boat Festival. The ASX200 is down a very sharp -1.5% in afternoon trade. The NZX50 is down its own -0.7% in late trade.
GOLD LOWER AGAIN
In early Asian trade, gold is at US$1932/oz and down another -US$6 from this time yesterday. It ended in New York at US$1933/oz, and earlier in London at US$1926/oz.
NZD RISES
The Kiwi dollar has firmed today from this time yesterday, up +40 bps and now at 62.1 USc. Against the Aussie we are up +60 bps at 91.4 AUc. Against the euro we are unchanged at 56.5 euro cents. That means the TWI-5 is higher at 69.9.
BITCOIN RISES FAST AGAIN
The bitcoin price has risen very sharply again today and is now at US$30,139 and up another +4.7% from this time yesterday. Institutional interest is said to be behind the move. And volatility has been high at +/- 3.6%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs

This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.